Let’s be honest: when you hear “2 million net worth at 40,” your brain probably does one of two things. Either it pictures a smug guy in a Tesla with a $40 juice cleanse, or it immediately starts doing the math on your own 401(k) and feels personally attacked. The truth is, hitting that number at forty is less about being a genius and more about being a very stubborn squirrel who refuses to stop hiding nuts for twenty years.
We’ve all got that one friend, Dave, who bought Bitcoin in 2013 “for fun” and now pays for his kid’s college with the change. But for most of us, the path to two million feels like trying to bake a sourdough loaf—it requires patience, a lot of flour (or savings), and you’ll probably have a few flat, embarrassing failures before it finally works.
The Mirage of the Millionaire Next Door
Here’s the kicker: if you hit $2M by 40, you probably don’t feel rich. You’re still arguing with your spouse about whether the $6 avocado is a “family staple” or a “luxury item,” and you’re still wearing that one good Patagonia jacket from 2016 to every event.
Must Read
You don’t have a yacht. You have a used Subaru with a mysterious rattling noise that you’ve decided to name instead of fix. The joke is that $2M is the new “comfortable” but it comes with a side of chronic anxiety about whether the plumbing will explode the same week the stock market dips.
It’s like being the bouncer at a club you’re not allowed inside. You’re close to the VIP section, but you’re still eating cold pizza in the parking lot, just in a nicer parking lot.
How the Math Actually Works (Without Winning the Lottery)
For most 40-year-olds with $2M, it wasn’t a single lucky stock tip. It was the slow, boring grind of maxing out your 401(k) while your buddy was buying a boat. It’s saying “no” to the premium cable package for a decade and “yes” to every free conference with a sad sandwich lunch.
It’s also about doing the compound interest shuffle. You start at 25, stashing away $500 a month, and by 35 you realize that the market’s volatility feels like a rollercoaster you’re stuck on—terrifying, but you’re slowly going uphill. By 40, the ups and downs are just background noise, like that neighbor’s barking dog you’ve learned to sleep through.
And let’s not forget the one-two punch: you either got a decent salary bump and didn’t inflate your lifestyle, or you married someone who also hates spending money. Finding a partner who says “let’s cook at home” instead of “let’t order $80 of sushi” is like finding a unicorn that does your taxes.
The Unspoken Costs of Being “Fine”
Here’s what nobody tells you about a $2M net worth at 40: you still panic about the future. You know that number is great, but you also know that private college tuition for two kids feels like buying a small house every September.
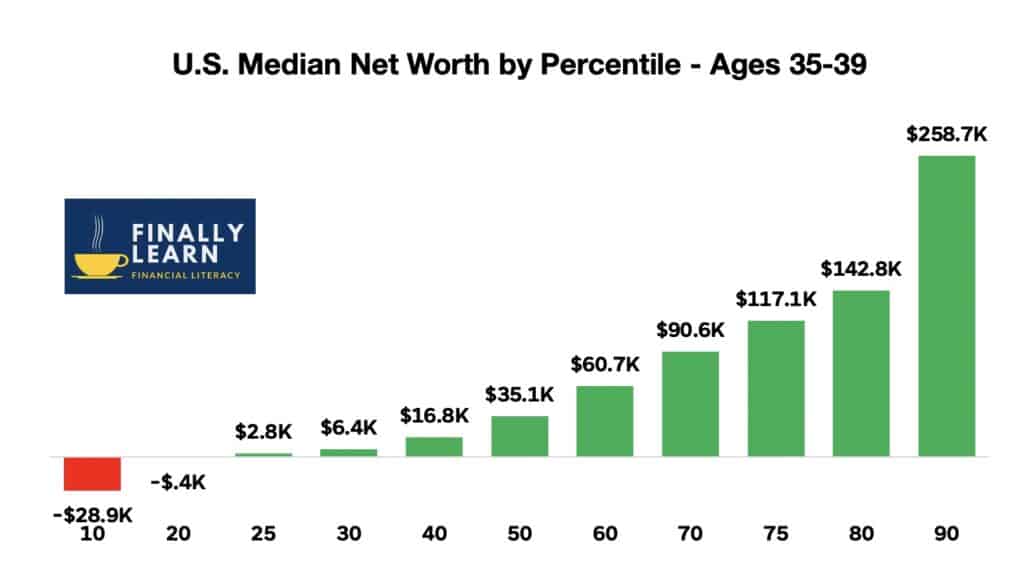
 Average Net Worth By Age – How Americans Stack Up | Money Guy
You’ll catch yourself checking your portfolio while waiting for your kid’s soccer practice to end, and the moment your balance drops $10,000 in a week, you’ll feel a phantom pain in your chest. Then you remember you’re not broke—you’re just temporarily losing imaginary money that you don’t need until you’re 65.
The real wealth flex isn’t the number; it’s the ability to say “I’m not worried about the grocery bill” while still clipping coupons for cat litter. It’s the luxury of a quiet panic attack rather than a loud, “I’m going to be homeless” one.
The Comparison Game is Rigged
If you’re 40 and have $2M, you’ll inevitably compare yourself to the guy who retired at 35 and now posts photos of his Costa Rica “office.” That guy is either lying, inherited a plumbing business, or has a tiny trust fund that he’ll burn through by 50.
Meanwhile, you have a job that still requires you to attend “synergy meetings” on Zoom. That juxtaposition is the comedy gold of personal finance—you have a balance sheet that looks healthy, but your soul is still attached to a laptop with a cracked screen.
But here’s the secret handshake: reaching $2M isn’t about being rich. It’s about having enough to say “no” to a bad boss, “yes” to a sabbatical, or “maybe” to fixing the dishwasher for another month. It’s the financial version of a dad bod—you’re not in peak physical shape, but you’re wonderfully comfortable in your own skin.
So if you’re 30 and reading this, start saving those nickels. And if you’re already there at 40, congratulations—now go change the air filter in the HVAC unit, because that’s what rich people actually do with their spare time. You’re not on a yacht; you’re just enjoying a slightly less stressful trip to Costco.