
You know that friend who casually drops “we’re just trying to build our net worth” into a brunch conversation? Yeah, we all have one. But behind the hustle-culture lingo and the “passive income” Pinterest boards, there’s a pretty wild reality about what the average American family actually has stashed away.
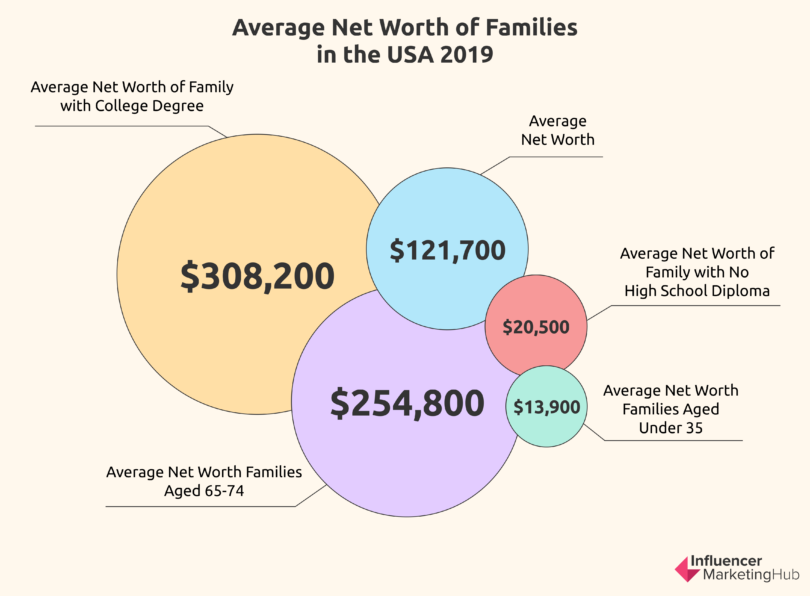
Let’s talk numbers, but without the spreadsheet-induced anxiety. According to the Federal Reserve’s latest Survey of Consumer Finances, the median net worth for a U.S. family is around $192,000 (as of 2022 data). That’s the halfway point—half of families have more, half have less. The average net worth, however, is a staggering $1.06 million, which tells you the ultra-wealthy are pulling that mean way, way up.
So, why the giant gap? Because a handful of billionaires and tech moguls inflate the average, making the “typical” feel like a failure. The median is your true mirror—it reflects the actual, lived experience of most people, not the guy who just sold his fintech startup for nine figures.
Must Read
The 30,000-Foot View: What’s In the Wallet?
Your net worth is simply everything you own minus everything you owe. Think: home equity, retirement accounts, checking balances, investments, and that beat-up kayak—minus credit card debt, student loans, and your car loan. It’s not about how much you earn; it’s about how much you keep.
And here’s the kicker: home equity is the single biggest driver of wealth for most families. For the median homeowner, equity makes up about 42% of their net worth. For renters, that number is basically zero, which is why owning a home is often the fastest path to building a safety net—even if you have to paint the bathroom yourself.
Fun fact: The age of your head of household matters more than your salary. Folks under 35 have a median net worth of about $39,000, while those aged 65-74 are sitting pretty at $410,000. Slow and steady doesn’t just win the race—it buys the condominium with the view.
Why You’re Probably Doing Better Than You Think
Social media is a highlight reel, not a financial statement. When you scroll past a rented Lamborghini or a “#girlboss” vacation, remember that most of those are funded by credit cards, not savings. The actual average American family drives a Toyota, shops at Costco, and worries about property taxes—not private jets.
Here’s a cultural reference for you: remember the Friends episode where Monica and Rachel’s apartment is impossibly huge for two waitresses? That’s the same illusion that messes with your financial headspace. The “average” lifestyle you see on TV is fiction; the median is your neighbor who mows his own lawn.
Another fun fact: approximately 1 in 5 U.S. families has a net worth of zero or negative. That’s not a judgment—it’s a red flag that the system is wobbly. But it also means that if you have even $5,000 in savings, you’re ahead of a shocking number of people. Perspective is your cheat code.
Practical Tips to Move the Needle (Without Losing Your Sanity)
First, track your liquid assets, not your income. It’s easy to feel “broke” with a $90k salary and $1,500 in checking. Shift your mindset from “how much I make” to “how much I’m keeping after the dust settles.” Open a savings account that’s annoying to access—out of sight, out of mind.
 What Is Your Net Worth? (+ FREE Net Worth Calculator)
Second, automate your retirement contributions like it’s a subscription service. Even $100 a month into a 401(k) with an employer match is a magic compound-interest lever. Over 30 years, at a 7% return, that’s over $120,000—and you never felt a thing. That’s the ultimate passive move.
Third, stop financing depreciating assets. That new $50,000 SUV loses 20% of its value the second you drive it off the lot. The average family hits their net worth goals by buying 3-5 year old used cars and holding onto them for a decade. Boring? Yes. Effective? Extremely.
The Race Isn’t About Them, It’s About Future You
Let’s do a quick reality check with the Schitt’s Creek mindset: the Roses lost everything and still found joy in a motel. Your net worth is a tool, not a scoreboard for your self-worth. If you’re drowning in debt, your first goal is to flip the negative to zero, and that alone is a win worth celebrating with a cheap bottle of rosé.
And don’t forget the invisible assets: your health, your network, your ability to learn. A 2023 study showed that people with a strong social circle tend to have higher financial resilience. Your buddy who knows about tax deductions is worth more than a gold bar.
Finally, don’t obsess over the monthly fluctuations. The stock market is a rollercoaster; your net worth will dip and spike like a EKG. Check it quarterly, not daily, and you’ll avoid the nausea that makes people sell low and buy high.
So, here’s the honest reflection: The average family net worth isn’t a destination—it’s a mirror. It shows you where you stand today, but it has zero power over where you’ll sit in ten years. Whether you’re at $5,000 or $500,000, the only meaningful comparison is with the version of you who didn’t start saving last year. That person is poorer, more stressed, and probably eating instant noodles. You’ve already won the most important race—the one against complacency.
Tonight, when you scroll past that influencer’s yacht, just smile, check your 401(k) balance, and remember: the median American is quietly building wealth while the loudest ones are just building debt. And honestly? That’s a pretty good place to be.