So, I was out for a walk the other day, you know, just enjoying the sun, when I bumped into old Tim. Tim's a retired guy, always has a smile on his face, and he's got this certain je ne sais quoi about him. I mean, the guy's always whistling, and he's got this little spring in his step that makes you think, "Hey, retirement's not so bad!"
Anyway, I got to thinking, "What's Tim's secret?" I mean, sure, he's got that pension from his old job, and he's got his Social Security, but is that really enough to keep a smile on your face day in and day out? So, I did a little digging, and guess what I found? There's this thing called the average net worth at retirement in the US, and it's kind of an eye-opener.
So, What's the Average Net Worth at Retirement?
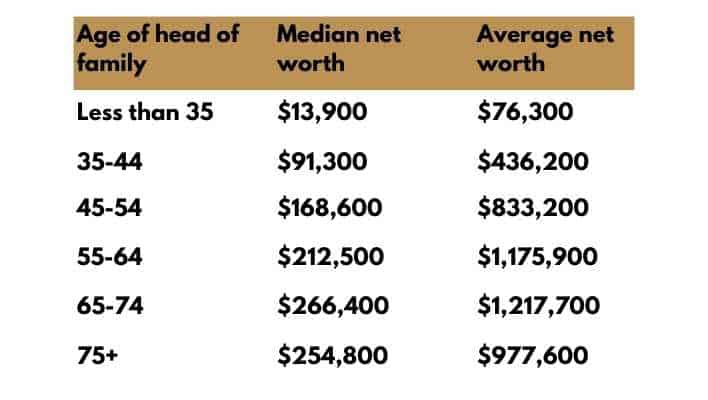
Alright, so let's get down to brass tacks. According to a study by the Federal Reserve, the average net worth at retirement (for households headed by someone 65 or older) is around $264,000. Now, that's the average, so some folks have more, some have less. But let's break that down a bit, shall we?
Must Read
First off, let's talk assets. These are things like your home, your savings, your investments. The average retirement-age household has about $200,000 in assets. Now, that's not too shabby, right? But here's where it gets interesting. The median (that's the middle number, the one that splits the list in half) is only about $60,000. So, half of all retirement-age households have less than that.
Now, let's talk debt. Yeah, I know, nobody likes to talk about it, but it's a reality for a lot of folks. The average retirement-age household has about $30,000 in debt. That's not great, but it's not the end of the world either. The thing is, though, that debt can eat into your net worth, and it can make retirement a whole lot tougher.
But What About Tim?
You might be wondering, "What about Tim? Where does he fit into all this?" Well, I asked him, and you know what he said? He said, "I don't know about all that, but I know I've got enough to live on, and that's all that matters." And you know what? He's right. It's not about having the most money, it's about having enough to live comfortably.
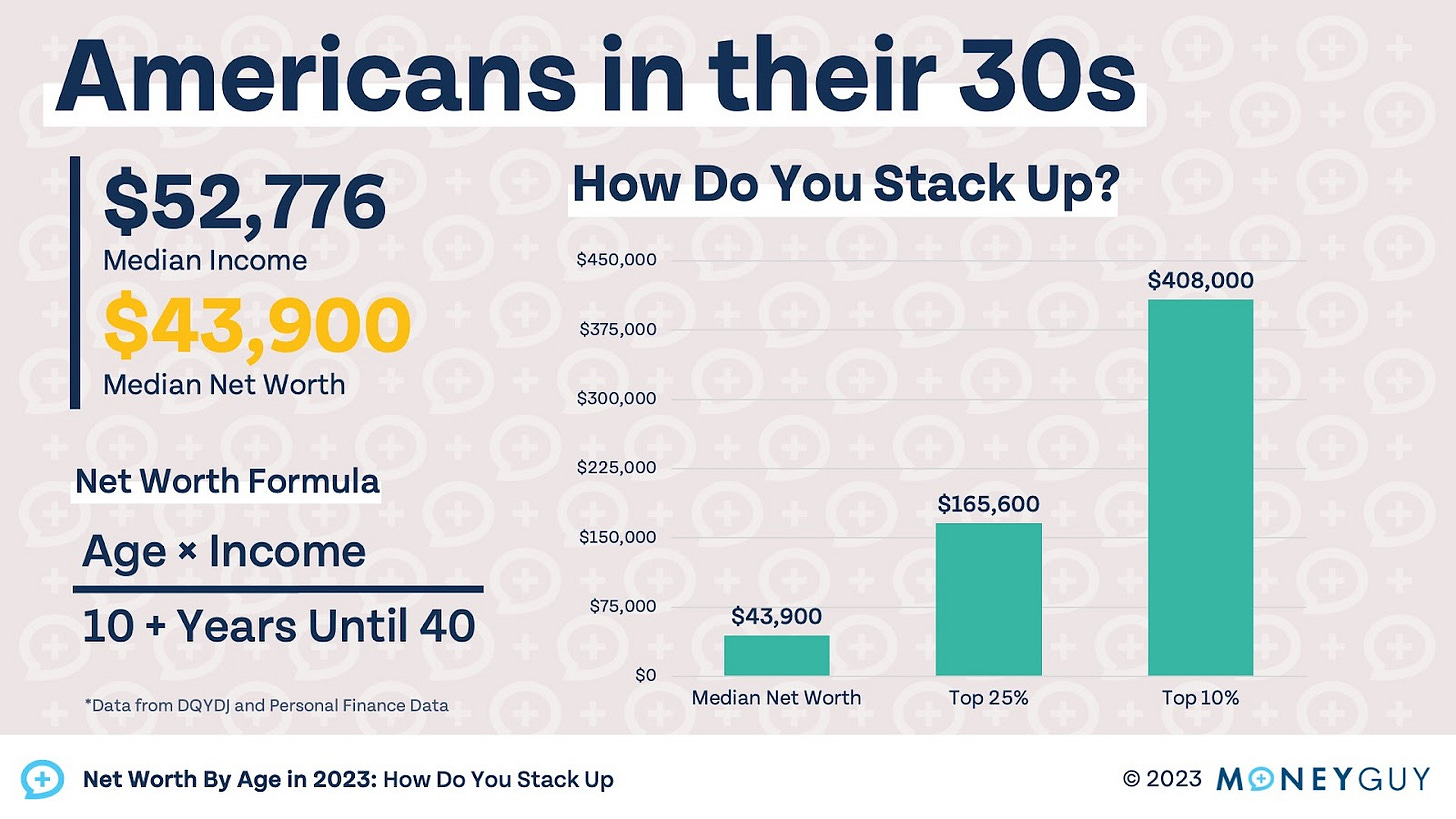 Net Worth By Age in 2023: How Do You Stack Up? | Money Guy
But here's the thing, folks. Tim's not an anomaly. He's not some lucky guy who just happened to stumble into retirement with a smile on his face. He planned for it. He saved, he invested, he paid off his debts. And that's something we can all do, no matter where we are in our careers.
So, What Can We Learn From This?
Well, first off, we can learn that retirement isn't just something that happens to us. It's something we can plan for, something we can work towards. And that's a powerful thing to know.
We can also learn that it's not just about having a big pile of money. It's about having enough to live on, enough to enjoy life, enough to keep that spring in your step. And that's a goal we can all strive for.
But here's the most important thing we can learn. We can learn that it's never too late to start planning for retirement. Whether you're 25 or 55, there's something you can do today to improve your chances of retiring with a smile on your face. So, what are you waiting for? Let's get planning!