Picture this: you’re at a backyard barbecue, flipping burgers, when your neighbor Dave casually mentions he’s “doing okay.” Dave drives a ten-year-old sedan, wears sandals with socks, and clips coupons. But here’s the kicker—Dave is in the top 1% of net worth in America. That’s the funny thing about the super-rich; they rarely look like the Bond villains we imagine. They look like the guy who brings his own Tupperware to the potluck.
So, what’s the magic number?
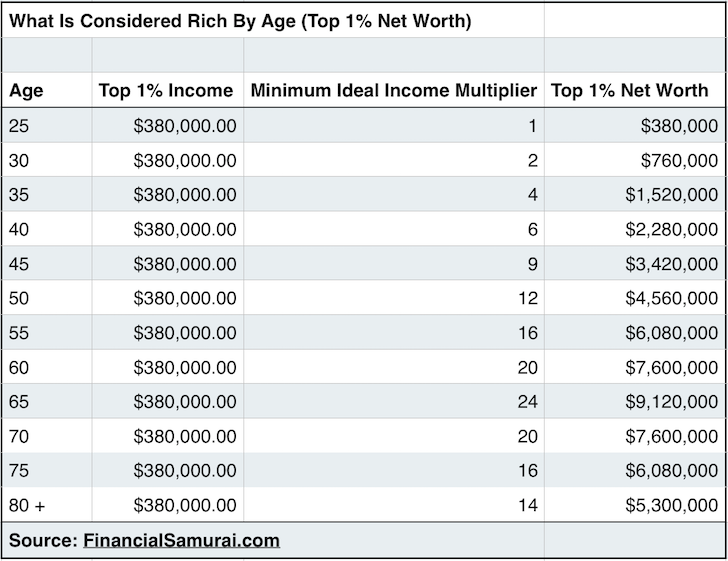
We’re talking about net worth—everything you own minus everything you owe. For the top 1%, that number hovers around $13.7 million as of recent data. Not $100 million, not a billion. Just under fourteen million bucks. That’s the entrance ticket to the club, and it’s a lot less astronomical than you’d think.
For context, if you found a briefcase with that much cash, you could buy a nice house, a vacation condo, and still have enough left to never check your bank balance again. But you wouldn’t be buying a private island or a spaceship. You’d just be very comfortable.
Must Read
The “Fat Wallet” in the Room
Why should you care about Dave’s balance sheet? Well, for starters, it’s a great reality check. When you scroll through Instagram and see influencers flexing private jets, remember that those folks are probably in the top 0.1%, not the 1%. The 1% is more about stability than flash. They’ve got a diversified portfolio, a paid-off mortgage, and maybe a rental property that throws off cash like a leaky faucet.
Think of it like this: if the top 1% were a pizza, it wouldn’t be loaded with gold leaf. It’d be a solid, thick-crust pepperoni with extra cheese. You’d eat it every night without worry, but you’d still get bored of it after a week.
The Journey, Not the Destination (But the Number Helps)
Here’s the warm and fuzzy part—most people in the top 1% didn’t inherit it all. Many are small business owners, doctors, engineers, or even school principals who saved aggressively for forty years. They didn’t hit a lottery; they hit a rhythm of paying themselves first and living below their means.
Take Sarah, a middle school teacher I once read about. She’s worth $8 million now because she bought index funds every single month since 1985 and drove her Honda Civic until the wheels fell off. She’s not rich because she’s a genius; she’s rich because she let time do the heavy lifting. That’s a story you can take to the bank—literally.
Why This Number Should Make You Smile
Here’s the real reason to care: the gap between you and the top 1% isn’t as wide as you think. The median net worth for a 65-year-old retiree is around $400,000. To get to $13.7 million, you’d need to save about $1,000 a month for 45 years at a 7% return. That’s a lot, sure, but it’s not impossible. It’s like running a marathon—you don’t sprint; you just keep jogging and don’t quit.
 Net Worth Benchmarks To Ensure Proper Growth Over Time
Also, knowing the number helps you put your own finances in perspective. If you’re sitting on $150,000, you’re already in the top 10% of households globally. When you compare yourself to Dave, you might feel small. But when you compare yourself to the 7 billion other humans on Earth, you’re basically royalty in flip-flops.
The Secret Sauce (It’s Not What You Think)
The biggest shock? The 1% isn’t obsessed with spending. They’re obsessed with owning—stocks, businesses, real estate. They don’t buy the $80,000 car; they buy the $30,000 car and invest the difference. That’s the quiet magic. It’s like having a magic money tree that you keep watering while everyone else is cutting it down for firewood.
So, next time you’re at a barbecue and someone mentions net worth, don’t roll your eyes. Instead, ask Dave about his index funds. He might just teach you how to grow your own backyard money tree. And hey, if you start today, maybe in 30 years you’ll be the neighbor in sandals with socks, smiling at your spreadsheets.
And One Last Thing
Don’t chase the number for the sake of the number. Chase the peace of mind that comes with it. The top 1% doesn’t sleep better because of their yacht fund; they sleep better because they have a safety net thick enough to catch a clumsy elephant. You don’t need $13.7 million for that. You just need a plan, a little patience, and the stubbornness to ignore the shiny stuff.
So go on, save a little extra this month. Smile at your budget. And remember—Dave’s net worth is just a number, but your financial freedom is a story you get to write. Make it a good one.