Ever played that game where you try to guess your friend's net worth? You know, the one where you shout out numbers like you're at an auction, and the person with the closest guess wins? Well, today we're going to talk about something similar, but with a twist. We're diving into the world of net worth and its liquid cousin. So, grab a cup of coffee, get comfy, and let's chat about money, money, money!
So, What's Net Worth Anyway?
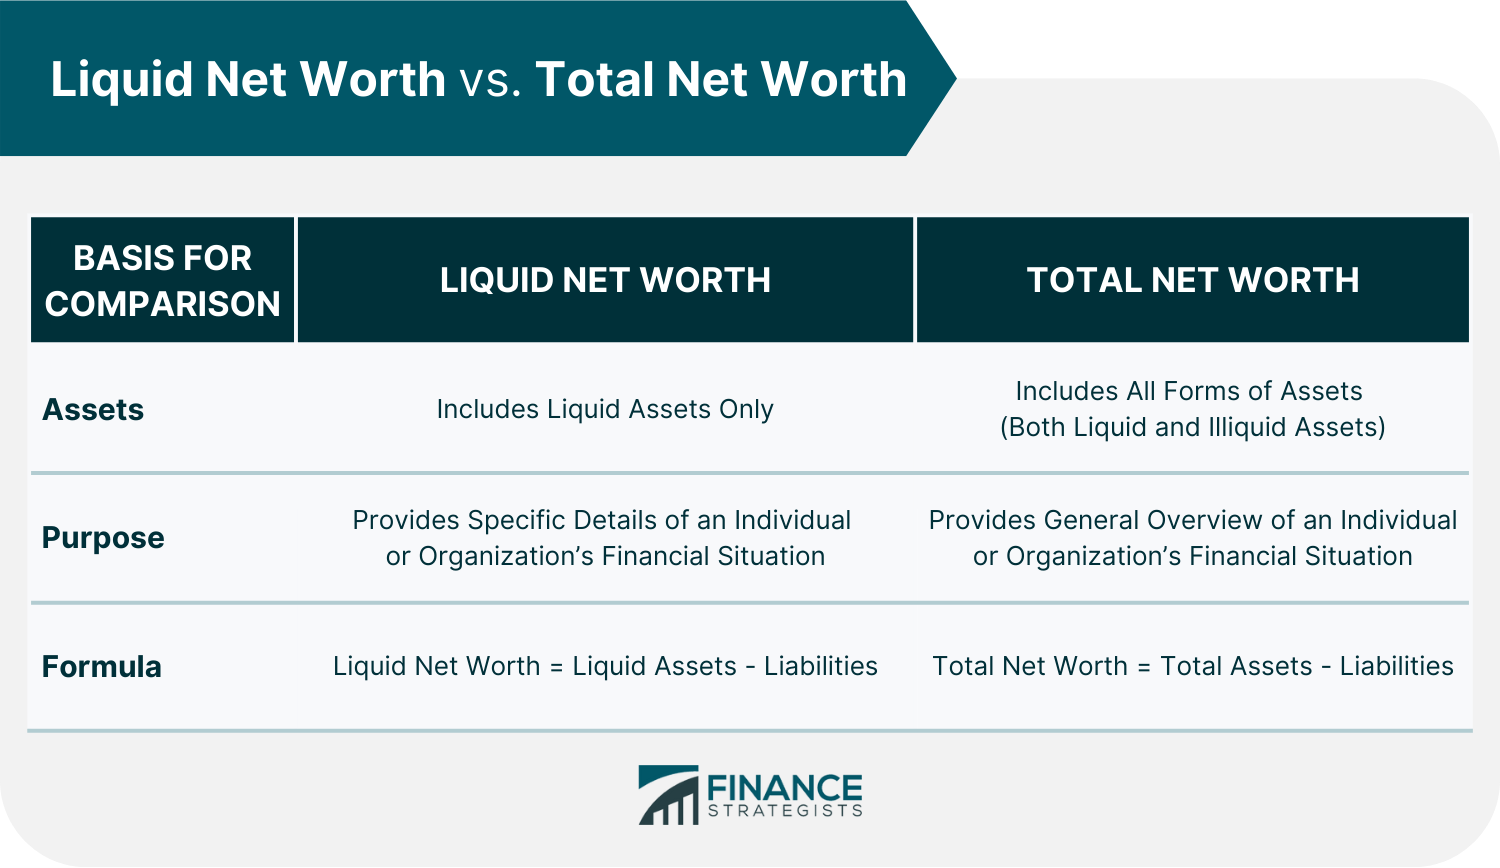
Imagine you're at a buffet. You've got a plate full of food, but you can't eat it all at once, right? Some dishes you can dig into immediately, like those yummy rolls. Others, like the fancy dessert, you'll have to wait for. Your net worth is like that buffet. It's the total value of all your assets - that's everything you own, from your house to your car, your savings, and even that painting your grandma gave you.
Now, here's where it gets interesting. Your net worth also subtracts all your liabilities - that's everything you owe, like your mortgage, car loan, or that shopping spree you went on last week. So, if you've got a $300,000 house and $200,000 in your bank account, but you owe $250,000 on your house and have $50,000 in credit card debt, your net worth is... drumroll please... negative $50,000. Ouch!
Must Read
Now, Meet Liquid Net Worth
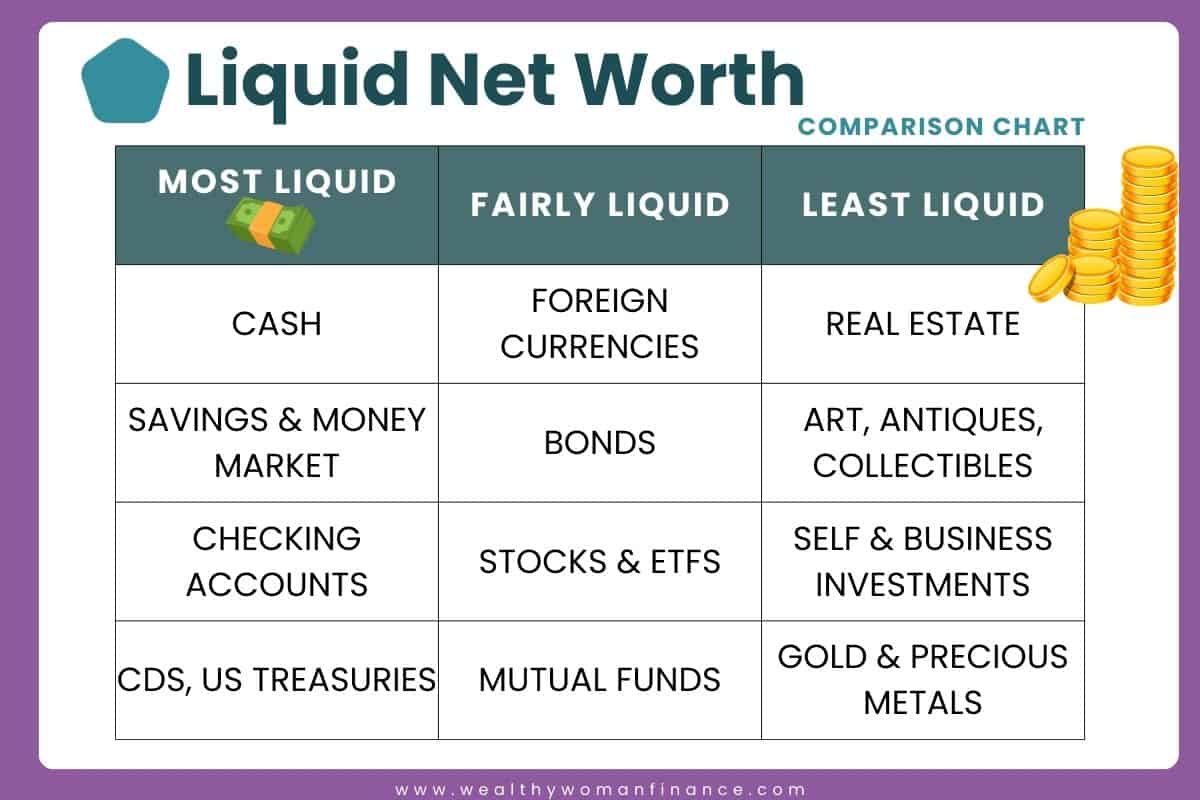
Remember those rolls from the buffet? They're liquid, right? You can eat them right away. Liquid net worth is like that. It's the part of your net worth that you can turn into cash quickly, without losing value. Think of it as your financial emergency fund. It's the money in your checking and savings accounts, your stocks that are easy to sell, and even that jar of coins under your bed (no judgment, we all have one!).
Let's say you've got a net worth of $500,000, but $400,000 of that is tied up in your house. Your liquid net worth might only be $100,000. That's still a nice chunk of change, but it's a lot less than your total net worth. Why does this matter? Well, let me tell you a story.
When Life Throws a Curveball
Meet Sarah. Sarah's got a great job, a beautiful home, and a net worth of $800,000. She's feeling pretty good about life. Then, one day, her company goes under, and she's out of a job. Her husband's salary is enough to cover their bills, but they've got no savings. Sarah's net worth is still $800,000, but none of it is liquid. She can't sell her house or her car to pay for groceries. She's stuck. Now, meet Tom.
Tom's in a similar situation. He's got a net worth of $600,000, but $200,000 of that is in a savings account. When he loses his job, he's got a safety net. He can pay his bills, look for a new job, and even take some time to retrain if he needs to. Tom's liquid net worth saved his bacon.
 What Are Non Liquid Assets at Carl Moran blog
Why Should You Care?
So, why should you care about liquid net worth? Because life happens. Cars break down, jobs get lost, and medical emergencies pop up. Having a healthy liquid net worth means you're ready for whatever comes your way. It's your financial safety net, your rainy day fund, your 'I don't want to sell my grandma's painting' fund.
Think of it like this: Your net worth is your financial dream. It's the big, beautiful house, the fancy car, the retirement you've always wanted. Your liquid net worth is the money you've set aside to make that dream a reality. It's the down payment on your house, the car you can actually afford, the retirement fund that's growing every day.
How Much Liquid Net Worth Do You Need?
So, how much liquid net worth should you have? Well, that depends. A good rule of thumb is to have 3-6 months' worth of living expenses saved up. That means if you spend $3,000 a month, you should have $9,000 to $18,000 in liquid assets. But remember, that's just a starting point. If you're self-employed, have a family to support, or live in an area with a high cost of living, you might need more.
Here's a little challenge for you. Next time you sit down to pay your bills, take a moment to calculate your liquid net worth. It's easy - just add up all the money you've got in checking and savings accounts, plus any other assets you can sell quickly. Then, divide that number by your monthly living expenses. That's your liquid net worth ratio. If it's not where you want it to be, don't worry. Every little bit you save counts. You're on your way to building your financial dream, one roll at a time!