Last Tuesday, I found myself staring at my banking app like it was a Magic 8 Ball. I shook my phone, squinted at the balance, and asked, “Will I ever be rich?” The app, of course, stayed silent. But my credit card statement from the weekend gave me a pretty clear, sarcastic answer.
That little panic attack happens more often than I’d like to admit. I’m not broke, but I’m not exactly “building an empire” either. I’m just… treading water, hoping a wave of cash washes ashore. It’s exhausting, and honestly, it’s a terrible strategy.
So, I decided to stop being dramatic and start being smart. This isn’t a lecture from a millionaire; it’s a diary entry from a fellow clueless adult. Let’s figure out this “net worth” thing together, shall we?
Must Read
The Awkward Math of Your Life
Net worth sounds like a term for people in suits who talk about “synergy.” But it’s literally just: What you own minus what you owe. That’s it. No magic, just subtraction.
If you own a $30,000 car but owe $25,000 on it, congrats, your car is a $5,000 paperweight in the equation. Ouch, right? It’s a harsh mirror, but it’s the only one that actually shows you where you stand.
I did the math last week. My “assets” were a laptop, a half-decent couch, and a savings account with $400 in it. My “liabilities” included student loans and a credit card for a “necessary” espresso machine. Let’s just say the final number wasn’t pretty.
Stop Buying Stuff, Start Buying Freedom
Here’s the part where I sound like your grandma, but she was onto something. That $8 iced coffee? It’s not the enemy. The enemy is the drip-drip-drip of small stuff that adds up to “rent money” every month. I’m not saying live like a monk, but ask yourself: does this purchase bring me closer to not working? Usually, no.
Every dollar you spend is a tiny worker you’re firing from your future payroll. That’s a weird visual, but stick with me. Your money should be working for you, not flying out of your wallet for another pair of sneakers you’ll wear twice.
I’ve started a game with myself: “Do I want this, or do I want the idea of having money?” That’s stopped me from buying three candles and a weird gadget this month.
The Boring Superpower: An Emergency Fund
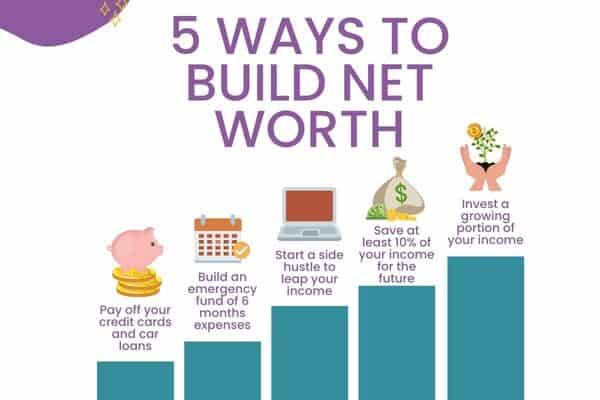
I used to think an emergency fund was for people who were expecting disasters. Then my car needed a new alternator, and my wallet wept. An emergency fund is not a suggestion; it’s the bodyguard for your net worth. Without it, you’re one flat tire away from credit card debt.
Start tiny. Seriously. Twenty dollars a week is a start. It’s not about the amount; it’s about breaking the cycle of “payday, payday, broke.” That buffer is what keeps you from borrowing from your future self at 20% interest.
Think of it as insurance against your own life. You’ll sleep better knowing a mishap isn’t a financial death sentence. That peace of mind is worth more than the cash itself.
 Net Worth – Here’s Everything You Need To Know - How to Money
Make Your Money Grow a Backbone
Savings accounts are for people who plan to buy a couch in a year. For building wealth, you need to get a little more adventurous. Index funds are the unsexy, reliable workhorse of the investing world. They’re not exciting, but they’ve historically gone up over time, unlike my disastrous attempts at day-trading.
If you’re like me, the word “investing” makes you think of Wolf of Wall Street. In reality, it’s just buying a tiny piece of the whole market. You’re betting that people will still buy stuff in 20 years. Seems like a safe bet, right? Even if you only have $50, throw it in. Your future self will high-five you for starting earlier.
The hardest part is ignoring the shiny crypto coins and “get rich quick” schemes. Those are just lottery tickets with extra steps. Slow and steady might be boring, but boring wins the race.
Raise Your Income, Not Just Your Coffee Budget
You can’t save your way to a million dollars. Unless you make like a million a year, but that’s a different problem. The other side of the net worth equation is making more money. Ask for that raise. Hustle on the side if you want, but make it count. Driving for a rideshare service burns out your car and your soul.
Instead, think about skills. Can you learn basic web design? Copywriting? Project management? Every skill you add is a raise you give yourself. It’s a cheat code, but it’s legal.
I started doing small freelance writing gigs. It’s not a fortune, but it’s an extra $500 a month that goes straight into my index fund. That’s $500 your boring, paycheque-to-paycheque self didn’t have.
The Final Humbling Truth
Look, I’m not wealthy. I still have a moment of anxiety every time my bank app refreshes. But now I have a plan, and that’s the difference. It’s not about being rich overnight; it’s about being less broke every quarter. That’s a goal I can actually stick to.
So, my modest proposal: subtract what you owe from what you own, stop bleeding cash on nonsense, and park your money in boring stuff. Yes, it’s slow. Yes, it’s dull. But it’s your dull. And that’s oddly satisfying.
Now, if you’ll excuse me, I’m going to go check my app again. Not because I have to, but because I’m curious. And that, my friend, is the real magic of it.