
Okay, let’s talk about that slightly terrifying phrase: net worth. It sounds like something a billionaire in a slick suit mutters while staring at a yacht, right? But here’s the secret: it’s just a fancy way of saying “what you own minus what you owe.” Think of it as a financial selfie — and honestly, it’s way less painful than a root canal, I promise.
First things first, grab a drink (coffee, tea, or something stronger if your credit card bill is staring at you) and a piece of paper. Or better yet, open a spreadsheet on your laptop. We’re going on a treasure hunt, and the treasure is your actual numbers. No judgment here — we’re just doing some basic math, not solving a NASA equation.
Step One: Add Up Your Assets (The Fun Stuff)
Your assets are all the things that put money in your pocket — or at least, things you could sell for cash. Start with the obvious: your checking and savings accounts. Yep, even that $37.50 that’s been sitting there since last March counts.
Must Read
Now, add your retirement accounts like a 401(k) or IRA. Don’t get scared by the stock market’s daily drama; just use the current balance. Also, throw in any investment accounts, like a brokerage or crypto wallet (we won’t tell anyone about your Dogecoin experiment).
Next up: your car, your house, and any shiny toys like a boat or a vintage guitar. For your car, use a rough estimate of what it’d sell for today, not what you paid for it. And for your house, be honest — don’t use the Zestimate from your overly optimistic neighbor. Use a realistic number, like from a recent appraisal or a solid realtor’s guess.
Finally, add other valuables: jewelry, art, or that rare collection of beanie babies that’s definitely going to fund your retirement (spoiler alert: it won’t, but it’s fun to dream). Just total it all up — this is your “good stuff” total.
Step Two: Tally Up Your Liabilities (The Ouch Column)
Now for the part that feels like stepping on a Lego in the dark. Your liabilities are everything you owe. Start with credit card balances — yes, all of them, even the one you use for “emergencies” that turned into “sushi nights.”
Add your mortgage balance (if you own a home), your car loan, student loans, personal loans, and any money you borrowed from your mom that she “totally forgot about.” Actually, that last one is on the honor system — but let’s include it for full honesty. Write it all down, and don’t round down to make yourself feel better. This is the “ugh” total.
The Magical Math (Don’t Worry, It’s Simple)
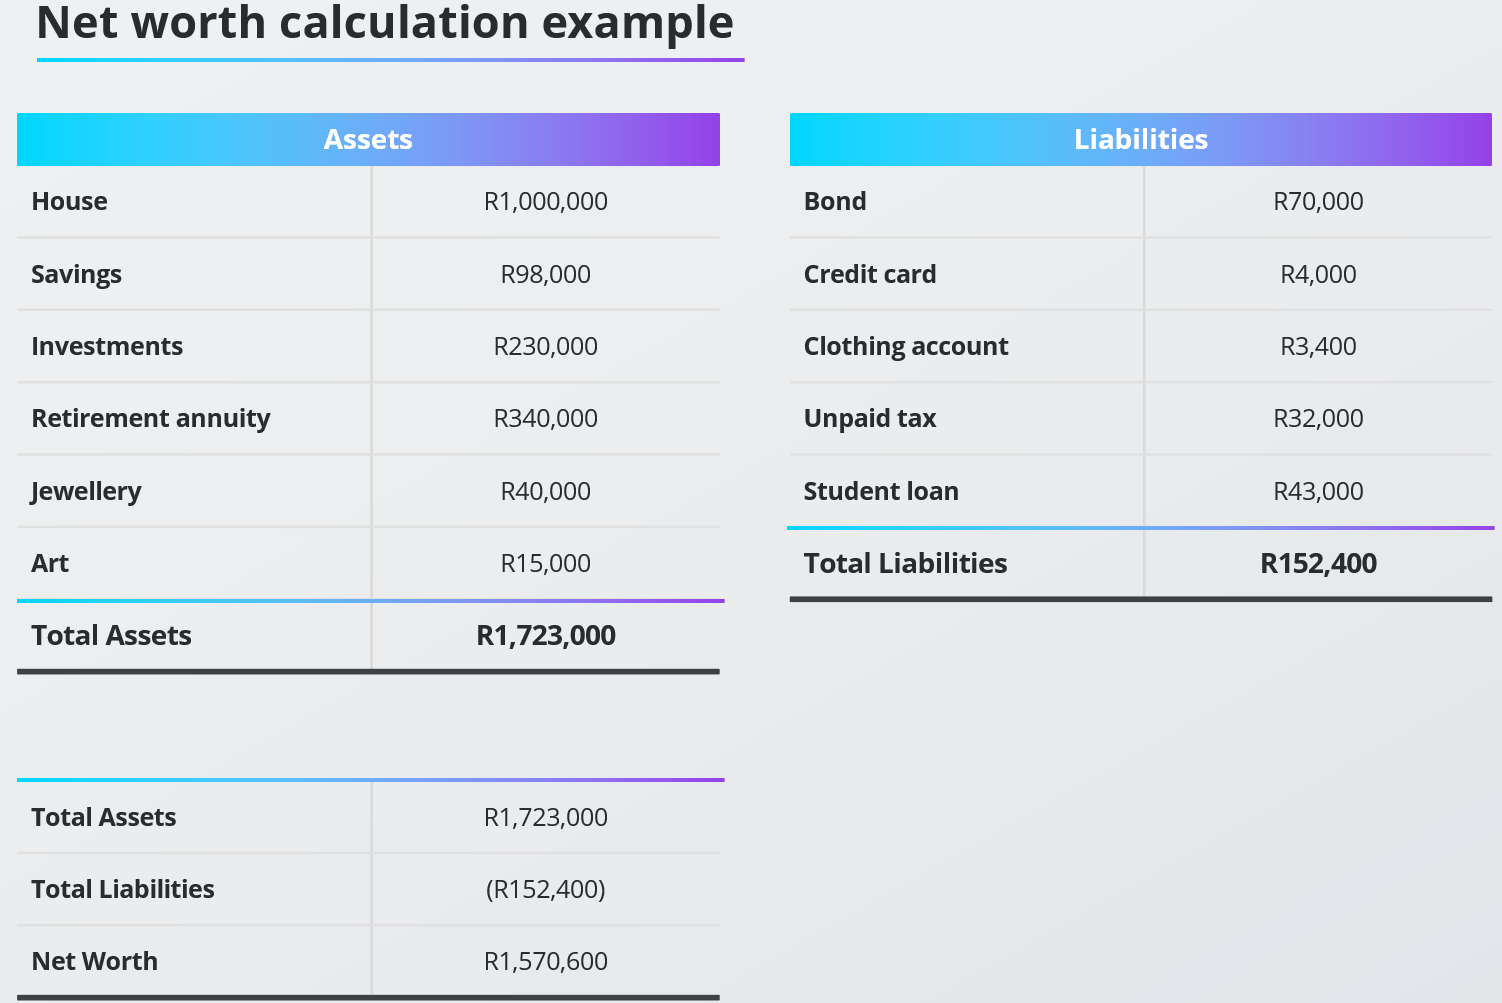
Here’s the big reveal: Net Worth = Assets − Liabilities. That’s it! No calculus, no algebra, just subtraction you learned in third grade. Take your “good stuff” total, subtract your “ugh” total, and the number that pops out is your net worth.
If the number is positive, congratulations — you’re officially worth more than a broken toaster! If it’s negative, don’t panic. Seriously, put down the panic button. A negative net worth is incredibly common, especially if you’re young or just finished school. That’s not a failure; it’s just a starting line.
 What is my net worth and how does it impact my retirement
Let’s do a quick example, because I’m feeling generous. Say you have $5,000 in savings, a car worth $12,000, and a sweet comic book collection valued at $1,000. That’s $18,000 in assets. Now, you owe $10,000 on a car loan and $3,000 on credit cards — that’s $13,000 in liabilities. Subtract them: $18,000 - $13,000 = $5,000 net worth. See? You’re not broke; you’re just a work in progress with four wheels.
Why Bother? (Besides Nerd Cred)
Knowing your net worth gives you a clear, unblurry snapshot of your financial health. It’s like stepping on a scale at the doctor’s office — uncomfortable, sure, but way better than guessing and being shocked later. You can track it over time to see if you’re moving in the right direction. If it goes up, do a happy dance. If it goes down, you’ll know exactly where to tighten the belt.
Plus, it’s a brilliant way to set goals. Want to hit $10,000? $50,000? A million? (A million is a great goal, but let’s start with “pay off my Visa.”) By calculating every few months, you’ll see your progress in real-time, like watching grass grow but with more exciting numbers.
And hey, you can also use this number to impress a date. “Oh, you like hiking? Let me tell you about my net worth trajectory.” Works every time. (Okay, maybe not, but at least you’ll be financially literate and single.)
Final Thoughts, Minus the Shoulder Cramps
Finding your net worth isn’t about judging yourself; it’s about empowering yourself. It’s a flashlight in a dark closet — you might find some dust bunnies, but you’ll also find your favorite jacket. And remember, this number is just a moment in time. It changes every single day as you pay bills, earn money, and make (or avoid) silly purchases.
So, grab that calculator, take a deep breath, and do the math. You’ll probably surprise yourself — maybe in a good way, maybe in a “time to cancel my streaming service” way. Either way, you’ll walk away knowing more than most people, and that’s priceless (literally, because it didn’t cost you anything).
Now go on, you beautiful, net-worth-calculating genius. Whether your number is big, small, or still finding its feet, you’re making progress just by looking. And that’s worth more than any dollar amount. Smile — you just took a huge, brave step toward owning your financial story.