You know that moment when you’re scrolling through social media at 2 AM and see an influencer casually flexing their “morning routine” in a house that costs more than your entire street? We’ve all been there. But here’s the kicker: figuring out your own net worth isn’t about keeping up with the Joneses—it’s about giving you a financial report card that actually makes sense.
Think of it as the ultimate self-care check-in, but instead of a face mask, you’re using a calculator. It’s the single most powerful number you can know about your finances, and trust me, it’s a lot less scary than it sounds.
The “What Even Is Net Worth?” Moment
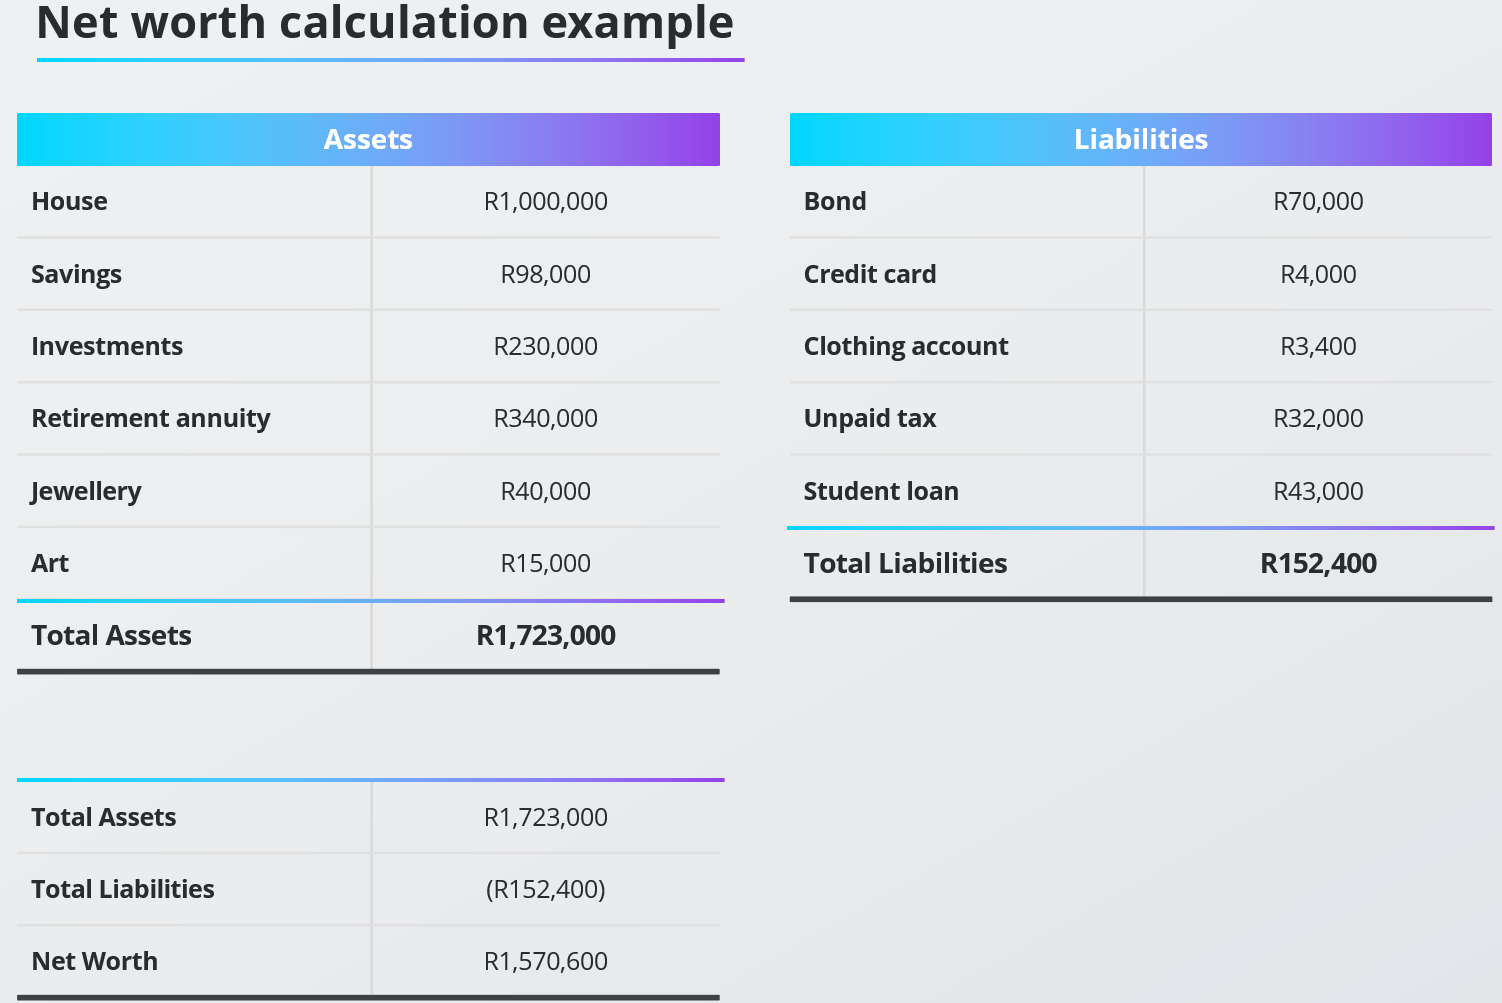
Simply put, your net worth is what you own minus what you owe. That’s it. No cryptic formulas, no Wall Street jargon—just a simple subtraction problem.
Must Read
Imagine your financial life as a tiny, very personal island. Everything on that island that has value—your cash, your car, your investments, your vintage sneaker collection—is an asset. Everything that drags you down—credit card balances, student loans, that buy-now-pay-later sofa—is a liability. Your net worth is the size of the island above sea level.
It’s not a measure of your income, either. You can earn $200k a year and have a net worth of zero if you spend it all on avocado toast and rent. Conversely, a school teacher who buys a modest home and saves diligently can be a quiet millionaire. It’s about accumulation, not salary.
The Treasure Hunt: Listing Your Assets
Grab a notebook, a spreadsheet, or even the notes app on your phone—whatever feels less like a chore. We’re going on a treasure hunt, and you’re the map.
First, list everything that’s worth money. Start with the obvious: checking and savings account balances. Then, move to investments—your 401(k), IRA, brokerage accounts, and that crypto you bought during the meme stock phase (yes, even that counts, though maybe whisper it).
Don’t forget your tangible assets. What’s your car worth today? (Check Kelley Blue Book, not your sentimental attachment). What about your home’s current market value? Even that vintage guitar or designer handbag has a resale price. Be honest with yourself—that IKEA bookshelf from 2015 might fetch you $20 at a garage sale, but it’s still an asset, however small.
The Reality Check: Adding Up Your Liabilities
Now for the less glamorous part—the “drain” side of the equation. This is where you need to channel your inner detective and get brutally honest.
List your mortgage balance (the remaining principal, not your monthly payment), car loans, student loans, personal loans, and any medical debt. Then, the sneaky ones: credit card balances. If you pay it off monthly, you’re golden. If you carry a balance, that’s a liability that’s actively working against you.
Don’t stress about your monthly bills like utilities or Netflix—those are expenses, not liabilities. Liabilities are outstanding balances you’re paying back over time. This is about what you owe right now, not what you spend in a month.
 Net Worth – Here’s Everything You Need To Know - How to Money
Pro tip: Make a cup of tea for this step. It can feel like a cold shower, but it’s a necessary one. Clarity is a form of power.
The Final Calculation & The “Dang” Factor
Time for the big reveal. Total your assets. Total your liabilities. Subtract the liabilities from the assets. Boom. That’s your number.
If it’s positive, congrats! You’re officially in the black. If it’s negative, you’re not alone—millions of people, especially younger folks with student debt, are there too. The beauty is that net worth is a snapshot, not a life sentence. It’s a starting line, not a finish line.
Here’s a fun fact: The average American’s net worth is around $192,000, but the median is closer to $121,000. The difference? Billionaires skew the average. So, don’t compare yourself to a tech mogul; compare yourself to last year’s you.
The “So What Now?” Plan
Tracking this number once a year is like having an annual physical. It’s preventive care. If your liabilities outweigh your assets, don’t panic—make a battle plan.
Start with the highest-interest debt first (credit cards, always). Automate a small transfer to a savings account each month, even if it’s just $50. Watch your assets grow like a slow-blooming plant. It’s not exciting, but it’s effective.
And remember, your net worth doesn’t define your worth as a human. You are not your balance sheet. You’re a person with a rich life—full of memories, relationships, and experiences—which are all assets that never show up on a financial statement.
A Little Reflection for the Road
When you go to bed tonight, don’t think about the number on a screen. Think about what that number represents: your choices, your habits, and your future potential.
Knowing your net worth is like checking the weather before a hike. It doesn’t stop the rain, but it helps you grab a jacket. So, check the forecast, pack your gear, and enjoy the walk. The goal isn’t to be rich in numbers; it’s to be rich in peace of mind. And that, my friend, is the only net worth that truly matters at the end of the day.