Last Tuesday, I had a minor meltdown in the cereal aisle. I couldn’t decide between the $4 organic granola and the $2 store-brand oats, so I did what any sane person does: I took out my phone to check my bank account.
And there it was, staring back at me. A number that made the granola feel like a reckless, luxury purchase. It got me thinking—is this number, the one in my checking account, actually my net worth?
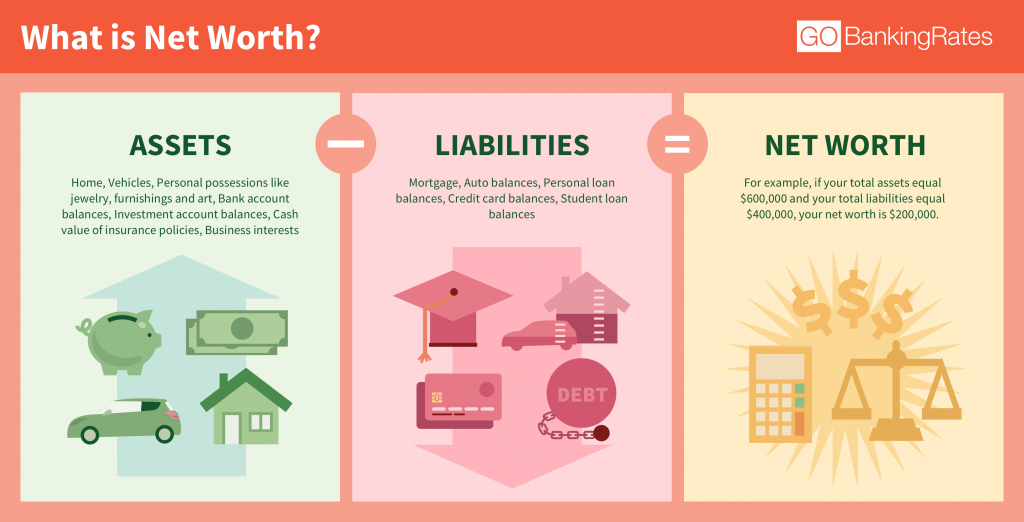
Obviously, it isn’t. Your net worth is the grand total of everything you own minus everything you owe. But figuring that out feels a lot like trying to solve a puzzle where half the pieces are in another room, and the other half are on fire.
Must Read
We tend to obsess over the wrong numbers, like our monthly salary. But your paycheck is just a snapshot; your net worth is the whole photo album, including the awkward teenage years.
The Great Inventory (or, What You Actually Own)
First, we have to talk about your assets. This is the stuff that puts money in your pocket, or at least, could if you sold it tomorrow. I’m not just talking about your checking account and that 401(k) you forgot the password to.
Think about your car—yes, that sad little hatchback with the sticky gear shift. It’s worth something, even if it smells faintly of old gym socks. Also, include the cash value of your investments, that old comic book collection, and, you know, your 401(k) once you finally recover that password.
You’d be surprised how quickly these little things add up. That’s the fun part—it’s like finding a $20 bill in an old coat pocket, but with more spreadsheets involved. (Or, in my case, a lot more spreadsheets.)
The Debt Monster (What You Owe)
Now for the buzzkill: your liabilities. This is the money you owe, and it’s crucial that you’re brutally honest here. Hiding your credit card balance from yourself is only going to make the next step more terrifying.
List out your mortgage, your student loans, that personal loan from your dad (he hasn’t forgotten, trust me), and any car loan. Include the little stuff too, like the $400 you owe on your store credit card from that "emergency" couch purchase. Everything counts—especially the stuff you’re trying to ignore.
I once avoided looking at my student loan balance for six months, thinking it would magically decrease. Spoiler alert: it did not. The interest just sat there, munching on my soul like a passive-aggressive hamster.
 What is my net worth and how does it impact my retirement
The Magic Math (and Why It’s Okay)
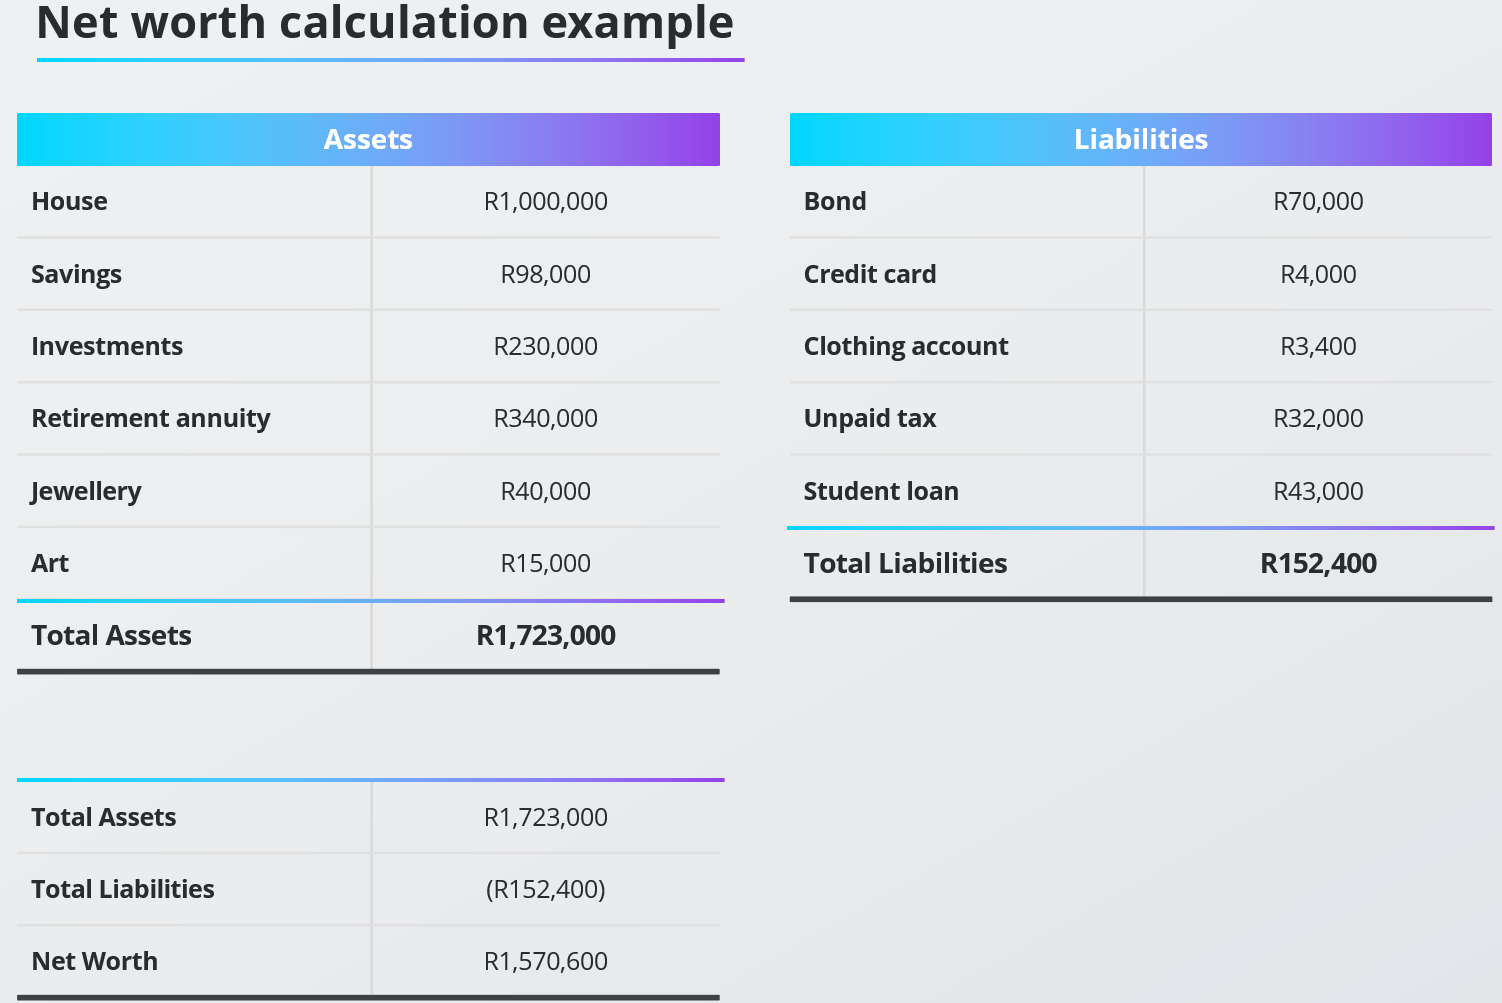
Here’s the part that actually answers the title question: Net Worth = Total Assets – Total Liabilities. That’s it. Take everything you own, subtract everything you owe, and you have your number.
If the number is negative, you are not alone. In fact, most people in their twenties and thirties are walking around with a negative net worth, thanks to student loans and mortgages. It’s a club with very cool t-shirts, but zero dividends.
If the number is positive, congratulations! You are officially richer than a toddler who owns a piggy bank with three quarters in it. But don’t start buying golden toilets just yet.
The irony is that knowing this number doesn’t just tell you about your money; it tells you about your decisions. When I finally did the math, I realized my net worth was basically the cost of a good used bicycle. (Spoiler: I don’t own a bike.)
But here’s the secret—once you know it, you can change it. You can’t fix a problem you refuse to measure. That’s like trying to lose weight by never stepping on a scale.
So, how do you know your net worth? You sit down, you get slightly depressed, you laugh at your own financial chaos, and then you write it down. It’s a drill, not a diagnosis.
And guess what? That $4 granola? I bought it. Because after calculating my net worth, I realized that while I might not be rich, I’m not broke enough to let a little muesli ruin my day. That feeling, right there, is worth more than any number.