
You know that moment when a friend casually drops that they’re “building their net worth,” and you nod along while silently calculating if you have enough in your checking account to cover this week’s oat milk lattes? Yeah, we’ve all been there. The term sounds like something reserved for Wall Street wolves in tailored suits, not for people who recycle takeout containers. But here’s the secret: net worth isn’t a mysterious number whispered by financial gurus—it’s just a fancy way of saying what you own minus what you owe. That’s it.
Think of it like your financial Instagram profile. Your “highlight reel” includes your savings, investments, and that vintage bike you restored. Your “burner account” is your credit card debt, student loans, and that “buy now, pay later” splurge on noise-cancelling headphones. Your net worth is the algorithm’s verdict: the honest, unfiltered total of your fiscal life. It’s not a score of your worth as a human—it’s just a snapshot of your balance sheet at any given moment.
The “Assets vs. Liabilities” Dance-Off
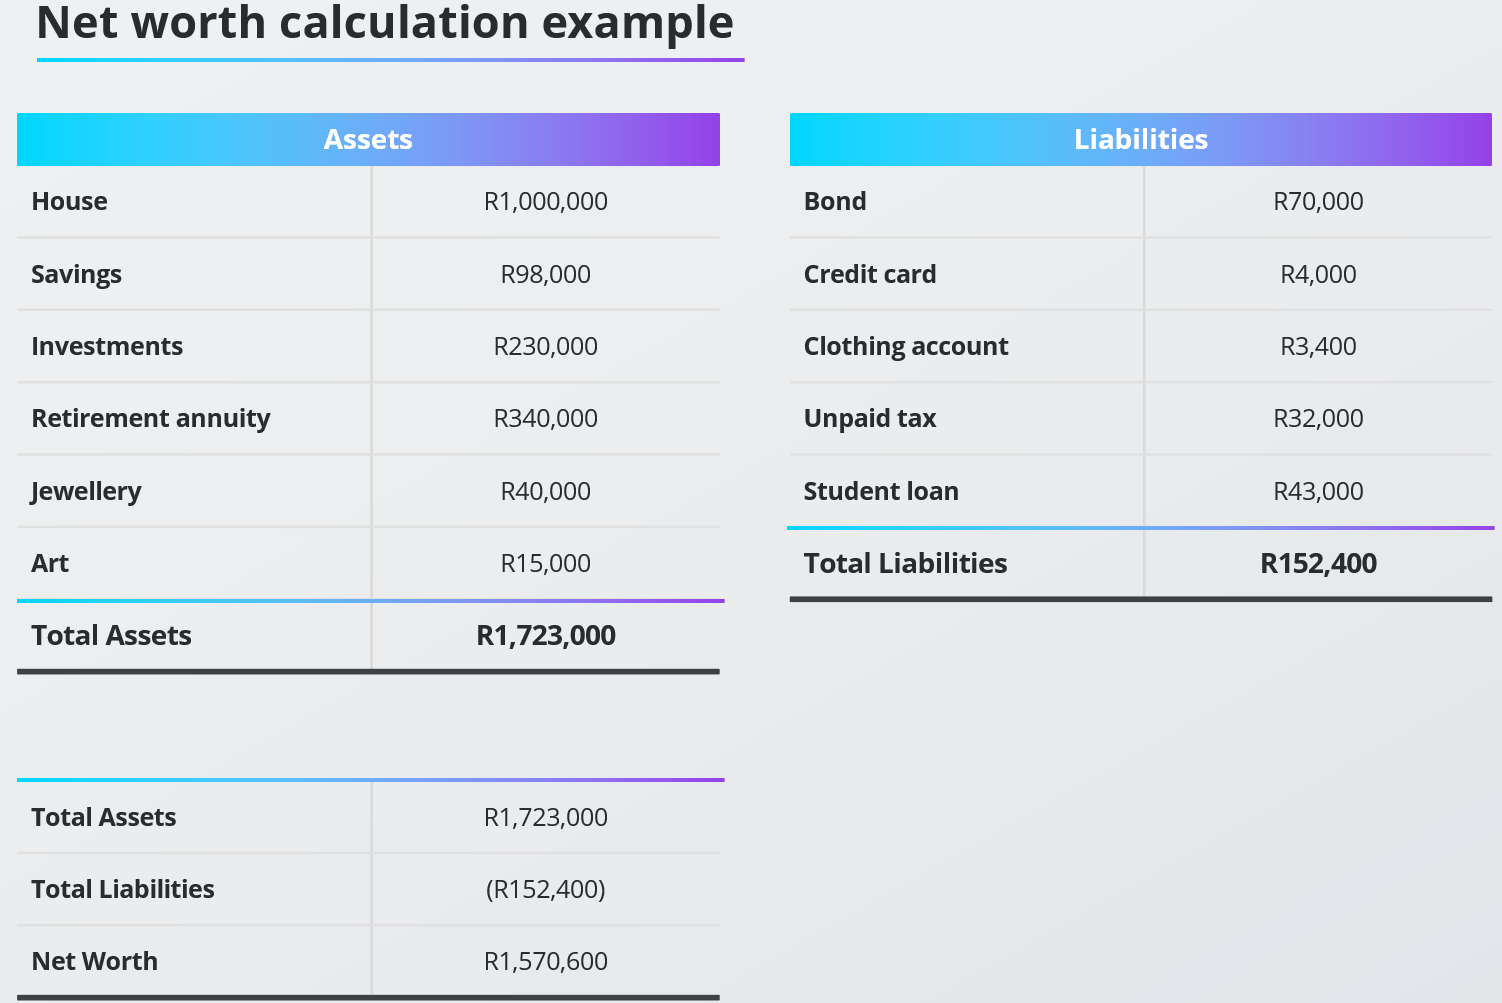
To get a net worth, you first have to play a game of mental Tetris. Assets are things that put money in your pocket: cash, stocks, bonds, real estate, or even that vintage comic book collection that’s suddenly worth a mortgage payment. Liabilities are things that take money out: car loans, credit card balances, or that gym membership you keep forgetting to cancel. The formula is brutally simple: Assets minus Liabilities equals your net worth.
Must Read
Let’s get practical for a second. Imagine you have $5,000 in savings, a car worth $8,000 (you hope), and a $2,000 emergency fund. That’s $15,000 in assets. Now, you owe $12,000 on the car and $3,000 on a credit card. That’s $15,000 in liabilities. Your net worth? A very honest zero. But here’s the plot twist—that’s not a bad place to start. Zero is the new black. It means you’re breaking even in a world where many people are deep in the red.
The Art of Small Wins (and Avoidable Fails)
How do you actually grow that number? You don’t need a tech IPO or a lottery ticket. You need a series of unsexy, repeatable moves. Start by tracking your spending for a week—yes, including the $4.50 coffee. You’ll likely discover that your “small treats” add up to a “big giant ouch” at month’s end. Redirect just $100 a month from impulse buys into a high-yield savings account or a simple index fund. That’s $1,200 a year, and with compounding interest, it’s like planting a money tree that grows while you sleep.
Another move? Attack high-interest debt like it’s the final boss in a video game. Credit card interest at 24% is an anchor dragging your net worth down faster than you can say “cashback rewards.” Pay that off before you even think about fancy investment portfolios. Fun fact: the average American household carries over $8,000 in credit card debt. If you’re one of them, clearing that balance can boost your net worth by thousands overnight—without changing your salary.
Why Your Net Worth Is (Not) Your Identity
Here’s the cultural irony: we live in a world where net worth is often used as a proxy for human value, yet the richest people in history—think of Warren Buffett—still eat at McDonald’s and drive old cars. Meanwhile, plenty of broke influencers rent private jets for content. The number on your balance sheet has about as much to do with your character as your shoe size. It’s a metric for decisions, not a badge of honor.
 What is my net worth and how does it impact my retirement
But that doesn’t mean it’s useless. Tracking your net worth gives you a reality check. It forces you to see the gap between your fantasy self (who invests in crypto and owns a cabin in the woods) and your actual self (who pays for subscriptions you’ve never used). When you see the number in black and white, you make better choices. It’s like stepping on a scale after the holidays—uncomfortable, but motivating.
Fun Facts to Lighten the Mood
Did you know that the term “net worth” dates back to the 15th century, when merchants used it to settle debts in Genoa? Or that the average net worth for a 30-year-old in the U.S. is around $35,000, but the median is closer to $9,000? That means half of all 30-year-olds have less than nine grand to their name. You’re not behind; you’re just human. Also, a 2023 survey found that 58% of Americans couldn’t cover a $1,000 emergency with savings. So if you have a $1,000 buffer, you’re already above average. Pop the champagne (but only if it’s on sale).
The real trick to building net worth isn’t some secret formula—it’s automation. Set up a transfer to your savings the day you get paid, before you can spend it. Contribute to your 401(k) even if it’s just 1% (your future self will send you a thank-you note). Treat your net worth like a houseplant: water it a little every week, don’t obsess over its daily growth, and cut off the dead leaves (read: subscriptions) ruthlessly.
The Daily Life Reflection
Here’s the truth: getting a net worth isn’t about making yourself miserable with spreadsheets. It’s about reclaiming control. Every time you choose to cook instead of ordering delivery, every time you negotiate your internet bill, every time you pay off a chunk of your loan—you’re not just saving money. You’re shifting the balance in your favor. You’re telling the world, and yourself, that you have a plan. And that’s a feeling money can’t buy, but ironically, it’s the biggest asset you can have.
So tonight, when you’re scrolling your phone, pause for two minutes. Jot down your savings, your debts, your stuff. Do the math. Don’t judge yourself—just observe. Your net worth might be negative, zero, or pleasantly surprising. But the fact that you looked? That’s a net win. And in the quiet act of knowing your number, you’ve already started to change it. That’s the only magic trick you need.