
Imagine your life is a video game, and you just paused it to check your stats. Net worth is that giant, glowing number on your character sheet. It’s the total of everything you own (your loot) minus everything you owe (your debt). And no, it has nothing to do with how cool you look doing it.
Here’s the fun twist: your net worth doesn’t care about your paycheck. You could make six figures and still be broke, or earn a modest salary and be quietly sitting on a goldmine. It’s the ultimate behind-the-scenes score of your financial life.
The “Stuff” Side (Your Assets)
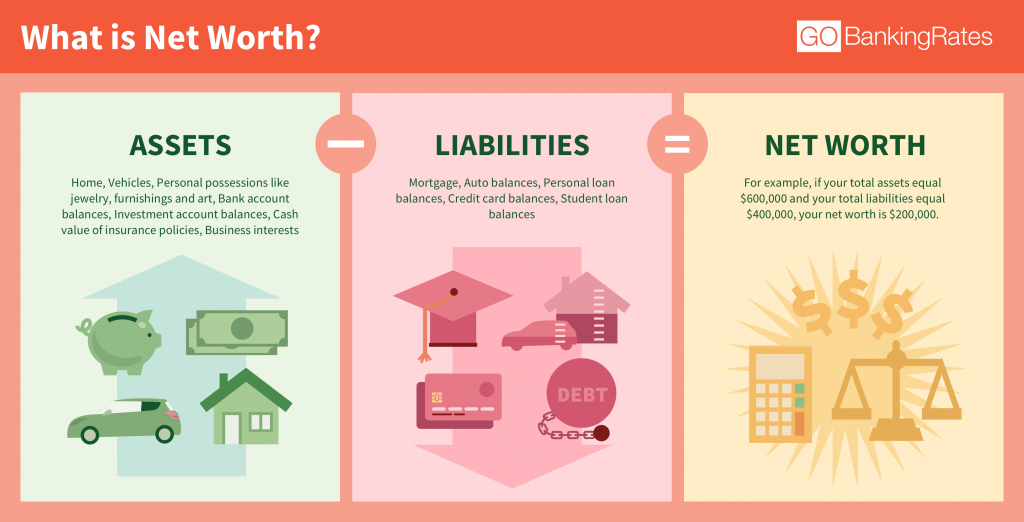
First, let’s raid your inventory. Assets are the things that put money in your pocket or could be sold for cash. That includes your checking account, your retirement funds, and that dusty coin collection from your grandpa.
Must Read
Yes, your beloved Jeep Wrangler counts. But here’s a hilarious reality check: that shiny car drops in value faster than a hot potato the second you drive it off the lot. We still count it, but at its current resale value, not the price you paid with your heart.
Your home, if you own one, is usually your biggest asset. But let’s be real—your house isn’t a piggy bank until you sell it. For now, we’ll use a realistic estimate of what a buyer would hand you today.
The “Oops” Side (Your Liabilities)
Now, hold your breath. Liabilities are everything that takes money out of your pocket. This is your credit card balance, your student loans, and that lingering tab for the pizza you bought three weeks ago.
Your mortgage is the big elephant in the room. Yes, it’s a liability, even though it’s tied to a lovely asset. Think of it this way: for every dollar of house you own, the bank still owns a slice of your morning coffee.
Don’t panic if this list makes you sweat. Seeing your debt on paper is like seeing your face in harsh lighting—it’s shocking, but it’s the first step to looking better.
The Magic Math (It’s Just Subtraction!)
Here’s the punchline: Net Worth = Everything You Own – Everything You Owe. That’s it. No calculus, no quantum physics, just simple subtraction your third-grade teacher would be proud of.
If your assets are $50,000 and your debt is $30,000, you’re sitting pretty at $20,000. If your assets are $10,000 and your debt is $40,000, you’re in the negative zone—don’t worry, you’re not alone, and it’s not a life sentence.
Here’s a quirky fact: even billionaires obsess over this number daily. They just use fancier spreadsheets and better suits to do it.
Why You Should Care (Even If You’re Broke)
Your net worth is like a financial GPS. It doesn’t tell you where you should be, but it tells you exactly where you are right now. You can’t navigate to a treasure island if you don’t know your starting port.
 Clear Results-Driven Strategy for what is your net worth to be in the
It’s also a hilarious judge of progress. Imagine tracking this number every year. One year you’re at -$5,000, the next you’re at $1,000. That’s not just growth; that’s a victory lap on your personal race track.
Plus, it flips your mindset. Instead of asking, “How much did I make?” you start asking, “How much did I keep?” That’s where the real fun begins.
Free Tools & A Dash of Weirdness
You don’t need a financial advisor in a bow tie to figure this out. A simple notebook, a free app, or a basic spreadsheet will do the trick. List your assets, list your debts, and subtract like you mean it.
Weird example time: Did you know your frequent flyer miles don’t count? Neither does your Beanie Baby collection, unless you’ve actually sold one recently. We only count real value, not “eBay dream” value.
And yes, that $20 bill you found in your winter coat last week? That absolutely counts. Every dollar in your bank account, your wallet, and under your mattress is part of the grand total.
The Secret They Don’t Tell You
Your net worth is a number, but it’s not your worth as a human. It doesn’t measure your kindness, your humor, or your ability to make a killer lasagna. It’s just the score of your money game.
But here’s the kicker: watching that number climb is addictive. It’s more satisfying than beating a high-score in Tetris. You’ll start skipping that overpriced latte just to see the little digits wiggle upward.
So, go ahead. Grab your last bank statement and your most recent credit card bill. Spend ten minutes playing accountant. You might be surprised, you might be horrified, but you’ll be curious. And that’s the whole point.
Now, go check your stats, player. The game is way more fun when you know your score.