
Let’s be honest: the only time most of us think about our net worth is when we’re lying awake at 3 a.m., staring at the ceiling, and wondering if that $4.50 cold brew habit is secretly the reason we’ll never own a home. It’s a weird number, right? It’s not your salary, and it’s definitely not the cash in your checking account. It’s basically the financial version of stepping on a scale after Thanksgiving dinner—nobody really wants to see the result, but we all peek anyway.
So, how does your net worth compare to your neighbor’s, your cousin’s, or that guy from high school who now posts photos of his yacht on LinkedIn? The short answer is: probably not as badly as you think, but also maybe worse than you’d like. And that’s okay. Because comparing your net worth to anyone else is like comparing a goldfish to a Great Dane—they’re both pets, but they live very different lives.
The Great Net Worth Illusion
Here’s the dirty little secret about net worth: it’s a snapshot, not a movie. Your friend who just bought a Tesla? His net worth might actually be negative when you factor in the loan. Meanwhile, your Aunt Carol with the 1998 Camry and a paid-off duplex is quietly sitting on a cool half-million. The scoreboard is misleading because it doesn’t show the late fees, the interest rates, or the sheer panic behind the scenes.
Must Read
I remember a guy in my college dorm who drove a BMW. We all assumed he was rolling in it. Turns out, his dad co-signed a lease, and he lived on instant ramen and stolen ketchup packets to make the payments. His net worth was probably minus the cost of four years of therapy. Meanwhile, the quiet kid who walked everywhere had a small online business and a savings account that could buy a small island in Maine. Never judge a book by its car payment.
The Baseline: You’re Not as Broke as You Think
If you’re under 35, your net worth is probably somewhere between “a jar of loose change” and “one emergency dental visit away from bankruptcy.” And that’s normal. The Federal Reserve publishes these dry-as-toast reports, but the gist is: the median net worth for people in their 30s is around $30,000 to $40,000. That sounds like a lot until you realize it includes the value of a used couch, a laptop, and the equity in a car you still owe money on. It’s not exactly trust-fund territory. It’s more like “I can fix my leaky roof without crying” territory.
But here’s the kicker: the average net worth is skewed by billionaires and tech moguls. So if you look at averages, you’ll feel like a broke clown at a millionaire’s ball. Look at medians instead. Median is the “middle” person. If you lined up everyone by net worth, the median person is the one in the middle. That’s your real competition. And that middle person? They’re probably wearing sweatpants and wondering if they should refinance their student loans. You’re fine.
The Stages of Net Worth Grief
First, there’s denial. “My net worth is fine, I just bought a $9 smoothie.” Then, anger. “Why does my sister have a house and I have a storage unit full of IKEA furniture?” Then, bargaining. “If I skip lunch every day for a year, I’ll have an extra $2,000!” Finally, acceptance. “My net worth is what it is, and I still have good hair.” You’ll cycle through these stages every time you log into your retirement app, which is about once a quarter, after a glass of wine.
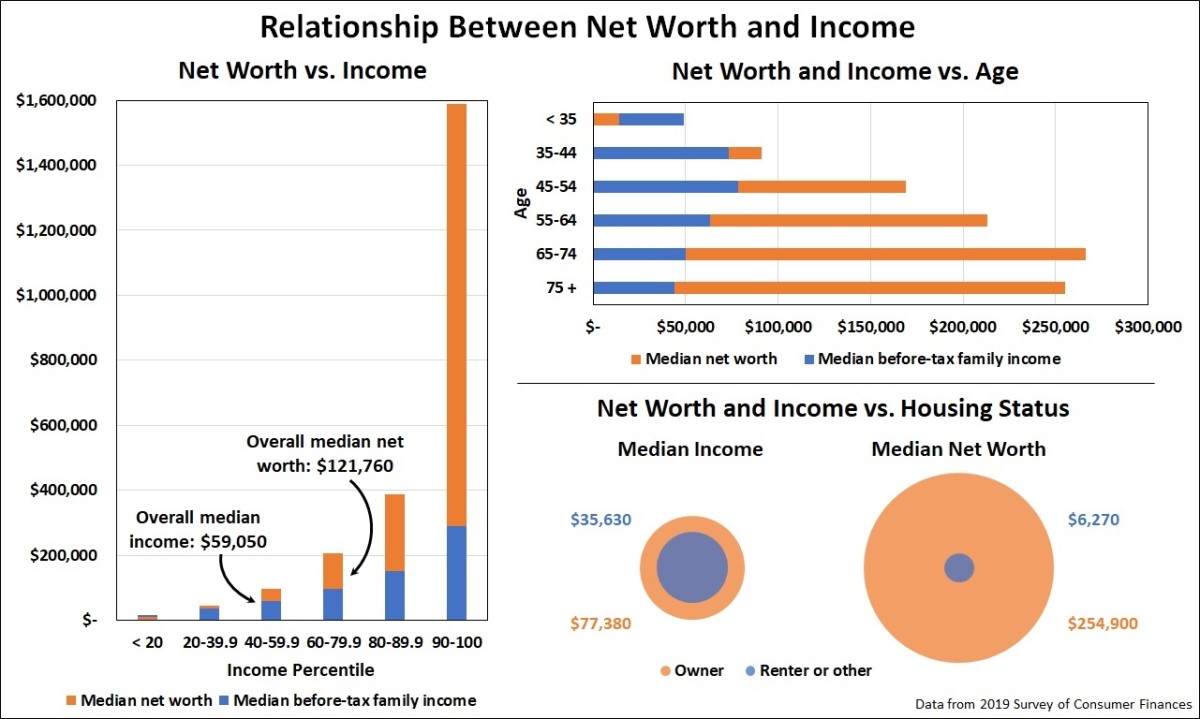 What Is Net Worth and How Do You Measure Up? - HubPages
The truth is, your net worth is a lagging indicator of your life choices, not a judgment of your character. It doesn’t measure your kindness, your humor, or your ability to change a flat tire. It literally just counts your assets (house, car, savings, that Beanie Baby collection you refuse to sell) minus your debts (the mountain of credit card bills from that “minimalist” phase). If you’re in the red, it just means you’re investing in experiences or you got unlucky with a used car. Both are valid.
So, How Do You Actually Stack Up?
Let’s do some quick math, but make it painless. Count up your checking, savings, and that 401(k) you’ve been contributing to for exactly four years. Add the estimated value of your car (even if it smells like old fries). Subtract your credit card balance, student loans, and the $800 you owe your buddy for that concert ticket. That’s your number. If it’s positive, congrats—you’re more stable than a cat on a windowsill. If it’s negative, welcome to the club. About 30% of Americans have a negative net worth, and they still manage to have fun on weekends.
Here’s the punchline: comparing your net worth to others is like comparing your pizza to the photo on the menu. The photo is perfect, but your pizza is hot, and it’s yours. The guy with the Lamborghini might be drowning in depreciation. The couple with the retirement cabin might have bought it in 1998 and never updated the kitchen. Your net worth is just a tool, not a trophy. If you’re saving a little, paying down debt, and not eating cereal for dinner every night, you’re beating about half the population. And that’s a win.
So the next time you see a “How do you compare?” quiz online, take it with a grain of salt—and a side of fries. Your net worth is not your worth. It’s just a number that changes with the seasons, like your mood or your jeans size. As long as you’re moving forward, even in tiny steps, you’re doing better than the guy who compares his net worth every single day. That guy has a net worth of anxiety, and that costs more than any mortgage.