
We’ve all been there—scrolling through a glossy real estate app, eyes glazing over at a penthouse listed for twelve million dollars. You pause, not because you’re shopping, but because you’re quietly asking the universe, “Who actually buys this?” The answer, of course, is someone with a “high net worth.” But here’s the kicker: the definition of that phrase shifts like sand in a luxury hourglass, depending on who you ask and where you’re standing.
Forget the yacht-club stereotypes for a second. The line between “comfortably well-off” and “genuinely wealthy” isn’t just about a number on a screen; it’s a psychological threshold, a passport to different financial conversations. Let’s pull back the velvet rope and look at the actual figures, because knowing the map is half the fun of the journey—even if you’re just sightseeing.
The Baseline: You’re Richer Than You Think
If you’ve ever felt a pang of envy seeing a friend’s stock portfolio, here’s a reality check that might make you sip your coffee a little taller. Globally, the most common global wealth benchmark for “high net worth” (HNWI) starts at $1 million in liquid assets—meaning cash, stocks, and bonds, not your primary residence or your vintage record collection.
That’s the official line from wealth management firms like Capgemini and Merrill Lynch. But let’s be honest: in San Francisco or Manhattan, a million bucks feels like a solid down payment and a used Tesla. In Tulsa or Toledo? That number often represents a very comfortable retirement with zero financial stress. The geography of wealth is real, and it distorts the math beautifully.
The Tiers of “Rich” (A Totally Unscientific but Fun Guide)
To navigate this, you need a taxonomy. Think of it like the Starbucks menu—there’s a size for every ego and budget. At the entry level, you have the “Working Rich” ($1M–$5M), who drive Audis and worry about private school fees. They’re wealthy, sure, but they still check the price of avocados.
Then comes the “Very High Net Worth” ($5M–$30M)—these folks buy the private school, not just the tuition. They have a wealth advisor on speed dial and debate the merits of buying a vineyard in Napa. Above them, the “Ultra High Net Worth” (UHNW)—the $30M-plus club—where money stops being about lifestyle and becomes a scoreboard. That’s where you find the private islands and the custom Bugattis.
Here’s a little cultural touchstone: remember the movie Crazy Rich Asians? Nick Young’s family isn’t just “rich”—they’re UHNW, the kind of wealth that buys a whole hotel for a party. The difference between the tiers isn’t just zeros; it’s the freedom from consequence. At the ultra level, a market dip is a headline, not a headache.
The Real Number That Matters: Net Worth vs. Cash Flow
Here’s a secret the magazines won’t tell you: Net worth is a vanity metric; cash flow is reality. You can be worth $2 million if your house in Austin appreciated, but if you’re still working a 9-to-5 to pay for it, you’re not “high net worth” in the lifestyle sense—you’re just asset-rich and income-poor.
The modern definition is shifting toward “financial independence.” That’s the FIRE movement (Financial Independence, Retire Early) crowd, who argue that if your passive income covers your expenses, you’ve won the game—regardless of the digits. In that lens, a 45-year-old teacher with $800k in index funds and no debt might feel wealthier than a lawyer earning $400k a year who lives in a mortgage balloon.
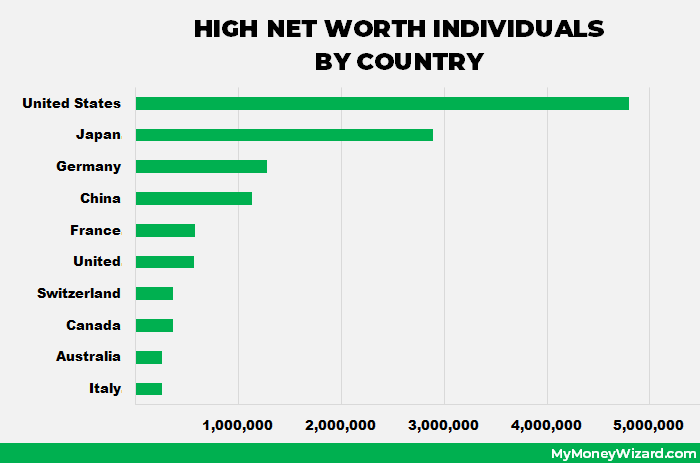 What's actually a high net worth? 11 wild statistics and 4 life lessons
There’s a fun stat from a 2023 Charles Schwab survey: Americans said you need $2.2 million to be considered “wealthy.” But the same survey found that people with $1.9 million felt they needed more. Spoiler: The goalpost always moves. It’s a hedonic treadmill, but it’s paved with gold.
Practical Tips to Feel Rich (Without the Club Membership)
So, how do you leverage this knowledge without a trust fund? First, stop comparing your “liquid assets” to a hedge fund manager’s. Instead, track your net worth monthly, but define “rich” as options, not ostentation. Can you quit your job for six months? That’s your personal HNW threshold.
Second, automate your investments to hit that $1M mark eventually, but remember that time in the market beats timing the market. A late boomer with a $500k portfolio and a paid-off house is often happier than a mid-career doctor with $1.2M but $450k in student loans.
Finally, embrace the “latte factor” with a twist. Fancy coffees won’t ruin you, but lifestyle inflation will. Every time you get a raise, save 50% of it. That’s how you buy back your own freedom—the only currency that truly matters.
The Reflection: It’s All Relative
Here’s the beautiful, humbling truth: High net worth is a moving target, and you’re already wealthier than 90% of the world. If you have a roof, a working car, and can buy groceries without checking the balance—you’re living a life that would make a medieval king weep with envy.
So the next time you see that $12M penthouse, don’t feel small. Feel curious. Ask yourself what kind of freedom you’re actually chasing. Because the most luxurious asset you’ll ever own is your attention—and how you choose to spend it. And that, my friend, is worth more than any net worth statement can capture.