Net Worth, Not Just a Celebrity Buzzword: Your FAFSA Guide
Ever wondered how the likes of Forbes magazine calculate the net worth of your favorite celebrities? It's not just about how many zeros are in their bank account. It's about assets, liabilities, and, yes, even their fancy cars and sprawling mansions. And guess what? The same principle applies when you're filling out your Free Application for Federal Student Aid (FAFSA).
So, grab a cup of coffee, put on your favorite playlist (we're currently vibing to Doja Cat's latest), and let's dive into the world of net worth, FAFSA-style.
Assets: What's Yours is (Sort of) Yours
In the world of FAFSA, assets are the things you own that have value. This could be cash, savings, investments, or even the car you've been saving up for (yes, even that sweet ride you've had your eye on).
Must Read
But here's the thing, not all assets are created equal. The Expected Family Contribution (EFC), which is what FAFSA ultimately calculates, considers only a portion of your assets. Here's a quick breakdown:
- Parental assets: About 5.64% to 20% of parental assets are considered in the EFC, depending on the parents' age and the number of children in college.
- Student assets: A whopping 20% to 50% of student assets are considered in the EFC. Ouch, right?
Now, before you start panicking about your hard-earned savings, remember that these are expected contributions. It's not like FAFSA is going to send you a bill. It's just a number that helps determine your eligibility for financial aid.
Liabilities: When Debt Isn't All Bad
Liabilities are the flip side of the coin. They're the things you owe, like student loans, car loans, or credit card debt. In the FAFSA world, liabilities are subtracted from your assets to calculate your net worth.
Here's a fun fact: The EFC formula considers up to $65,750 in parental debt and $62,200 in student debt as protected, meaning they're not factored into the EFC calculation. So, if you've got a mountain of student loans, that's actually working in your favor.
Calculating Your Net Worth: The FAFSA Way
Now, let's do some math. The FAFSA net worth calculation is pretty simple: Assets minus Liabilities equals Net Worth. But remember, we're only considering the portion of assets that's factored into the EFC.
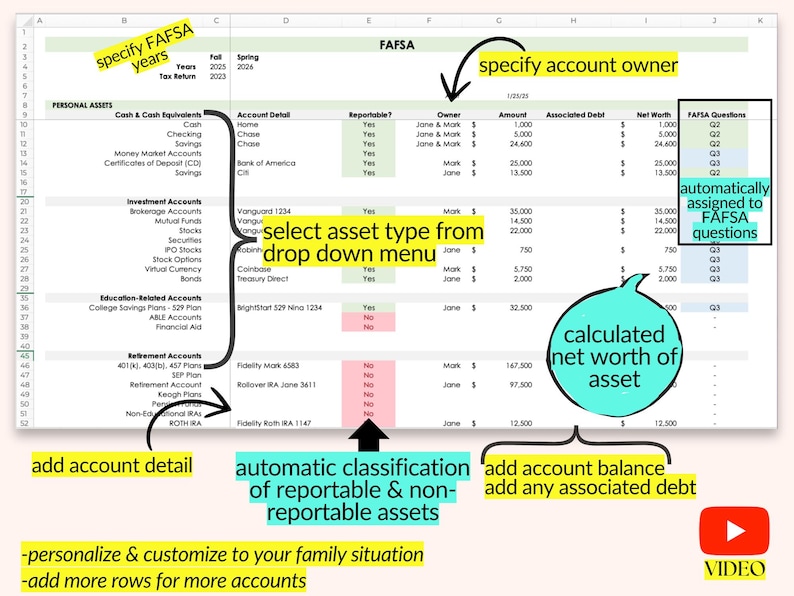
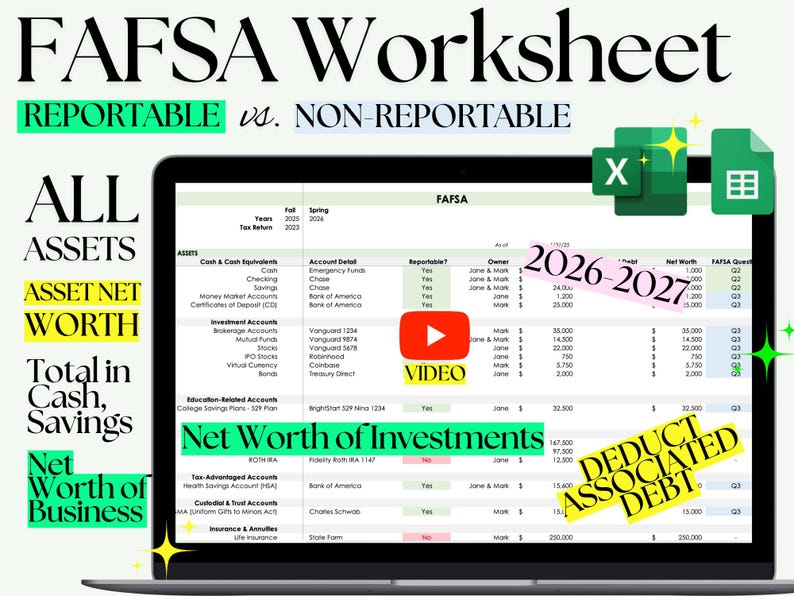 FAFSA Worksheet Template, Asset Net Worth Calculator (excel, Google
Let's say you're a dependent student with $50,000 in parental assets and $10,000 in student assets. Your parents have $20,000 in debt, and you've got $5,000 in student loans. Here's how it breaks down:
- Parental assets considered: $2,820 (5.64% of $50,000)
- Student assets considered: $2,000 (20% of $10,000)
- Total assets considered: $4,820
- Total debt protected: $65,750 (parental) + $62,200 (student) = $128,000
- Net worth for FAFSA: $4,820 - $128,000 = -$123,180
Yes, you read that right. Your net worth for FAFSA purposes is negative. But don't worry, that's just how the formula works. It's not like you're suddenly in debt to the government.
Reflecting on Your Worth
So, there you have it. Calculating your net worth for FAFSA isn't as daunting as it sounds. It's just a matter of understanding what's considered and what's not. And remember, it's not about how much you have, but how much you're expected to contribute.
As you fill out your FAFSA, take a moment to reflect on your worth. Not just your net worth, but your personal worth. You're investing in your future, and that's something to be proud of. So, keep your chin up, and let's get you that financial aid.
And hey, maybe one day, Forbes will be calculating your net worth. Stranger things have happened, right?