
Okay, let’s be honest for a second. When you hear the words “net worth,” do you instantly picture a stuffy banker in a suit, frowning at a spreadsheet? Or maybe you imagine Elon Musk casually checking his billions between tweets? You’re not alone. Most of us think it’s a number reserved for the ultra-rich, not for someone who just spent $40 on takeout because they were too tired to cook. But here’s the secret: your net worth is just a fancy term for your personal financial report card. And checking it is way less scary than checking your teeth in the mirror after eating spinach.
Think of it like this: your net worth is simply what you own minus what you owe. That’s it. No calculus, no stock market wizardry. It’s like figuring out how many slices of pizza you actually have left after you’ve paid your friends back for the delivery fee. Owned minus owed. You’re just doing simple subtraction with your life stuff.
Why Should You Even Bother?
Great question, and I’m glad you asked before skipping this article. Knowing your net worth isn’t about bragging at dinner parties (please don’t). It’s about getting a clear picture of your financial health without any rose-colored glasses. It’s like stepping on a scale—sure, the number might sting, but you can’t fix what you don’t measure.
Must Read
Imagine you’re on a road trip. You wouldn’t just drive around aimlessly hoping to reach the beach, right? You’d check the fuel gauge and the map. Your net worth is that fuel gauge for your money. It tells you if you’re cruising comfortably or if you need to pull over and reassess before you’re stranded on the side of the highway of life. It’s your financial GPS.
The “No-Judgment” Check-In
Here’s the best part: you don’t need an app that costs $200 a month or a fancy accountant. You can do this with a piece of paper, a notes app on your phone, or even a napkin if you’re feeling bold. Grab everything you own that has value. That’s your “assets” box. We’re talking about your checking account balance, your savings, that 401(k) from your first job, the current value of your car (sorry, that dent didn’t help), and even that weird coin collection your uncle gave you.
Don’t forget the small stuff! That $500 in cash you keep in a drawer for emergencies counts. That old guitar you bought in college? If it still plays, it’s worth something. Every little bit adds up. You’re basically cataloging your treasure chest, and it’s surprisingly satisfying to see it all in one place.
Now, The Not-So-Fun Part: Your Debts
Okay, take a deep breath. This is the “liabilities” side. This is what you owe to others. That includes your credit card balance (we won’t judge the sushi splurge), your student loans, your car loan, and any money you borrowed from your mom. Write down the total amount you owe for each. Yes, all of it. Avoid the temptation to “forget” that one small loan. It’s still your co-pilot on this ride.
 What is my net worth and how does it impact my retirement
Seeing your debts listed out can feel like looking at a pile of dirty laundry. It’s not pretty, but it’s real. The goal isn’t to feel shame; it’s to see the full picture. You can’t plan a budget or make better money moves if you’re pretending half your debt doesn’t exist. Ignorance might be bliss, but it’s also expensive.
Do The Simple Math
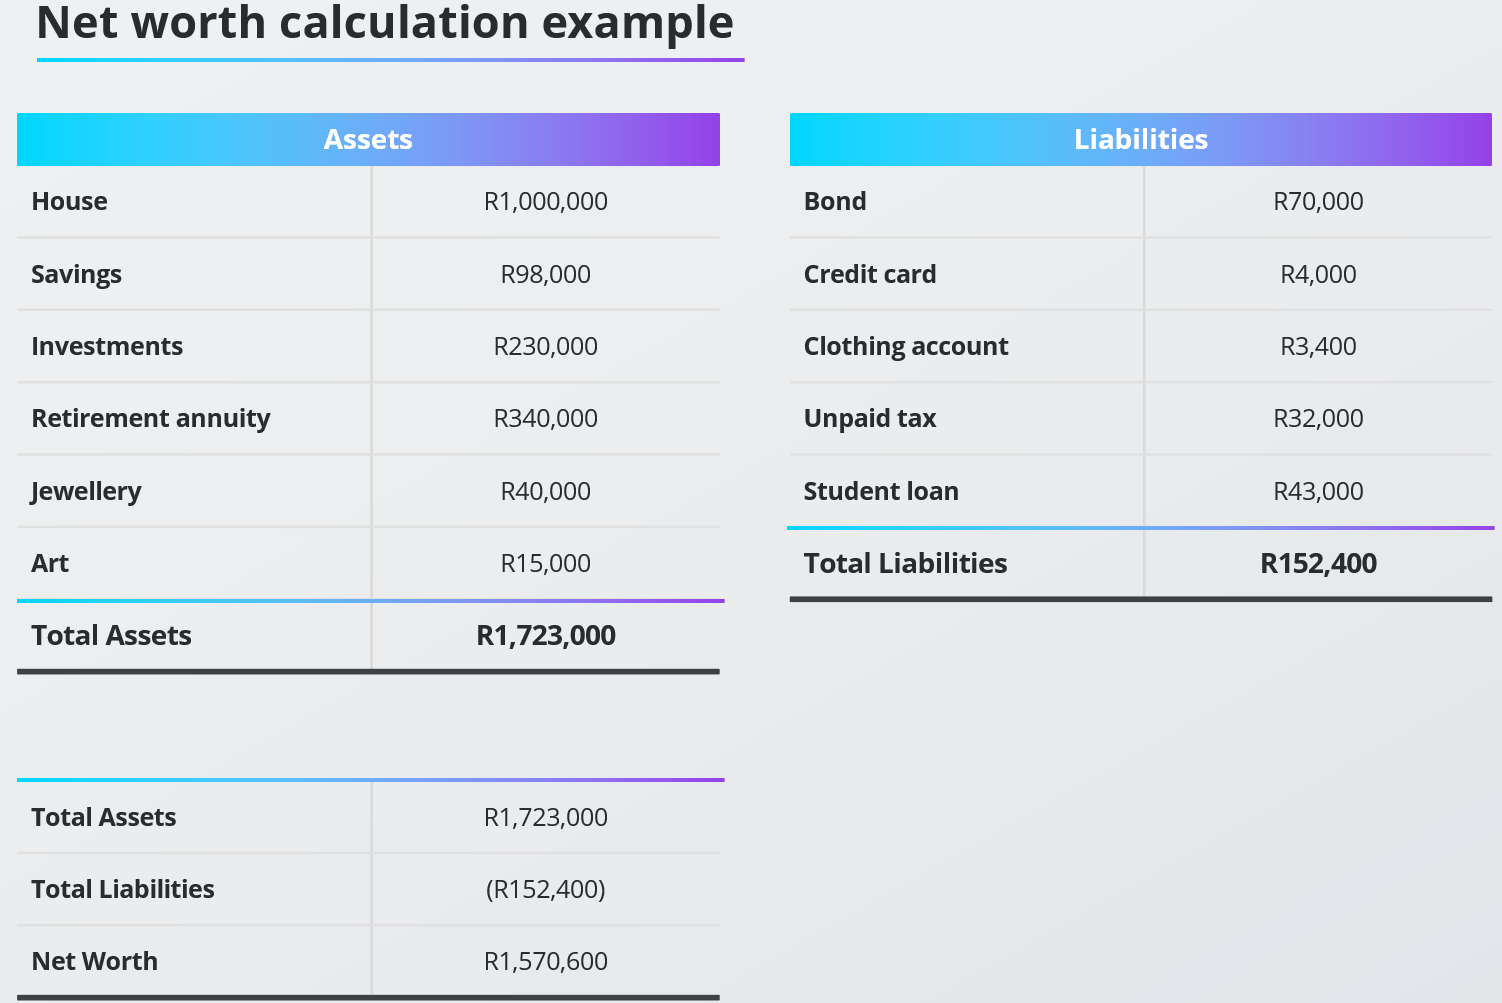
Now for the grand finale. Take your total assets (the good stuff) and subtract your total liabilities (the not-so-good stuff). The number you get, whether it’s positive or negative, is your net worth. If it’s a positive number, congratulations! You’re officially “in the black.” If it’s negative, you have a lot of company, so please try not to panic. A negative net worth doesn’t make you a failure. It just means you’re early in your journey, and that’s totally okay.
For example, Sarah has $2,000 in her savings account and a car worth $8,000. That’s $10,000 in assets. But she has $12,000 in student loans and a $500 credit card bill. Her liabilities are $12,500. So, her net worth is $10,000 minus $12,500, which equals negative $2,500. Looking at that number might make her cringe, but now she knows exactly where she stands. She can now decide to tackle that credit card first because it has the highest interest rate. That’s powerful info.
Make It A Date, Not A Chore
Don’t do this every day. You’ll go crazy. Instead, check your net worth once a month or once a quarter. Think of it like a little coffee date with your money. Grab a latte, sit down, update the numbers, and see if you moved the needle. Did you pay off some credit card debt? Did you get a raise and stashed the extra cash? Watching that number climb, even by a little, feels like winning a mini-game.
And here’s the most freeing part: it’s just a number. It doesn’t define your worth as a human being. You could have a low net worth and be the best friend, parent, or neighbor on the planet. But by checking it, you’re telling yourself, “Hey, I care about my future, and I’m not afraid to look at the details.” That’s a pretty badass attitude. So go ahead, grab your calculator, and give it a shot. Future you will be genuinely grateful.