Okay, let’s be real for a second. The phrase “net worth” sounds like something a billionaire in a tailored suit whispers to his accountant while sipping a $5,000 bottle of wine. But guess what? It’s just a fancy way of asking, “If I sold everything I own and paid off all my debts, how much cold, hard cash would I have left?”
See? Not scary. It’s basically the adult version of counting your piggy bank change, except the piggy bank is your 401(k) and the change is… well, hopefully more than quarters. So grab your coffee, put down the panic, and let’s figure this out together. I promise it’s easier than assembling IKEA furniture.
The Great Math Adventure (It’s Just Addition and Subtraction)
First, we need to get our hands on the two main ingredients: what you own and what you owe. We call these assets and liabilities, but let’s call them “your stuff” and “the stuff that haunts you.” Easy enough, right?
Must Read
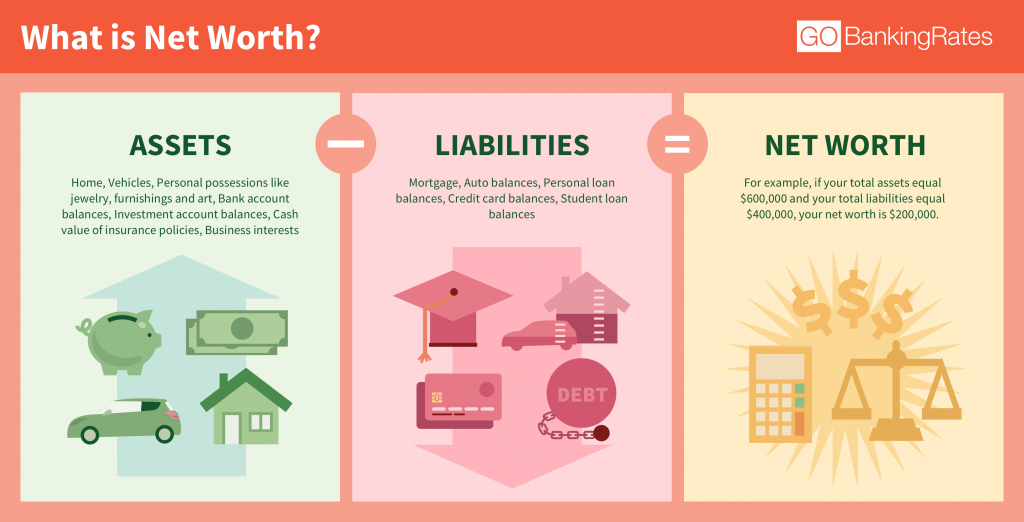
Start with your assets. That’s everything that has value and could be turned into money. I’m talking about your checking account balance, that savings account you’re ignoring, and any investments you might have (stocks, bonds, or that weird crypto your cousin told you about).
Don’t forget the big stuff. Your car, even if it smells like old fries, counts. Your house, if you own one, counts for its current market value, not what you paid for it in 2015. And that vintage guitar in your closet? Yes, that counts too. You’re richer than you think.
Now for the uncomfortable part: the liabilities. Write down every single debt. Credit cards, student loans, that personal loan from your buddy Mark, and your mortgage. If you owe money on the car, subtract that remaining balance. This is the “ouch” column, but we can’t skip it.
Time to Do Some Quick (And Painless) Math
Okay, here’s the secret formula that financial gurus don’t want you to overthink: Assets minus Liabilities equals Net Worth. That’s it. No calculus. No wizardry. Just subtraction.
Let’s say your assets total $50,000. And your debts total $30,000. Your net worth is $20,000. Boom. You just calculated your entire financial life in under two minutes. Go ahead, give yourself a little high-five. You earned it.
But what if the number is negative? Like, minus a few thousand? Breathe. That’s super common, especially if you’re young or just finished school. A negative net worth doesn’t make you a failure. It just means you’re currently worth less than zero on paper, which honestly sounds like a superhero origin story.
 Calculating Your Net Worth Chapter 1 Lesson 4 Answer Key - Verified
Why Should You Even Care? (Aside from Bragging Rights)
Knowing your net worth is like stepping on a scale. It’s a snapshot, not a life sentence. It shows you a trend. If your number goes up over time, you’re on the right track. If it goes down, you might need to stop ordering so many fancy oat milk lattes (I’m talking to myself here).
It also makes you feel incredibly adult. Seriously. The next time someone mentions “financial health,” you can nod thoughtfully and say, “I checked my net worth last week.” That phrase will instantly make you seem responsible, even if you’re wearing pajama pants on a video call.
And look, this number isn’t a measure of your worth as a human. You are not your portfolio, okay? Your kindness, your sense of humor, and your ability to open a pickle jar all matter way more than your balance sheet. But knowing the number gives you a baseline to improve upon.
How Often Should You Do This? (Don’t Overthink It)
Please, for the love of your sanity, don’t check this daily. That’s a recipe for an anxiety spiral if the stock market dips. Instead, do it once a month. Or once a quarter if you’re a busy person. Even once a year works, honestly.
Every time you check, you’ll see a little picture of your progress. Maybe you paid off a credit card. Maybe you got a raise. Maybe you sold that old guitar. Each little change nudges the number in a great direction. That’s motivating!
I like to do it on the first of the month with a glass of iced tea. Make it a ritual. Celebrate the wins, even the tiny ones. And if the number dips? Just shrug and say, “Well, next month’s a fresh start.” Because it is. That’s the beauty of math.
So, go on. Grab a napkin, a calculator app, or a spreadsheet if you’re feeling fancy. Add up your stuff, subtract your debts, and boom. You now know your net worth. Go flex on someone (politely, of course). You just leveled up in the game of adulting, my friend.