
There's a question that pops into our heads somewhere between scrolling through Instagram and sipping our morning coffee: What am I actually worth? Not in a philosophical way—though that's fun over wine—but in the real, numbers-on-a-spreadsheet way. Finding your net worth is one of the most illuminating financial exercises you'll ever do, and honestly, it's easier than choosing what to binge-watch next.
So, What Exactly Is Net Worth?
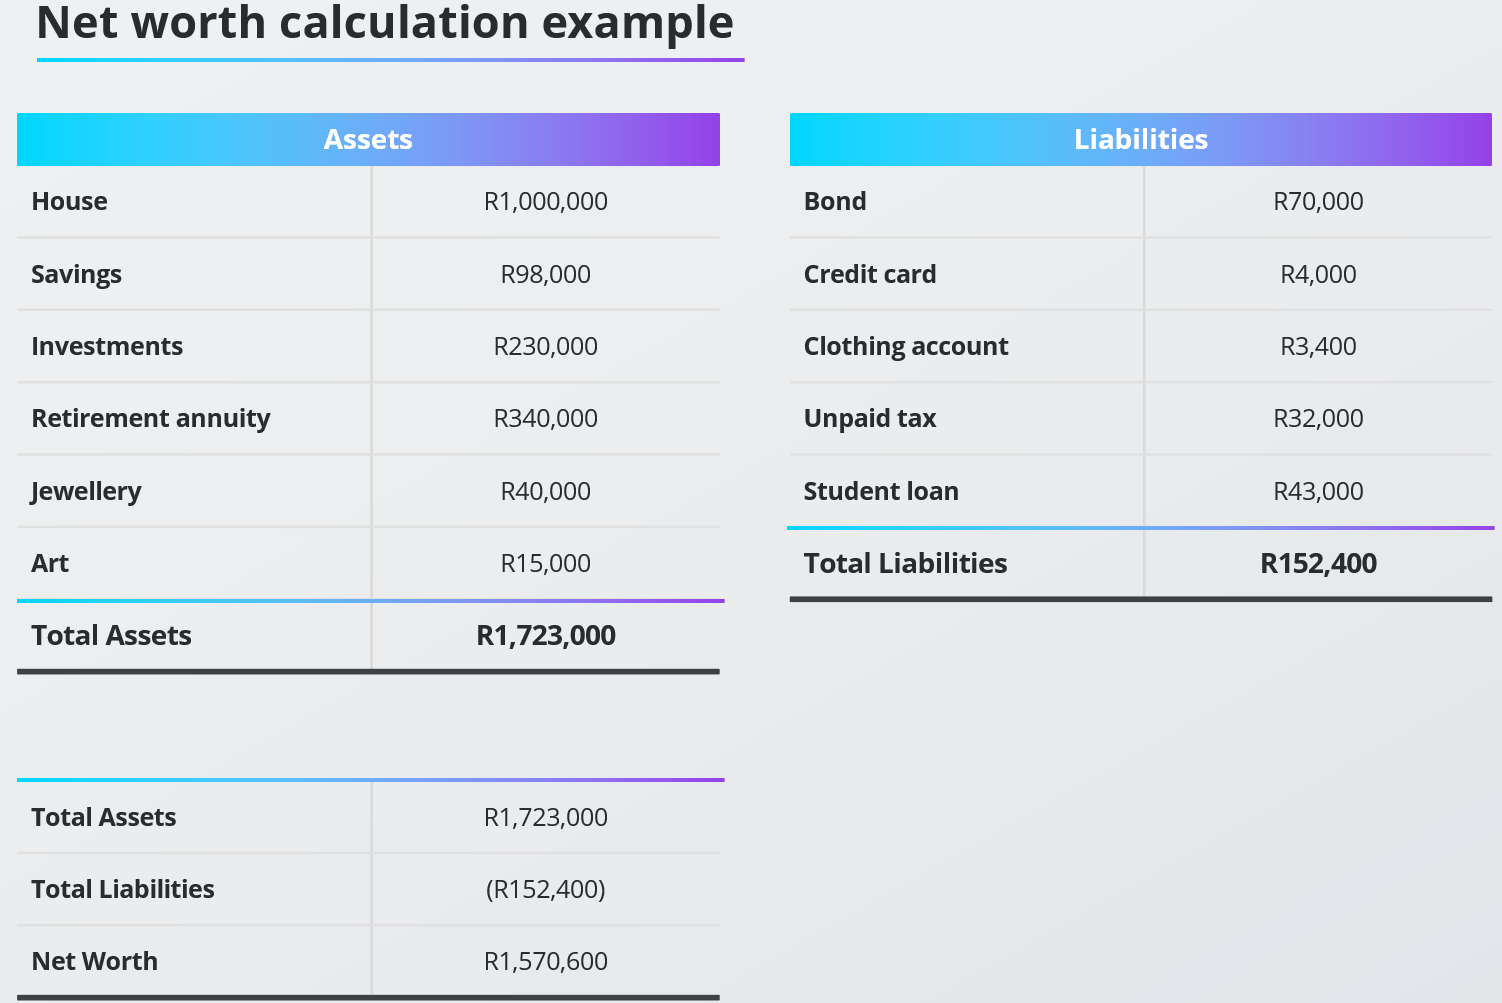
Think of net worth as your personal financial rap sheet—just without the mugshot. It's the difference between everything you own and everything you owe. That one simple equation reveals a surprisingly complete picture of where you stand financially.
In other words, it's your assets minus your liabilities. If you have $50,000 in savings and your grandma's vintage lamp collection counts, you subtract your $15,000 in student loans. What remains is your net worth, for better or worse.
Must Read
Step One: List Everything You Own
Start by gathering your assets like you're prepping for a very boring treasure hunt. Bank accounts, investments, real estate, the vintage car that might be worth something someday—everything goes on the list. Even the equity in your home counts, so pull out that mortgage number.
Don't forget about digital assets like cryptocurrency or that suspicious investment your cousin keeps texting you about. Certificates of deposit, retirement accounts, and emergency savings all belong here too. The more thorough your list, the more accurate your picture becomes.
Step Two: Add Up Everything You Owe
Now comes the part that makes most of us squirm—your liabilities. Credit card balances, car loans, mortgages, student loans, and any personal debts you've been avoiding. List every single one, no matter how small, because ignoring a $200 balance won't make it disappear.
Even that "I'll pay you back someday" promise to a friend belongs on this page. If money is owed, it counts against your net worth. Honest math leads to honest clarity.
Step Three: Do the Simple Math
Here's where the magic happens—or at least the insight. Subtract your total liabilities from your total assets, and voilà: you've just calculated your net worth. It's essentially your personal financial scorecard, updated in real time.
If the number is positive, congratulations—you're ahead of the game. If it's negative, don't panic; millions of people start there, including many who ended up millionaires. A net worth is a snapshot, not a life sentence.
Tools That Make It Effortless
Nobody wants to spend three hours with a calculator unless that calculator lets them buy shoes with it. Luckily, apps like Mint, Personal Capital, and Net Worth Tracker pull your accounts together automatically. They do the tedious work so you can focus on the fun part—the trends.
Spreadsheet lovers can build a custom template in Google Sheets or Excel for full control. Some people keep it old-school with a warm cup of coffee and a hand-written ledger. Whatever your style, consistency matters more than the method.
Cultural Money Moments
We live in a culture that loves to flaunt lifestyles but rarely talks about net worth. MTV's "Cribs" made mansion tours look normal while most viewers drove used Hondas. Meanwhile, Warren Buffett—the second-wealthiest person alive for decades—drives the same car type for years.
 What is my net worth and how does it impact my retirement
The lesson? Net worth often looks nothing like the aesthetic of wealth. A flashy sports car bought on credit could mean someone's net worth is trending downward. Quiet accumulation, by contrast, builds fortunes that last generations.
Fun Fact: The Billionaire Benchmark
Did you know that becoming a billionaire means your net worth has three commas? If you earned $1 per second, you'd need about 31 years to reach one billion. That's roughly how much longer you'd sit in traffic driving from Los Angeles to New York—five times over.
On a friendlier note, the average American household net worth sits around $192,900 according to recent Federal Reserve data. Meanwhile, the global average is around $84,500, though that varies wildly by country. Knowing these benchmarks helps put your own number in perspective.
Track It, Don't Just Calculate It
Finding your net worth once is helpful; tracking it monthly is transformative. Just like checking your Gucci bag in the mirror before heading out, a regular financial check-in keeps you looking sharp. Trends over twelve months tell a far richer story than a single number ever could.
Set a reminder on your phone to revisit it during the first week of each month. Celebrate the wins, however small, and adjust the plan when things dip. Your net worth is a living number, and it responds to the habits you build today.
Quick Tips for a Healthier Number
Small changes compound like a good skincare routine—only for your finances. Start by automating savings, even if it's just $25 a week, because automation removes the temptation to spend. Paying down high-interest debt first gives your net worth the quickest boost.
Investing early, even in a basic index fund, turns time into your greatest ally. Every dollar you don't owe and every dollar you wisely own pushes the number in the right direction. Treat it like a marathon, not a sprint.
A Little Reflection
Net worth isn't just a cold calculation—it's a mirror for the choices you make between Netflix episodes. It reflects patience, discipline, ambition, and sometimes the messy reality of life getting in the way. And that's perfectly okay, because the most valuable thing you can own might be the clarity to move forward with intention.
The next time you wonder where you stand financially, you'll know exactly where to look. Open the spreadsheet, open the app, or open your eyes—and start counting what truly matters.