
Last Tuesday, I found myself staring at my bank account like it was a Magic 8 Ball, hoping the numbers would rearrange themselves into something more… flattering. My friend Jake, a guy who owns a beat-up Honda and a surprisingly robust stock portfolio, laughed when I told him. He didn’t laugh at my balance, but at my question: “So, what’s my net worth, anyway?” I thought it was just a fancy term for “how much cash I have left after rent.” Oh, how naive I was. (You’re probably nodding your head right now, aren’t you? Don’t worry, we’ve all been there.)
Here’s the kicker: your net worth is not your salary, and it’s definitely not the amount in your checking account. It’s the single most honest number about your financial life, and it’s surprisingly easy to calculate once you get past the initial dread. Think of it as a financial report card, but instead of grades, it’s just a cold, hard number. The goal isn’t to be a millionaire by 30 (though, hey, if that’s you, call me); it’s to know exactly where you stand so you can stop guessing.
The Simple Math That Scares Everyone
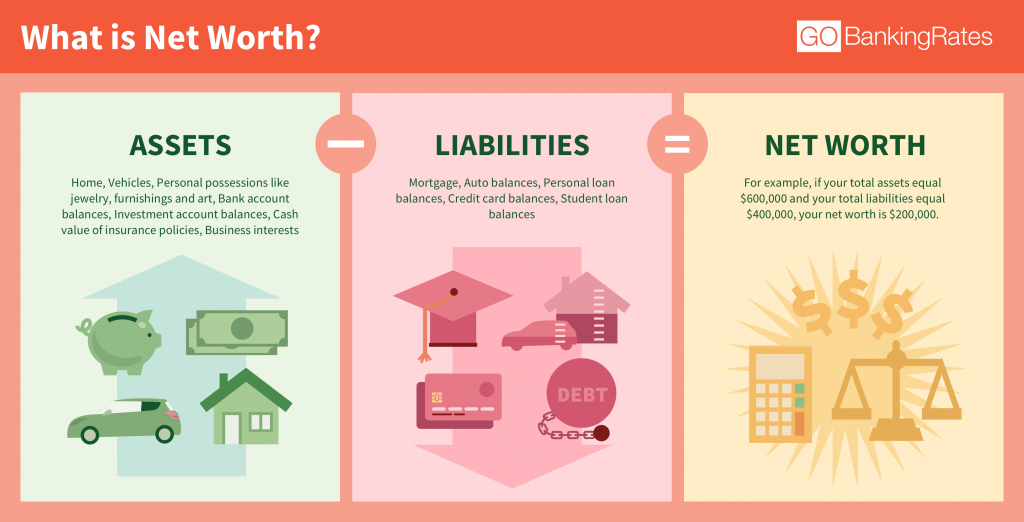
Forget the complicated spreadsheets and the Bloomberg terminals. Your net worth is literally one subtraction problem: Total Assets minus Total Liabilities. That’s it. If you own more than you owe, you’re in the green. If you owe more than you own, you’re in the red—which, by the way, is not a moral failure, just a starting point. (I once did this calculation and felt like I needed a cigarette, and I don’t even smoke.)
Must Read
Let’s break down the “Assets” side first. This is everything you own that has monetary value. We’re talking cash in all your bank accounts, your 401(k) or IRA balances, the current market value of your car (not what you paid for it, sorry), and any real estate you own. Don’t forget that old comic book collection or the vintage guitar you never play—if you could sell it for money, it counts. Everything.
Now, the Liabilities—the buzzkill side of the equation. This is every dollar you owe to someone else. Your mortgage balance, your car loan, student loans, credit card debt, and even that $50 you owe your buddy for pizza last month (yes, it counts, and you should pay him back). The key here is to use the current payoff amounts, not the minimum monthly payments. We’re talking total debt, not your monthly bill.
Why Your Brain Will Try to Lie to You
Here’s where it gets psychological. Your brain will tell you, “My car is worth $15,000 because I paid $25,000 for it three years ago.” That is a lie. Your car is worth what a stranger will pay you today, which is probably $8,000 if the check engine light is on. Use real numbers, not hopeful ones. Look up your car’s value on Kelley Blue Book, check your investment statements for the actual balance, and log into your loan portal for the true payoff amount.
Similarly, you might be tempted to ignore your credit card debt because it feels “temporary.” Don’t. That’s like ignoring a leaky roof because it’s not raining right now. The debt is there, it’s real, and it’s part of the math. The only way to fix your financial health is to first accept the full, unvarnished truth of your liabilities. (Deep breaths, we’re almost done with the heavy stuff.)
 Determine Your Net Worth in 3 Easy Steps! - New Century Investments
What Your Net Worth Actually Tells You
Once you have your number—let’s say it’s negative $5,000—you might panic. But here’s the secret: a negative net worth in your 20s or 30s is normal, especially if you have student loans or a mortgage. It doesn’t mean you’re broke; it means you’re investing in your future. The real magic is in the trend, not the absolute number. If your net worth goes up by $500 every month, you’re building momentum, even if the total is still in the red.
Your net worth is also a fantastic bullshit detector. It cuts through the noise of lifestyle inflation. You know that guy on Instagram with the leased BMW and the $12 juices? His net worth might be lower than yours, and that’s the tea. This number doesn’t care about your job title or your zip code; it only cares about mathematical reality.
How to Get a Better Number (Without Sacrificing Your Social Life)
Tracking your net worth isn’t a chore; it’s a form of self-respect. You don’t need a fancy app—a simple spreadsheet or even a piece of paper works. I recommend calculating it once a month, not every day. Daily checking leads to anxiety; monthly check-ins give you a clear, sane picture of your progress. It’s like stepping on a scale: you don’t weigh yourself after every meal, only every few weeks.
Also, don’t get obsessed with comparing yourself to “average” net worth by age. Those charts are skewed by billionaires and people who inherited trust funds. Your only competition is last month’s you. So, grab your bank statements, your loan balances, and your 401(k) log-in. Spend 20 minutes doing the math, and then go treat yourself to a coffee (yes, even if you’re in the negative—you’ve earned it).
And hey, if you do the math and find out you’re worth more than you thought? Don’t get smug. Just quietly update your emergency fund and keep going. The goal isn’t to be rich; it’s to be aware. And now, you are. Go forth and subtract.