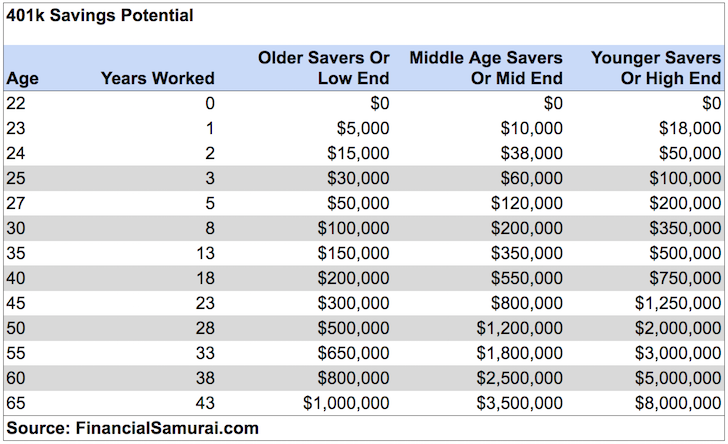
Picture this: you’re sprawled on your couch, doom-scrolling through finance TikTok, and someone casually drops the phrase “net worth.” Instantly, you think of billionaires’ yachts and your own modest checking account. But then the kicker lands—should that 401(k) balance you’ve been squirreling away actually count in that grand total? It’s the kind of question that feels both deeply nerdy and surprisingly existential. Let’s unpick it together, with a latte in hand and zero judgment.
The Short Answer? Yes—But Let’s Get Cozy With the “Why”
Simply put, your 401(k) is absolutely included in your net worth. Net worth is the ultimate scoreboard of your financial life: everything you own (assets) minus everything you owe (liabilities). Your retirement account is an asset, plain and simple, even if you can’t touch it without a penalty until you’re 59½.
Think of it like a vintage wine collection—you’re not drinking it tonight, but it’s still valuable property sitting in your cellar. Excluding it would be like saying your house doesn’t count because you live in it. Silly, right?
Must Read
In fact, financial advisors universally agree: ignoring your 401(k) gives you a laughably incomplete picture of your financial health. It’s like checking your weight but only counting your left leg.
Why People Get Confused (The “Locked Box” Illusion)
The confusion stems from the fact that a 401(k) feels like a locked box—you can’t access it freely, and there are tax penalties for early withdrawal. That psychological barrier makes some folks think, “Well, if I can’t spend it, it doesn’t count.” But your net worth isn’t about what you can spend today; it’s about what you own over a lifetime.
Here’s a fun cultural parallel: remember when Ross from Friends got a “divorce” from Emily but still wore his wedding ring? That ring was still an asset, even though the relationship was toast. Your 401(k) is the same—it’s a legally binding asset, regardless of when you plan to cash in on it.
Also, consider that your net worth is a snapshot for lenders, mortgage brokers, and even your future self. They don’t care about your liquidity timeline; they care about your total financial firepower.
The Nitty-Gritty: What Actually Goes Into the Math
When you calculate net worth, you add up all your assets: checking accounts, savings, home equity, cars (yes, deduct what you owe), and yes, the full balance of your 401(k) and IRA. Then you subtract your liabilities—credit card debt, student loans, your mortgage, that sneaky personal loan from Uncle Bob.
Your 401(k) balance should be the gross amount—the number on your latest statement, before any potential future taxes. Some ultra-detail-oriented folks subtract an estimated tax liability (since you’ll owe income tax on withdrawals), but that’s optional. For most of us, the raw number is fine—it’s like estimating your height without taking off your socks.
Fun little fact: the average 401(k) balance for a 50-year-old is around $180,000, according to Vanguard’s 2023 data. That’s not chump change—that’s a serious chunk of your net worth pie, often 30-50% for mid-career savers.
Practical Tips for Your Own Net Worth Statement
First, stop treating your retirement accounts like a shameful secret. Log into your 401(k) portal, screenshot that number, and put it next to your checking account total. The visual alone feels empowering—like finally cleaning out that junk drawer.
Second, update your net worth quarterly, not daily. The stock market swings wildly; if you check daily, you’ll either get euphoric or nauseous. Instead, set a calendar reminder for the first week of January, April, July, and October. Treat it like a spa day for your finances.
 Empower Retirement After Tax Contributions at Gerald Murdock blog
Third, don’t obsess over the tax nuance unless you’re a pro. If you want a more pessimistic but realistic picture, subtract 20% from your 401(k) balance as a stand-in for future taxes. But honestly? That’s for accountants and worrywarts. The mainstream definition includes the full balance, so just roll with it.
The Pop Culture Net Worth Check
Let’s drag a celebrity into this for fun. Imagine Taylor Swift’s net worth—she has cash, real estate, royalties, and a fat retirement account (we assume). Does anyone doubt her wealth because she can’t easily liquidate her pension? No. Her net worth is a massive number because everything counts.
Or think of the movie The Wolf of Wall Street. Jordan Belfort’s net worth was inflated by stocks and assets—not just cash in a mattress. Your 401(k) is the legal, boring, responsible cousin of that energy.
Here’s a quirky tidbit: the term “net worth” dates back to 1600s England, where aristocrats counted their land, gold, and even their servants’ value. We’ve evolved, but the principle remains—assets are assets, whether they’re locked in a vault or a Fidelity account.
The “Roth vs. Traditional” Twist
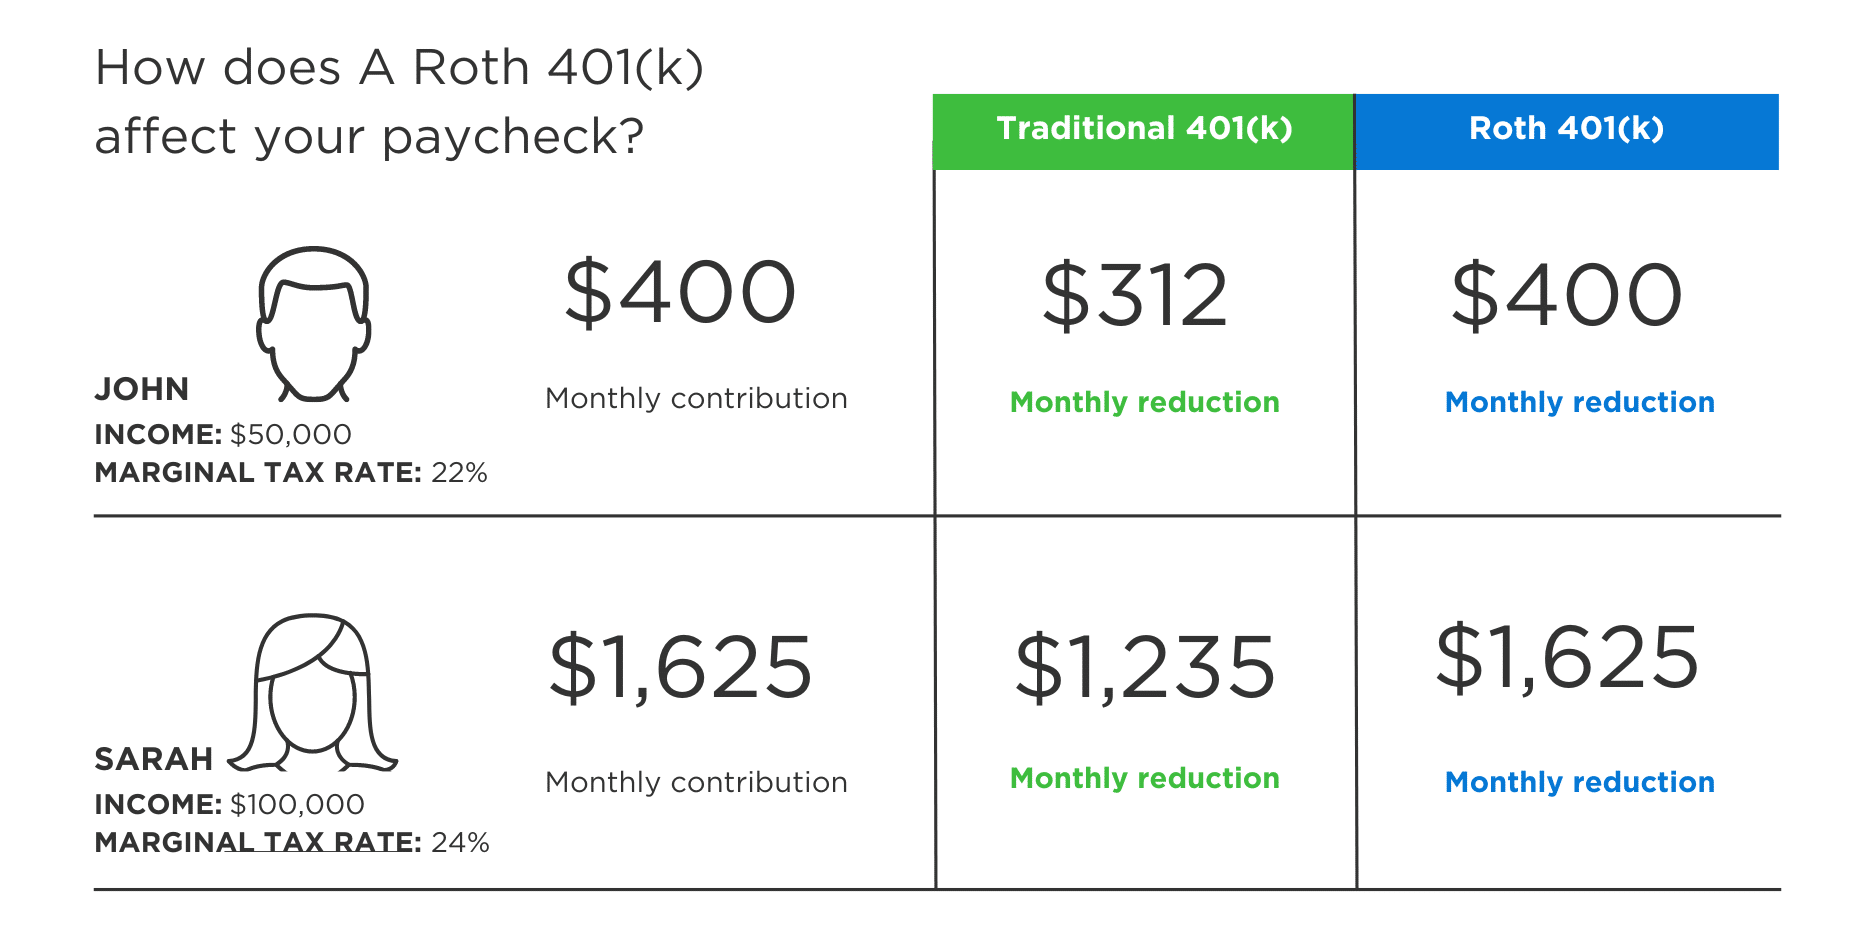
One small caveat for the ultra-nerdy: if you have a Roth 401(k), that’s even more straightforward. Since you’ve already paid taxes on those contributions, every single penny counts as pure net worth. A traditional 401(k) has a hidden tax bill waiting in the future, but again—we’re not splitting hairs unless you’re doing formal financial planning.
And for the self-employed with SEP IRAs? Same rule. Solo 401(k)s? Count them. All of it goes into the big bucket. The only asset that doesn’t count is your life insurance cash value if you haven’t borrowed against it—but that’s a whole other article.
A Gentle Reality Check
Including your 401(k) might make you feel richer, but remember: it’s not spendable cash for emergencies. That’s why financial gurus also recommend having 3-6 months of liquid savings outside retirement. Your net worth can be a million, but if your car breaks down and you only have $500 in your checking account, you’re still in a pickle.
So think of net worth as your financial resume—it’s impressive for job interviews, loan applications, and Nextdoor bragging rights. But your cash flow is your day-to-day heartbeat. Both matter, but they answer different questions.
Final Reflection: The Set-It-and-Forget-It Reality
Here’s the unsexy truth: most people don’t know their net worth off the top of their head, and that’s okay. The real win isn’t the number—it’s the habit of saving, regardless of how you label it. Your 401(k) is a quiet little soldier marching toward your future, and yes, it counts every single step of the way.
When you check your net worth this weekend, pour a glass of something nice. Include that 401(k) figure, smile at the progress, and then log off. Because the point isn’t just to have a big number on a spreadsheet—it’s to sleep better knowing you’re building a life, one pre-tax dollar at a time. And that’s worth more than any net-worth metric could ever capture.