So, you’re sprawled on your couch, doom-scrolling through retirement calculators at 11 p.m., and a terrifying thought bubbles up: “Is my 401(k) actually mine? And more importantly, does it count when I brag about my net worth at a cocktail party?”
Take a deep breath, grab a snack, and let’s untangle this financial knot. The short, shocking answer is: Yes, your 401(k) is absolutely part of your net worth. But—and this is a big, greasy, pepperoni-sized “but”—it’s not the same as having that cash sitting in your checking account, ready to buy a jet ski.
What the Heck Is Net Worth, Anyway?
Think of net worth as your financial report card, but for grown-ups who have bills. It’s the big, hairy math problem: Everything you own (assets) minus everything you owe (liabilities).
Must Read
Your 401(k) is a giant, beautiful asset. It’s a pile of money that has your name on it, even if the government is standing behind you with a clipboard, waiting to take a nibble when you finally pull it out. So, when you add up your house, your car, your Beanie Baby collection from 1998, and that dusty old savings bond from grandma—the 401(k) goes right in the pile.
Don’t let anyone tell you otherwise. If someone says, “Oh, I never count my 401(k),” they’re either a billionaire who forgets about pocket change, or they’re lying to seem mysterious. It’s your money, folks. It’s just wearing a very itchy sweater called “retirement.”
Yes, It’s Real Money. But It’s Also a Magic Trick.
Here’s the part that feels like a mind-bender. Your 401(k) is real, but it’s trapped in a time-out chair until you turn 59½. Think of it like a delicious lasagna that’s still in the oven—you can smell it, you know it’s yours, but if you pull it out early, you’re going to burn your fingers with a 10% penalty and a tax bill that makes you weep.
So, when calculating net worth, include the full, current balance. That’s the honest number. But for the love of all that is holy, do not pretend you can use it to pay off your credit card debt tomorrow. That’s like saying you’re rich because you own a gold bar that’s sitting at the bottom of a shark tank.
The funny thing? People do this all the time. They see a $500,000 balance on their statement and suddenly feel like a Wall Street wolf. Then they ignore the $50,000 they owe on a car that’s worth $20,000. The math doesn’t lie, but it does love a good practical joke.
The Two Types of “Rich” People
Let’s talk about cash flow vs. net worth. You can have a net worth of $2 million and still eat ramen for dinner because it’s all locked up in your house and retirement accounts. Conversely, you can make $500,000 a year, spend every penny, and have a net worth that’s a sad, lonely negative number.
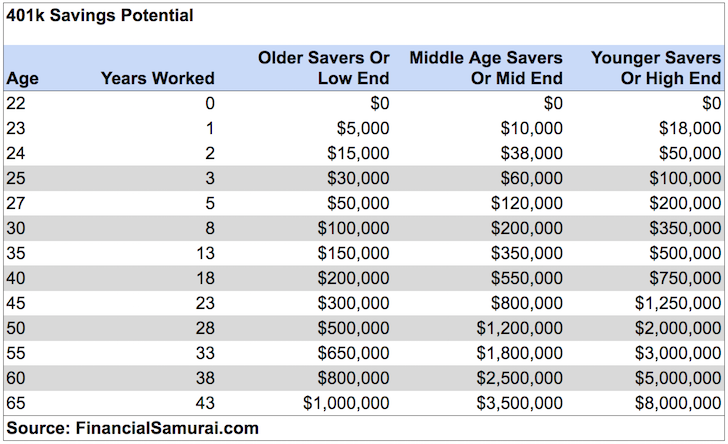 The Average Net Worth For A 30 Year Old - Financial Samurai
Your 401(k) is the ultimate “future you” flex. But it’s a liquidity nightmare. In the world of net worth, it counts for 100% of its value. But in the world of “can I buy a taco right now?”, it’s worth exactly zero pesos. That’s why financial advisors get grey hair—they have to explain that to people who want to retire at 55.
Here’s a Surprise: It Counts More Than You Think
Here’s a fun, bizarre fact: Your 401(k) is actually more valuable to your net worth than a paid-off car. Why? Because a car depreciates faster than a celebrity marriage. But a 401(k), if invested in a decent index fund, historically grows at around 7-10% a year after inflation, thanks to the miracle of compound interest.
So, a $100,000 401(k) isn’t just $100,000. It’s a little money tree that keeps growing acorns. When calculating your net worth, you’re not just counting the money today—you’re counting the potential of that money to become a giant redwood of financial security. That’s not just an asset; it’s a time-traveling asset.
But here’s the kicker: Don’t subtract the taxes you’ll owe later from your net worth. Why? Because nobody does that for a brokerage account, and also, tax laws change more often than pop star hairstyles. Keep it simple. Count the gross balance, and let future-you deal with the tax man. That’s a classic “future-you’s problem” move.
The Bottom Line (Like a Classy Pair of Pants)
So, is your 401(k) part of your net worth? Yes, unequivocally, and without a doubt. It’s a massive chunk of your financial identity. It’s the nerdy, responsible kid in the family of your assets.
Just remember the golden rule of net worth: It’s a scoreboard, not a wallet. You wouldn’t brag about your high score in a video game if you couldn’t pause the game to pee. Similarly, don’t brag about your 401(k) if you can’t access it without a penalty. Own it, track it, and smile knowing that you’re richer than you feel—just a little more locked up than you’d like.
Now, go check your balance, feel a tiny surge of pride, and then immediately remember you still have to mow the lawn. That’s the beautiful, weird, and hilarious reality of personal finance. Your net worth is a beast, and your 401(k) is its loyal, slightly boring sidekick.