Picture this: you’re staring at your banking app, watching the numbers do their little digital dance, and you feel a warm glow of pride. But then a sneaky thought creeps in—is this all I’ve got, or is this just the tip of the iceberg? Welcome to the wonderfully confusing world of net worth and its cooler, more liquid cousin, liquid net worth. Don’t worry, we’re going to untangle this without a single spreadsheet-induced headache.
Your Financial Avatar vs. Your 'In Case of Emergency' Fund
Think of your net worth as your financial avatar—the grand total of everything you own (house, car, that vintage comic book collection) minus everything you owe (mortgage, student loans, that bet with your uncle). It’s a fantastic, big-picture number that tells you how much wealth you’ve built over a lifetime. It’s the scoreboard of your financial game, and it’s genuinely fun to watch it grow.
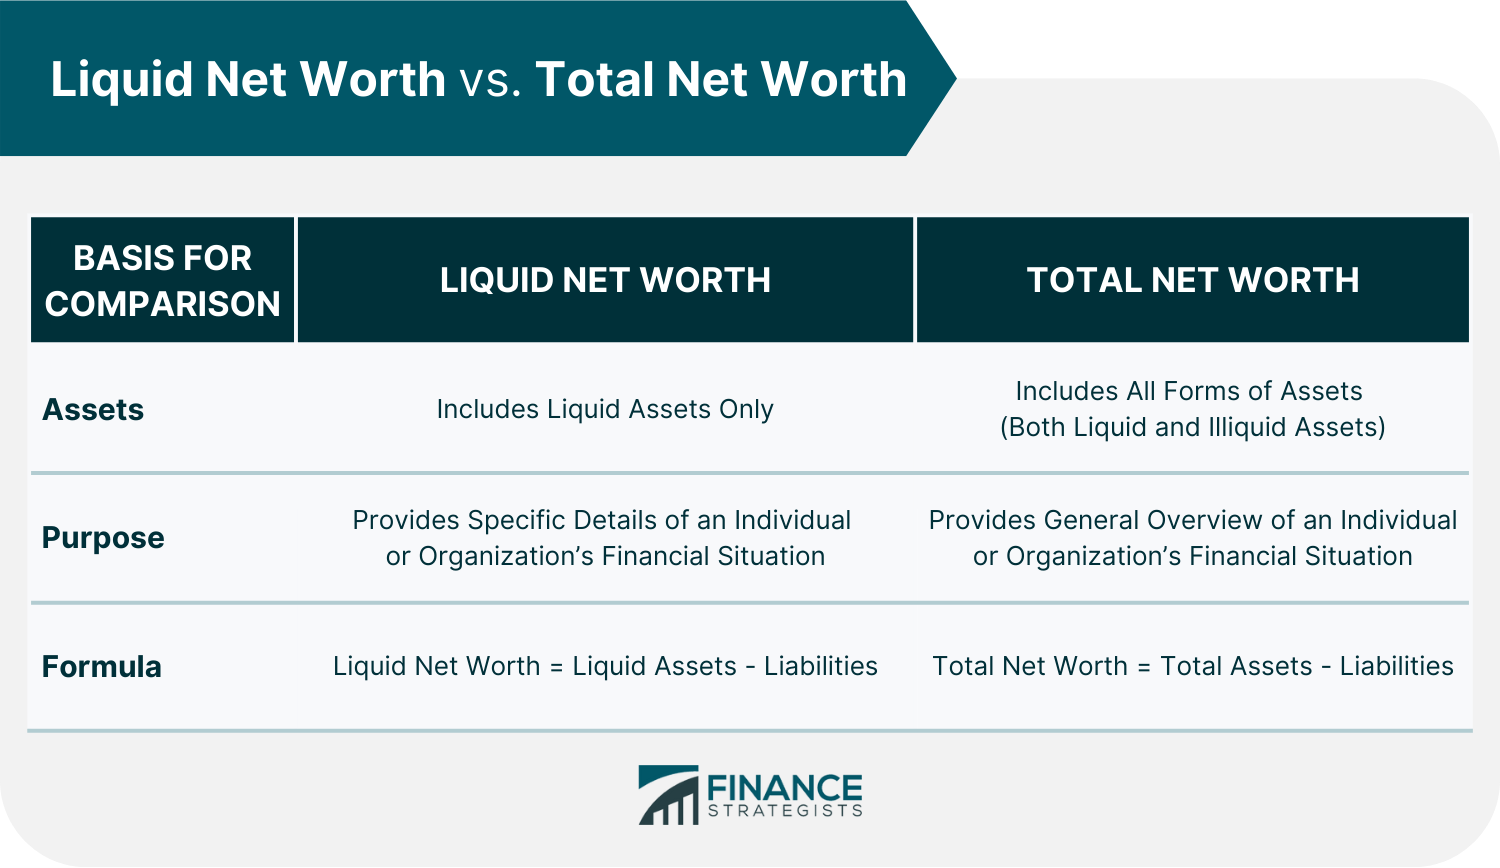
But here’s the kicker: your net worth is often trapped. Your house is worth a fortune, but you can’t pay for groceries with a bathroom renovation. That’s where liquid net worth struts in—it’s the cash and assets you can turn into cold, hard money within a few days without wrecking their value.
Must Read
So, liquid net worth is your “run-and-grab-it” money. We’re talking checking accounts, savings accounts, stocks, bonds, and money market funds. Basically, anything you can sell or withdraw quickly and painlessly.
Why Does This Matter for Your Everyday Joy?
Imagine your net worth is a beautiful, frozen lake. It looks impressive, but you can’t drink it. Liquid net worth is the refreshing stream that flows right past your cabin—you can scoop it up, splash it on your face, and use it to pay for a spontaneous pizza party. Without liquidity, you’re rich on paper but stuck in quicksand when opportunity (or an emergency) knocks.
Here’s a little secret: a high net worth with low liquidity is like owning a five-star restaurant but only being allowed to eat the breadsticks. You feel wealthy, but your daily life doesn’t reflect it. That’s why tracking your liquid net worth gives you a truer sense of your financial flexibility—your ability to say “yes” to a last-minute trip or “no” to a stressful job without breaking a sweat.
The fun part? You get to play a game of “What’s my escape velocity?”—how quickly can you pivot if life throws a curveball? That’s not morbid; that’s empowering!
The Divorce of the Two Numbers
Let’s be real: your house is not a liquid asset. Your 401(k) is not liquid (without penalties, anyway). Your rare Beanie Baby collection? Cute, but not liquid—even if that one bear is worth $10,000. Liquid net worth ignores all that stuff and focuses purely on what you can deploy in a pinch.
 What Is Liquid Net Worth? - Self. Credit Builder.
For most of us, the gap between net worth and liquid net worth is like the difference between a marathon plan and a sprint plan. The marathon is about building long-term assets; the sprint is about having cash on hand for the unexpected—an AC that dies in July, a surprise dental bill, or a once-in-a-lifetime concert ticket that just popped up on resale.
So, which number should you obsess over? Both! But here’s the twist: your liquid net worth is what gives you peace of mind at 2 a.m. when your brain decides to calculate worst-case scenarios. Your total net worth is for the long game; your liquid net worth is for the here and now.
How to Make This More Fun (Yes, Really)
Start by calculating both numbers—just this once, do it with a glass of wine or a fancy coffee. Then, set a silly little goal, like “I want my liquid net worth to cover six months of ramen-and-rent.” Watch it grow, and celebrate small victories: every dollar you save in your emergency fund is a dollar your future self will high-five you for.
Don’t panic if your liquid number feels puny next to your net worth. Most people are house-rich and cash-poor, and that’s okay—it’s the normal state of adulting. The goal isn’t to have a mountain of cash sitting idle; it’s to slowly bridge the gap so you have options, freedom, and a little wiggle room to say “yes” to life.
And here’s the uplifting kicker: every single month, you can nudge that liquid number upward. Sell that clutter, automate a tiny transfer to savings, or negotiate a raise (yes, you can!). Your net worth might be a slow-growing oak tree, but your liquid net worth is the flowerbed you can actually enjoy today.
So go ahead, peek at both numbers with fresh eyes. Don’t judge yourself—just observe. Then, pat yourself on the back for even caring. Because understanding the difference isn’t just about math; it’s about designing a life where your money works for you, not the other way around. You’ve got this, and your future self is already grinning.