
Okay, let’s talk about net worth. It sounds like something a stuffy banker whispers behind a mahogany desk, right? But really, it’s just a fancy way of asking, “If you sold everything you own and paid off all your debts, how much cold, hard cash would you have left?”
Think of it as your financial report card, except instead of a letter grade, you get a number that can make you feel like a genius or a goblin hoarding pocket lint. And here’s the kicker: the number for the average American is a wild rollercoaster ride, not a straight line. Let’s dive into the messy, funny, and sometimes baffling world of U.S. net worth.
First, the big, shiny number. The average net worth of an American household is often quoted in the millions—like $1.06 million, according to recent data. But before you start sobbing into your ramen, remember that the average is a liar. It’s skewed by billionaires like Jeff Bezos floating by in their mega-yachts, dragging the number up with them.
Must Read
If you and I and Elon Musk are in a room, the average net worth is technically in the billions, but you and I are still broke. That’s why the median net worth is the real star of the show. This is the middle point—half of households have more, half have less. And that number is much humbler, sitting around $192,900. Still a nice chunk of change, but it’s not “buy an island” money.
The Age Game: When Does the Money Show Up?
Here’s a fun secret: your net worth is basically an old-age pension in disguise. In your twenties, you’re likely swimming in student loans and living off gas station sushi. Your net worth is probably negative, which is a polite way of saying “the bank owns your soul.”
But then, a magical thing happens—you get a job with a 401(k), and your net worth starts to creep up like a hesitant cat. By your 30s and 40s, you’ve got a house (with a mortgage, but still!) and maybe a retirement account that isn’t a total joke. The real fireworks, though, explode in your 60s and 70s. That’s when the median net worth peaks at over $400,000. You become a paper millionaire, not because you have cash, but because your house in a decent suburb is now worth triple what you paid for it.
So, if you’re under 35 and your net worth is a sad little negative number, relax. You’re not failing; you’re just in the “gathering supplies” phase of the video game of life.
The Equity Trap and Other Quirky Details
Here’s where it gets silly. A huge chunk of that median net worth is home equity. That means your net worth is largely tied up in a place you can’t eat and a roof you can’t sell without having to live in a van afterward. It’s like being rich in Monopoly money—technically valuable, but you can’t buy groceries with a bathroom.
Then you have the liquid folks—the ones with massive brokerage accounts. They’re the ones who actually feel rich. The rest of us are just “house rich, cash poor,” which is just a fancy way of saying “I have a nice couch but no money for takeout.”
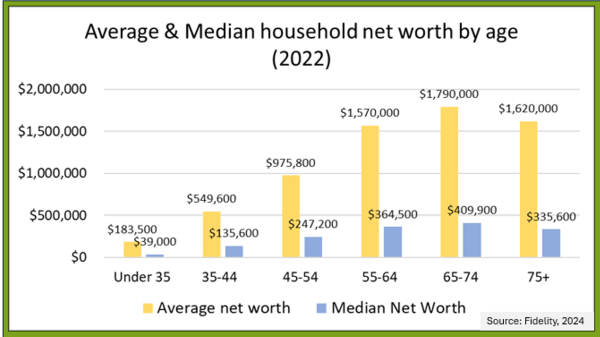 Chart and Comment: Average and Median Household Net Worth by Age — HOME
And let’s not forget the elephant in the room: student debt. This little gremlin sits on the shoulders of millions, dragging down their net worth like a depressed anchor. The average millennial spends their first decade of adulthood paying off the privilege of learning about the French Revolution. It’s not fair, but hey, at least our taste in music is good.
Race, Education, and the Grand Lottery
Now, let’s get honest for a second. Net worth isn’t just about hustle; it’s about history. The median net worth for white households is significantly higher than for Black and Hispanic households. This isn’t a personal failing—it’s decades of systemic stuff like redlining, unequal inheritance, and pay gaps. It’s a downer, but you can’t understand the numbers without knowing the real story.
Education also plays a huge role. A college degree can add a million dollars to your lifetime net worth, but so can starting a killer plumbing business. The moral? Skills matter more than titles. A welder who saves aggressively can out-earn a philosophy professor who spends like a drunken sailor. No offense to philosophers—I just know the welder has a better retirement party.
So, What’s the Takeaway?
Stop comparing yourself to the average—that’s comparing your hamster wheel to a rocket ship. Instead, focus on your own trajectory. If you’re paying off debt, you’re winning. If you’re maxing out a tiny 401(k), you’re winning. Net worth is a marathon, not a sprint, and the finish line is a comfortable retirement, not a yacht.
Here’s the uplifting truth: you have control over the next dollar you save. You can’t change the past, but you can absolutely tell tomorrow’s version of you, “Hey, let’s not buy that fifth latte.” It’s the little, boring choices that build the mansion, one brick of compound interest at a time.
So, what’s the final verdict on U.S. net worth? It’s a mixed bag of extreme wealth, stubborn poverty, and a whole lot of middle-class folks who are doing better than they think. Your worth is not your net worth. You are not the digits on a screen. You are the friend who laughs too loud, the person who dogsits for free, the human who brings snacks to parties. That’s an asset no spreadsheet can measure.
So go on, check your numbers if you must, but then close the app and go for a walk. Your net worth might be a work in progress, but your net joy is already off the charts. And honestly? That’s the only currency that truly matters.