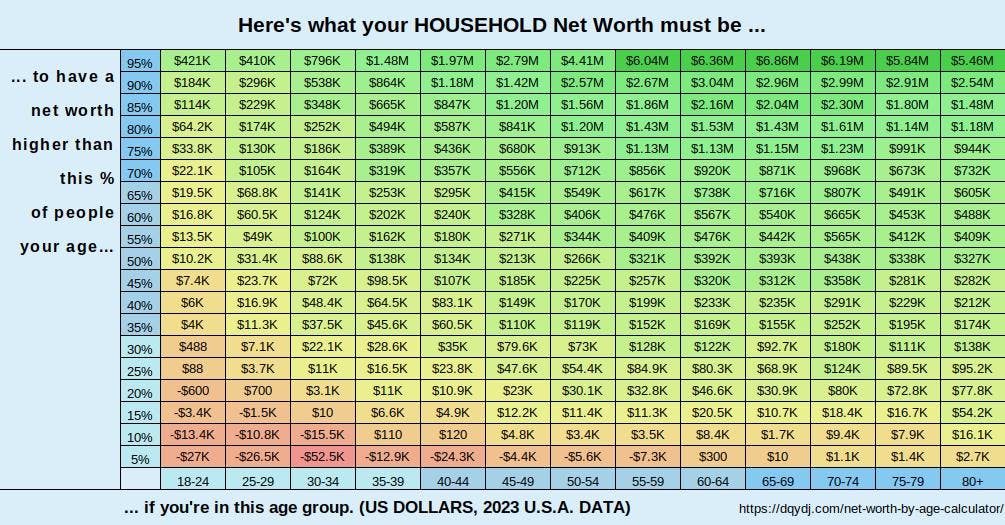
Let’s talk money. Not your paycheck, not your piggy bank—your net worth. That magical number that tells you what you’d have left if you sold everything and paid off all your debts.
And here’s the kicker: it changes dramatically by age. It’s like a financial rollercoaster, and we’re about to ride it together.
The 20s: Broke but Hopeful
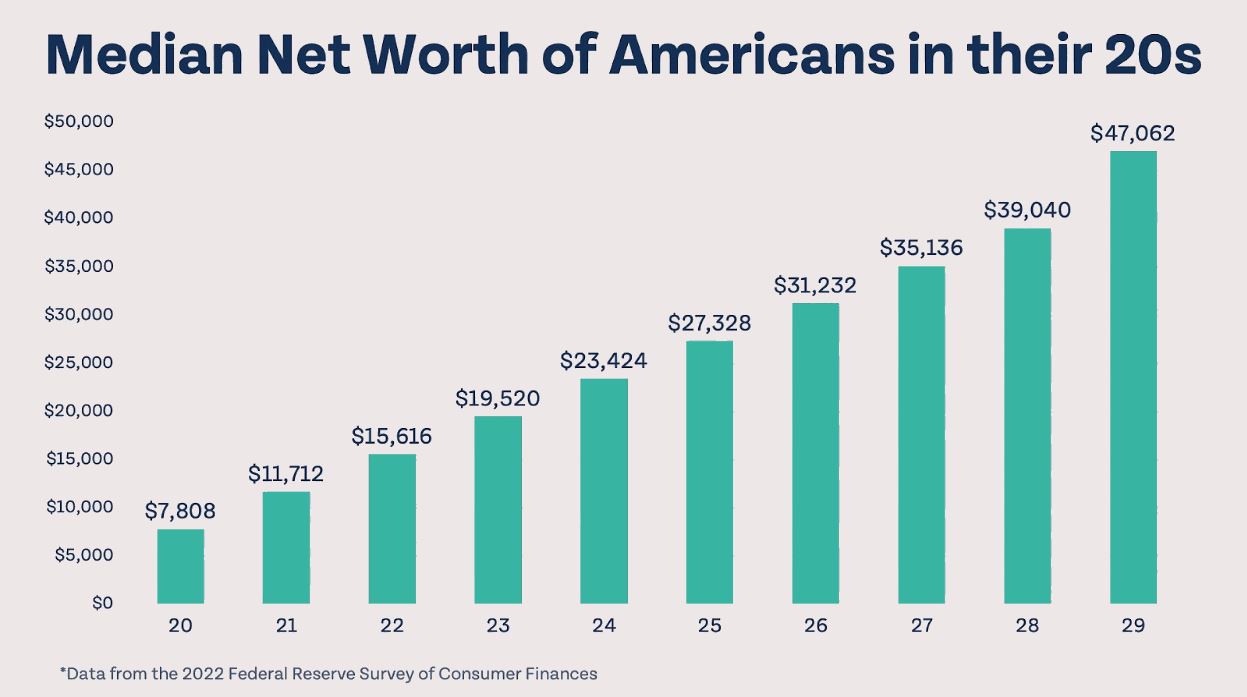
Ah, your twenties. The decade of ramen noodles, shared apartments, and “adulting” panic. The average net worth for Americans under 35 is around $14,000. That’s not a typo.
But the median? It’s a hilariously low $6,000. Why the gap? Because a few tech bros and trust-fund babies are dragging the average up, while the rest of us are just trying to afford avocado toast.
Fun fact: your biggest asset right now is probably your potential. Or that beat-up Honda Civic that somehow still runs.
The “Latte Factor” Is a Lie
Ignore the influencers who say skipping your morning coffee will make you a millionaire. In your twenties, the real problem is student loans and low wages, not a $4 latte.
But here’s the good news: time is your superpower. Even saving $50 a month now can snowball into something big later. Just don’t panic when your friend posts their “first home” on Instagram—it’s probably their parent’s basement.
Must Read
The 30s: The Squeeze
Welcome to your thirties, where life gets real. Weddings, babies, mortgages, and the sudden urge to buy a lawnmower. The average net worth for ages 35-44 jumps to $141,000, but the median is still a modest $35,000.
Why the gap? Because the top 10% are hoarding the fun. For most, this decade is about paying down debt while childcare eats your savings like a hungry goat.
Quirky fact: your net worth might actually drop in your early thirties if you buy a house. That down payment vanishes, and you’re suddenly rich in “illiquid assets” and poor in cash.
The 401(k) Temptation
You start staring at your retirement account like it’s a crystal ball. “Should I contribute more or buy a minivan?” Spoiler: the minivan won’t appreciate in value.
But this is the decade where compound interest starts flexing. Every dollar you save now is like planting a money tree. Just don’t expect it to sprout overnight—more like a decade.
The 40s-50s: Peak Earning, Peak Spending
This is the “sandwich generation” era. You’re paying for your kids’ college and your parents’ medical bills—simultaneously. Ouch. Average net worth for ages 45-54 skyrockets to $313,000, but the median? A more sobering $60,000.
Why the big jumps? Because this is when people finally pay off their own student loans and start making real money. Your salary peaks, but so does your life creep—that’s when you buy a boat because your neighbor did.
Funny but true: many people in their 50s have more equity in their house than in their bank account. You’re house-rich and cash-poor, which is a fancy way of saying “I can’t afford a new fridge.”
The “Late Starter” Redemption
If you’re behind, don’t cry into your retirement-age beer. The 50s are when you can legally shovel money into catch-up contributions. That’s $7,500 extra into your 401(k) each year.
It’s like the IRS finally gives you a cheat code. Use it or lose it, my friend.
 Average Net Worth By Age – How Americans Stack Up | Money Guy
The 60s and Beyond: The Big Reveal
Here’s the punchline. For ages 65 and up, the average net worth is a whopping $1.1 million. But don’t book a yacht yet—the median is just $200,000.
That means half of retirees have less than $200K to their name. Yikes. But the other half? They’re sitting pretty, and their secret is usually a pension or a paid-off house.
Quirky fact: your net worth often peaks at age 72. Why? Because you finally stop sending money to your kids, and your Social Security kicks in. It’s the golden years of compound interest doing the cha-cha.
The Boomer Secret Weapon
Retirees love to say “it’s not what you make, it’s what you keep.” They’re right. The average millionaire in this age group drives a used Toyota, not a Porsche.
And here’s the kicker—they got rich by avoiding dumb debt and holding onto index funds. Boring, but effective.
Why This Is Fun (Really)
Net worth by age is like a report card for your life, but with less shame and more math. It’s fascinating to see where you stack up against your peers, but remember: comparison is the thief of joy.
Some people have negative net worth (yep, that’s real), while others are drowning in cash. The goal isn’t to beat the neighbor—it’s to beat your own past self.
And the best news? You can change your number today. Pay off a small debt, or skip that impulse buy. Boom, your net worth just went up.
Your Action Plan
If you’re in your 20s, stop stressing. If you’re in your 50s, stop panicking. Every decade has its quirks, but the math is always on your side—if you start.
So go check your bank account. Laugh, cry, or shrug. Then make a tiny move to level up. Because the coolest part about net worth? It’s not destiny. It’s a story you’re still writing.
Now go be rich in your own weird, wonderful way.