Let’s talk about money. But not the boring kind. The kind where you obsessively refresh a calculator at 2 AM to see how you stack up against your neighbors, your high school bully, and that guy from college who definitely overpays for avocado toast.
We’re diving into the wild world of net worth percentiles by age. It sounds like a spreadsheet nightmare, but trust me, it’s a rollercoaster of ego, panic, and weird societal flexes. Buckle up, because this is more entertaining than your group chat right now.
The Big, Scary Number
First, the math. Your net worth is simply everything you own (cash, stocks, that dusty Beanie Baby collection) minus everything you owe (student loans, mortgages, that IOU to your buddy). That’s it. No wizardry required.
Must Read
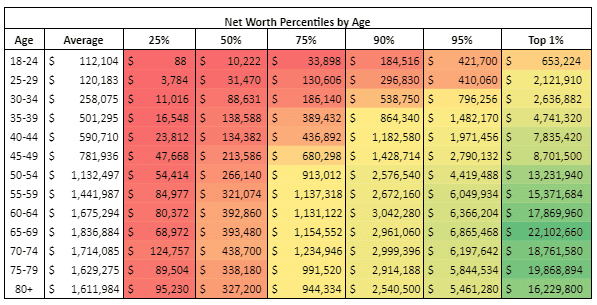
Now, the fun part: comparing it to other people. The data crunchers at the Federal Reserve and sites like DQYDJ have sliced and diced this into neat little “percentile” buckets. Being in the 50th percentile means you’re smack in the middle. Being in the 90th means you’re basically a money wizard.
Here’s the kicker: being “average” is shockingly low. You don’t need to be a tech bro to hit the middle. You just need to stop buying $7 lattes. (Okay, that’s a lie, but it feels good to say).
Your 20s: The Hunger Games
In your 20s, the median net worth is a hilarious joke. We’re talking around $6,000 to $10,000. Most of that is just your emergency fund and maybe a Roth IRA that you started after a panic binge on YouTube.
But here’s the twist: the top 10% of 20-somethings are already rocking $200,000 or more. Who are these people? They’re either living with their parents rent-free (smart move!) or they invented an app that sends you reminders to drink water. Honestly, good for them.
Don’t freak out if you’re at zero. Being broke in your 20s is a rite of passage. It’s the only time you can eat ramen for dinner and call it “minimalist living” without judgment.
Your 30s: The Awkward Middle Ground
Ah, your 30s. This is where things get weird. The median net worth finally breaks the $40,000 to $50,000 mark. But the spread is insane. Some of your friends are buying houses; others are still paying for the wedding they had in 2019.
Here’s the quirky fact: if you’re in the 75th percentile at age 35, you’re looking at around $280,000. That’s the “I have a 401(k) and a sensible sedan” zone. But the top 1% in their 30s? They’ve already crossed the $1.3 million line. That’s not just “doing okay.” That’s “I can buy a small island and name it after my cat.”
Pro tip: Don’t compare your “behind” to someone’s “highlight reel.” That girl from high school isn’t posting her credit card debt on Instagram. She’s just posting the new couch. Same energy.
Your 40s: The Mid-Life Pivot
Your 40s are where the numbers start to get chunky. The median net worth jumps to around $135,000. But don’t clap yet, because the average is way higher, like $900,000. That’s the classic “one billionaire in the room ruins the average” effect.
Funny detail: A lot of your wealth at this age is home equity. You bought a place in 2016 for peanuts, and now it’s worth a fortune. You didn’t become a genius; you just got lucky with interest rates. That’s okay. Luck counts too.
 The Net Worth Of The Average American: Net Worth By Age - Crushing REI
If you’re in the 90th percentile here, you’re pushing $1.9 million. You’re not rich-rich, but you can definitely afford a boat. A used one, sure. But a boat nonetheless.
Your 50s & 60s: The Finish Line (Or the Cliff)
By your 50s, the median net worth hits $250,000, but the 90th percentile is a wild $3.4 million. And in your 60s, the top 10% are sitting on $4.5 million plus. That’s not just “retirement.” That’s “I can afford to buy a fancy coffee and a muffin without checking my balance.”
Here’s the hilarious trap: Most people think they need $5 million to retire. But the median retiree is living on less than $1 million total. They’re fine. They clip coupons. They eat early bird specials. They’re happy, dammit.
The real secret to these numbers? Time in the market beats timing the market. And also, don’t get divorced. Seriously. Divorce is the single fastest way to blow up your percentile ranking. It’s the financial equivalent of throwing your phone in a lake.
Why This Is Actually Fun
Why do we love these charts? Because they’re a yardstick for our secret fears. We want to know if we’re winning at the game of life. And the answer is always, “Well, it depends on who you ask.”
You could be in the top 10% of your small town but bottom 50% in San Francisco. One of my favorite facts: In New York City, a $1 million net worth makes you “lower middle class.” But in rural Ohio, that makes you a Rockefeller.
So, next time you’re feeling poor, just remember: Someone with $10 million is still stressed about their taxes. It never ends. The goalposts move.
The Takeaway (No Judgment)
Stop obsessing over the 99th percentile. It’s mostly old people with land and stock options. Instead, just try to be better than past you. Did you save $100 this month? Win.
And if you’re in the bottom 25%? So what. Percentiles are just snapshots. They don’t show your future raises, your side hustle, or that garage sale you’re planning. You’re a work in progress.
Now, go check your account balance. But do it with a smile. Because at least you’re not paying for storage fees on a boat you never use. That’s the real wealth, folks.