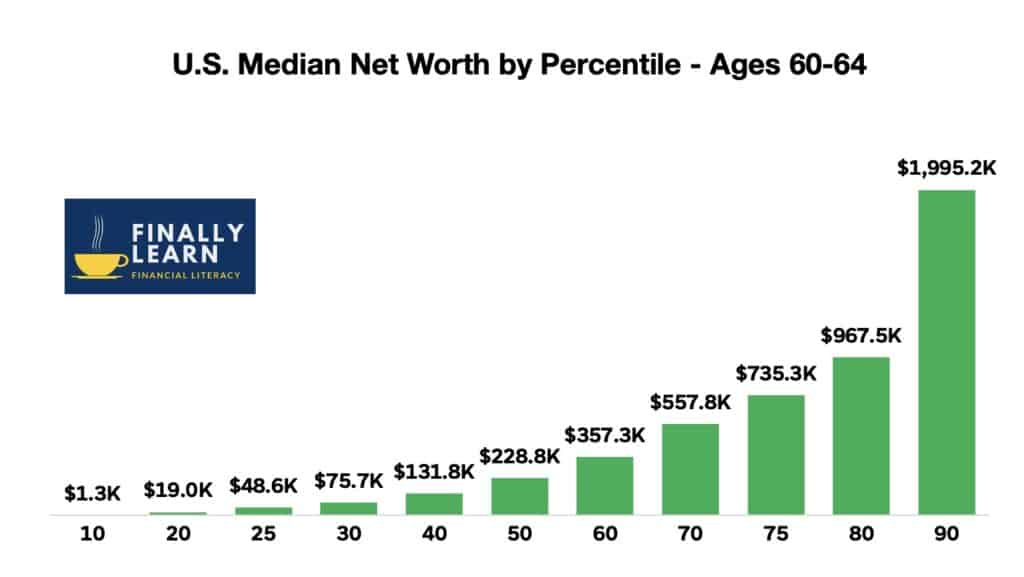
Okay, let’s talk about the big, scary number. You know the one—the “net worth to retire at 60” figure that keeps you up at night, staring at the ceiling. Deep breaths. We’re going to crunch this together, but we’re doing it with coffee, not calculators.
The Magic Number (Spoiler: It’s Not Magic)
First, let’s ditch the idea that there’s a single, universal dollar amount. You won’t find it etched on a golden tablet somewhere. Your number is as unique as your weird hobby of collecting vintage bottle caps.
That said, financial nerds love a good rule of thumb. The classic one? Aim for 25 to 30 times your annual expenses by age 60. If you spend $60,000 a year, you’re looking at $1.5 million to $1.8 million. That’s the “4% rule” in action—you withdraw 4% yearly, and hopefully, your money outlives you.
Must Read
But wait! Don’t panic if that number feels like a distant planet. It’s a starting point, not a verdict.
What’s Actually in Your “Net Worth” Bucket?
Here’s where it gets fun. Net worth isn’t just your checking account. It’s everything—your house, your 401(k), that dusty IRA, even the equity in your ’57 Chevy. Yes, really.
But here’s the catch: your house isn’t a sandwich. You can’t eat your walls unless you sell them and downsize. So, separate “liquid” wealth (cash, stocks) from “illiquid” stuff (real estate). You need the liquid stuff to pay for groceries.
Also, don’t forget Social Security. It’s not a fortune, but it’s a solid base. At 60, you might wait until 67 to get the full check, or take a reduced one at 62. That’s a whole other coffee chat.
The “Gap” Nobody Talks About
Here’s the sneaky problem: health insurance. If you retire at 60, you’ve got five years of private insurance before Medicare kicks in at 65. And private insurance is like buying a used car—expensive and full of hidden fees.
So, add a million-dollar cushion just for premiums and copays? Okay, that’s an exaggeration, but $20,000 to $30,000 per year for a couple isn’t crazy. Budget for it, or you’ll be eating ramen with a side of regret.
Another gap? Inflation. A $60,000 lifestyle today will cost about $80,000 in ten years. That’s not a scare tactic; that’s just math being a jerk.
How to Actually Get There (Without Selling a Kidney)
If you’re 50 reading this, you still have a decade. That’s ten full years of compound interest working its slow, boring magic. Max out that 401(k) catch-up contribution—it’s an extra $7,500 a year if you’re 50 or older. That’s not chump change.
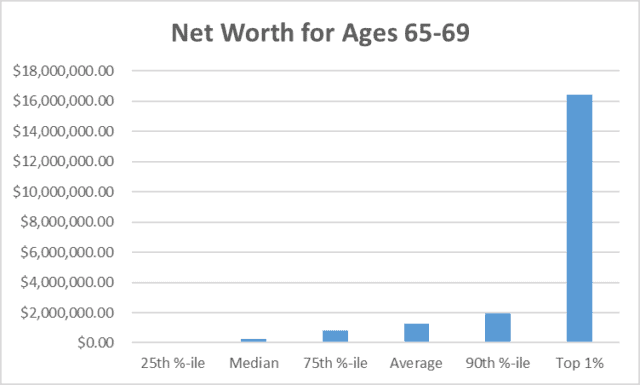 How Does Net Worth Actually Develop Over a Lifetime? - Wealthtender
Also, consider delaying the retirement party. Working until 62 instead of 60 adds two more years of savings and shrinks your withdrawal years. Two years. Big deal. It’s like waiting for your coffee to cool instead of burning your tongue.
And for the love of all things holy, pay off your debt before you retire. A mortgage at 60 is a boat anchor. Kill that thing, or at least shrink it to a rowboat.
What If You’re Not There? (Relax)
Let’s say you’ve only got $200,000 saved. Is retirement dead? No, but your expectations need a makeover. You might need to work part-time at a bookstore or become a “consultant.” That’s not failure; that’s a lifestyle.
You can also move to a cheaper city. Your money goes twice as far in Tulsa than in San Francisco. Plus, Tulsa has better pie. I’ve checked.
Remember, the “net worth to retire at 60” is a moving target. It changes with the stock market, your health, and whether your kids actually move out. Ha.
The Final, Honest Truth
Stop comparing yourself to your neighbor with the boat. You don’t know their credit card debt. You only need enough to cover your specific, unglamorous, beautiful life.
So, take a deep breath. Write down your spending for a month. Multiply by 25. Then, don’t cry. Just start cutting little things—like that daily $7 latte. That latte is $2,500 a year. Over ten years, that’s a solid chunk of your “magic number.”
Retiring at 60 isn’t about a perfect score. It’s about flexibility. If you can cover your basics, you can handle anything. And if you fall short? Maybe you work three days a week at a golf course. Free golf, my friend. That’s not retirement. That’s winning.
Now, pass the creamer. We’ve got a plan to doodle on a napkin.