
Okay, let’s have a real chat about money. You know, the kind of money that makes you do a double-take at your bank app. We’re talking about that elusive club: the top 5% of earners and net worth holders in the US.
First, let’s get the awkward numbers out of the way. To be in the top 5% by net worth, you need roughly $1.4 million in total assets (house, investments, cash) minus any debts. That’s not a typo—it’s a million with a “b” sound, but only one “m” in the middle.
Now, before you panic and check your 401(k) for the fifth time today, breathe. This isn’t about your daily latte habit. It’s about the whole enchilada—your house equity, that weird stock your uncle recommended, and yes, even that dusty coin collection in your sock drawer.
Must Read
What That Actually Looks Like
Picture this: You own a modest three-bedroom home in a decent suburb, fully paid off. You’ve got $300k in retirement accounts, a sturdy emergency fund, and a paid-off Honda that still runs like a champ.
Congratulations, friend—you might already be closer to that top 5% than you think. The secret isn’t a Silicon Valley IPO; it’s stubborn consistency. Most people in this bracket didn’t win the lottery; they just outlasted their own bad decisions.
Here’s the kicker: the top 5% isn’t all private jets and caviar breakfasts. Honestly, it’s a lot of middle-aged folks in Costco sneakers arguing about lawn fertilizer. The real flex is not having a panic attack when your furnace dies.
The Big Misconception
We tend to imagine the top 5% as tech billionaires or trust-fund kids with questionable facial hair. Nope. Most are doctors, engineers, small business owners, and even some very savvy school teachers who bought index funds in the 90s.
They didn’t get there by timing the market or flipping crypto. They got there by not buying the new truck every three years and letting compound interest do the heavy lifting. Boring, right? But so is watching paint dry, and that works too.
Let’s talk about the income side for a second. Top 5% by income is a different beast—that’s around $350,000 a year or more. But income is fickle; net worth is the real muscle. You can earn a fortune and still be broke if you spend like a Kardashian on a bender.
Where the Money Hides
Here’s a fun secret: a huge chunk of that top-5% net worth is illiquid. It’s locked up in a business, real estate, or retirement accounts you can’t touch without a penalty. So they’re “rich” on paper, but they still clip coupons for paper towels.
That means the guy next door with the boat might be drowning in debt, while the quiet woman in the Prius is quietly sitting on $2 million. The math doesn’t care about appearances.
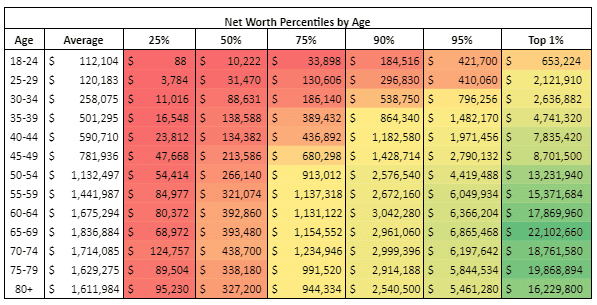 Us Wealth Percentiles By Age – Net Worth By Age Calculator – KNAD
Another fun fact: to stay in the top 5%, you don’t need to be a genius. You need to avoid divorce, lawsuits, and get-rich-quick schemes. That’s it. That’s the whole plan. Boring is the new baller.
How to Join (Without Selling a Kidney)
Start with the boring stuff: automate your savings. Pay yourself first, even if it’s just $50 a month. Then, when you get a raise, don’t upgrade your lifestyle. Upgrade your net worth instead.
Buy a reasonable house you can actually afford. Drive your car into the ground. Cook at home more often than you order out. It’s not sexy, but neither is being broke at 65, so pick your poison.
And for the love of all things holy, max out that retirement account. The tax advantages alone are like getting a pay raise from the universe. Future you will send you a fruit basket, I promise.
Now, a reality check: the top 5% isn’t the finish line. It’s a moving goalpost that inflates every year. But here’s the beautiful thing—once you hit a certain net worth, the stress drops off a cliff. You sleep better, you smile more, and you laugh at the word “overdraft.”
But here’s the real tea: you don’t need that status to be happy. I’ve met folks in the top 1% who are miserable, and people with $50k net worth who are radiantly joyful. Money is a tool, not a personality.
So, what’s the takeaway? Chase financial security, not a vanity metric. The top 5% is a nice bragging right for cocktail parties, but the real jackpot is peace of mind, freedom to say “no” to bad jobs, and the ability to help your loved ones without breaking a sweat.
And hey, if you’re reading this and your net worth is currently $1,200—you’re doing fine. Every millionaire started with a dollar and a dream (or at least a 401(k) match). The goal isn’t to out-earn your neighbors; it’s to out-live your financial worries.
So go stretch your legs, smile at your bank account (even if it’s small), and remember: the top 5% is just a number. The top 100% of being a decent human? That’s free, and you’re already there. Now go buy yourself a cheap ice cream cone—you’ve earned it.