Let’s be honest: “net worth” has become the unofficial currency of the group chat. It’s the number you secretly compute after a friend mentions their stock options, and the stat that makes you feel like a tycoon when your 401(k) ticks upward. But here’s the kicker—your net worth is a bit like a movie star’s Instagram. It looks spectacular, but it doesn’t tell you what’s actually happening behind the scenes.
That’s where liquid net worth swaggers in, wearing sunglasses and holding a cold brew. If net worth is the total value of everything you own, liquid net worth is the portion you could actually spend by next Tuesday without selling a kidney or waiting for escrow to close. Think of it as the difference between owning a vineyard and having cash for a glass of wine.
The Glamorous (and Slightly Deceptive) World of Total Net Worth
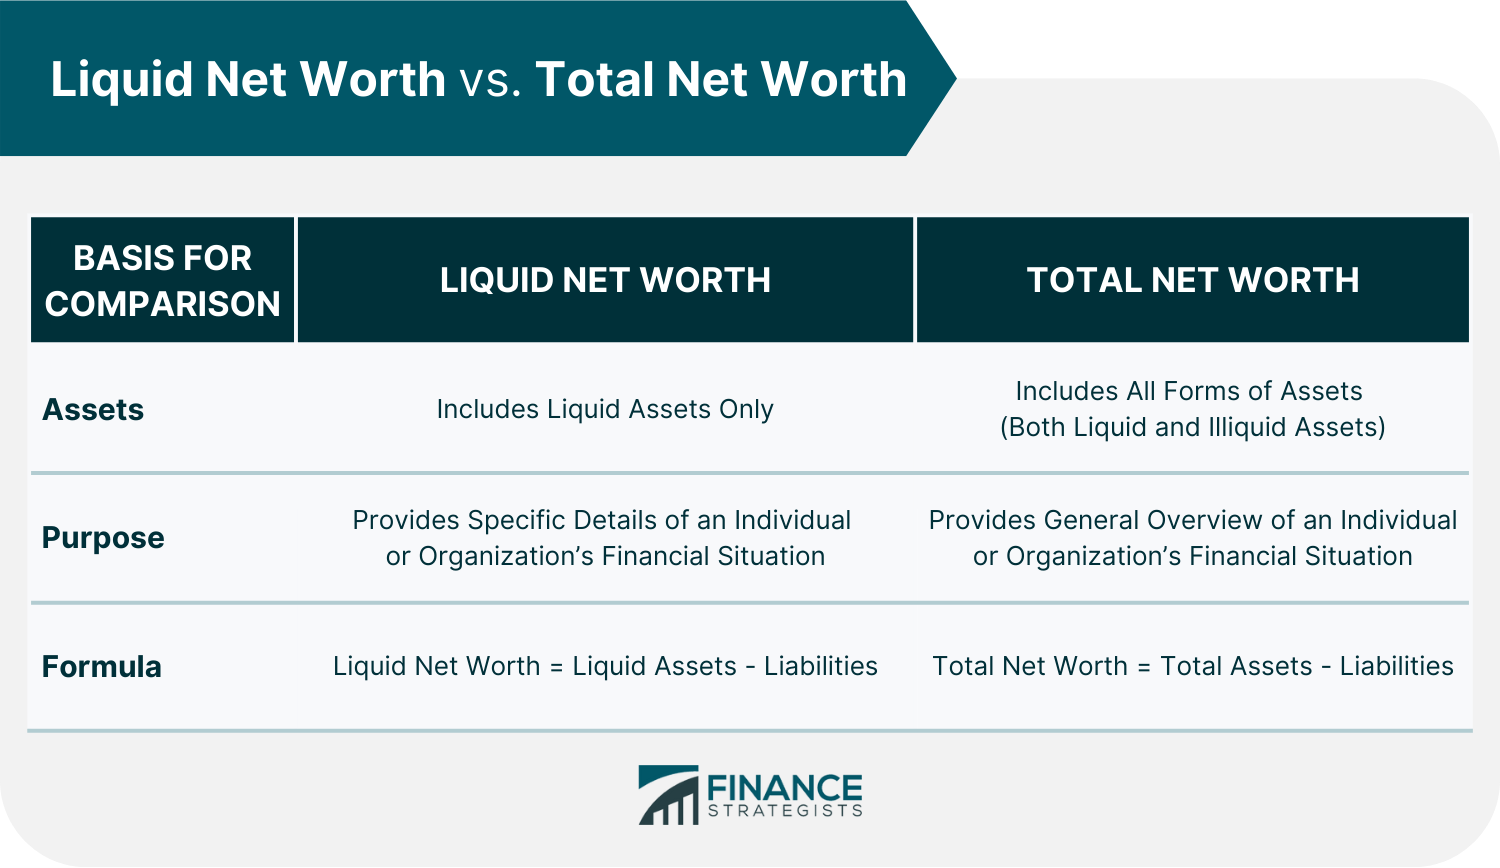
Your total net worth is a simple math equation: everything you own (assets) minus everything you owe (liabilities). That includes your home, your car, that vintage guitar you swear you’ll learn to play, and your retirement accounts—even the ones you can’t touch without a tax penalty and a sad trombone sound.
Must Read
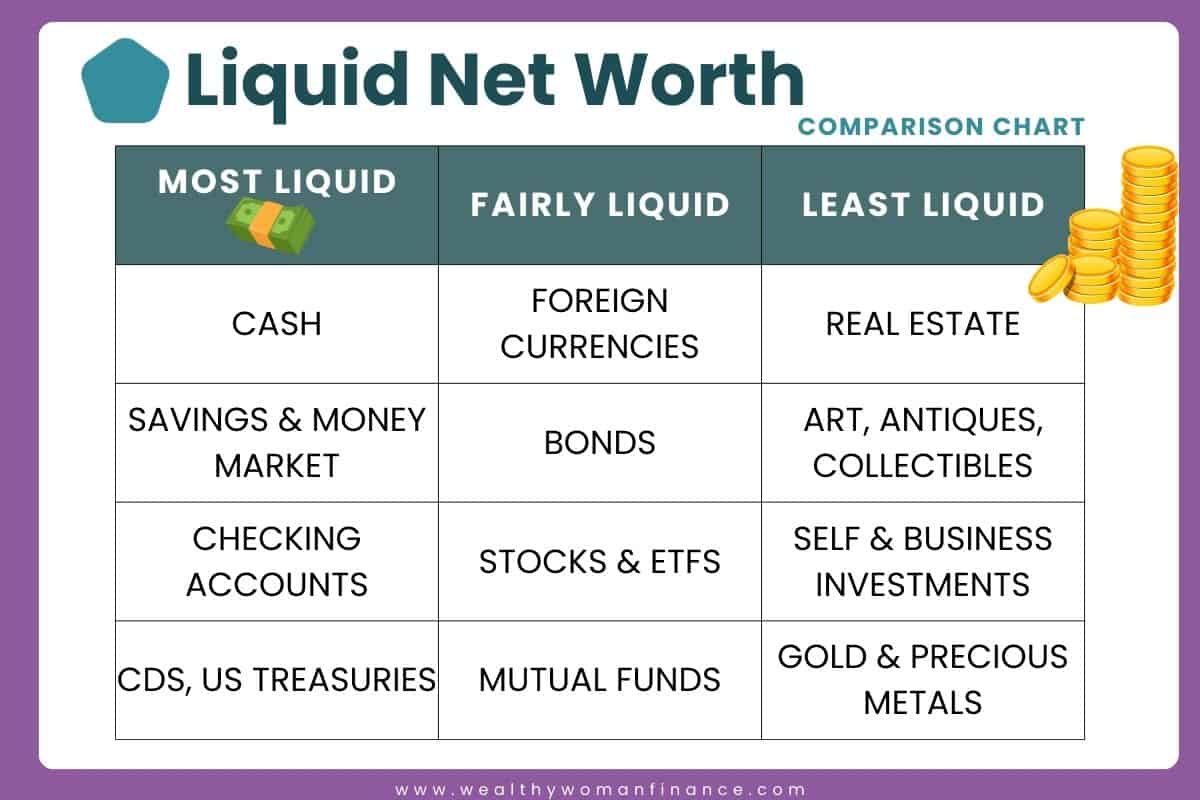
It’s the number that financial advisors love to throw around, and it’s genuinely useful for tracking long-term progress. But here’s the sneaky part: a huge chunk of your net worth might be illiquid. Your house is an asset, sure, but you’re not going to sell it to pay for brunch. Your 401(k) is fantastic for future you, but current you will face a 10% penalty if you dip in early. That’s not flexibility; that’s a financial straightjacket.
Remember the 2008 housing crash? Plenty of people had impressive net worths on paper—until their homes dropped 30% in value and their “wealth” evaporated overnight. Illiquid assets are only as solid as the market’s mood on any given day.
Why Liquid Net Worth Is the Cool, Calm Cousin
Liquid net worth is the cash and cash-equivalents you can access within a few days without penalties or a garage sale. We’re talking checking accounts, savings accounts, money market funds, and maybe some stocks or bonds you can sell with a tap on your phone. It’s the money that says “yes” when opportunity knocks—or when your car makes a weird noise.
Think of it like this: total net worth is the size of your swimming pool. Liquid net worth is the water actually in it. A giant concrete hole looks impressive, but you can’t do a cannonball into an empty pit. Liquidity is your freedom juice, and it’s what separates the “wealthy” from the “wealthy-until-they-need-cash.”
This is why financial gurus often say, “Cash is king.” But let’s be real—it’s more like cash is the royal advisor who actually gets things done.
The Art of Not Being “House Poor” (or “Stock Poor”)
You know that friend who lives in a stunning downtown loft but eats instant noodles and panics at a $40 dinner bill? They’re likely suffering from low liquid net worth. Their money is tied up in a down payment and furniture, leaving them with a beautiful cage and no birdseed.
On the flip side, consider the software engineer who drives a 2012 Honda and rents a modest apartment. Their net worth might be lower than the loft owner’s, but their liquid net worth is stacked. When a startup opportunity comes knocking or a market crash offers bargain stocks, they have the dry powder to act. That’s not boring; that’s power.
 What Are Non Liquid Assets at Carl Moran blog
Here’s a fun fact: Jeff Bezos’s net worth is massive, but his liquid net worth is a fraction of it because it’s mostly Amazon stock. If he wanted to buy a small country tomorrow, he’d have to sell shares, deal with SEC rules, and possibly tank the stock. Even billionaires face the liquidity trap—it’s just a fancier trap with better views.
Practical Tips to Boost Your Liquid Wealth (Without Sacrificing Your Netflix)
First, get to know your liquidity ratio—that’s your liquid assets divided by your total net worth. A healthy benchmark? Anything above 15% to 20% gives you breathing room. If you’re sitting at 5%, don’t panic; just start shifting gears.
Start small: create a “freedom fund” separate from your emergency fund. This is money for opportunities, not just disasters. Next, consider a high-yield savings account—it’s basically a checking account that pays you for your patience. And finally, review your investments. If you’re over-leveraged in real estate or a single stock, consider trimming a bit to build your cash stash.
One more tip: automate a “liquidity transfer” each month, just like you automate your retirement contributions. Even $100 shifted from your checking account to a liquid investment adds up—and it makes you feel oddly adult.
The Daily Life Connection
Here’s the reflection part. Your net worth is your report card for the decade; your liquid net worth is your ability to change your plans this weekend. That trip to Lisbon? That’s liquidity. That career break to start a bakery? That’s liquidity. The peace of mind when your landlord raises rent? You guessed it—liquidity.
So, while you should absolutely admire your total net worth’s growth over time, don’t fall in love with a number you can’t touch. Water your financial garden, but always keep a pitcher of cash ready to pour. Because in the end, wealth isn’t just about what you own—it’s about the options you can actually afford to take.
Now, go check your savings balance. And maybe sell that vintage guitar—you’re never going to learn it anyway.