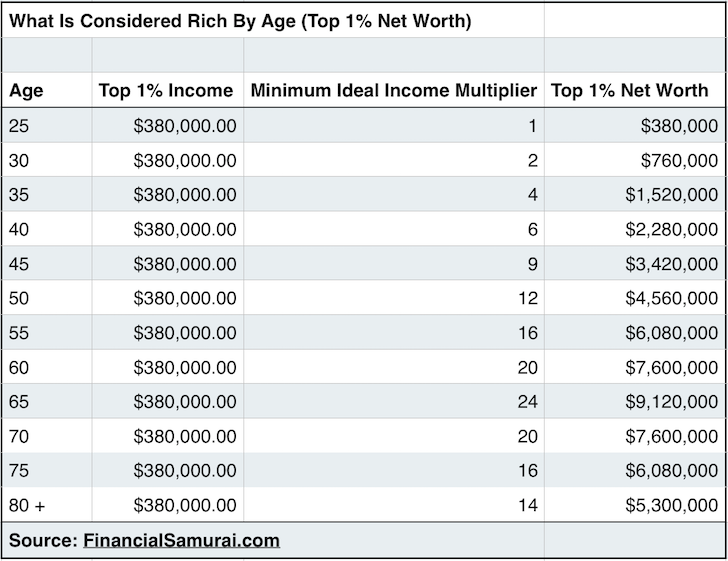
Let’s be real for a second: we’ve all googled “average net worth by age” at 2 a.m., clutching a lukewarm coffee and a sliver of hope. The results usually make you feel either wildly ahead or painfully behind, with very little wiggle room for nuance. But today, we’re not talking about the average—we’re talking about the top 1%, the financial Mount Everest that looms over the rest of us.
Here’s the kicker: the number isn’t just one big, scary figure. It shifts dramatically depending on whether you’re 30, 45, or pushing 60. And spoiler alert—the path to that exclusive club isn’t always what you’d expect. It’s less about a single lucky lottery ticket and more about a slow, steady grind with a few clever twists.
The 30-Something Story: Swinging for the Fences
If you’re in your early 30s and wondering where you stand, the top 1% net worth bar is around $1.1 million to $1.5 million, depending on which data set you peek at. That might sound like Monopoly money, but think about it—this group isn't just saving; they’re often founders, startup early employees, or folks who got into real estate right before the boom.
Must Read
They’re the ones who took a calculated swing while their peers were streaming aggressively and calling it “self-care.” The fun fact? Many of them didn’t get there on salary alone—they built assets that work while they sleep. Think rental income, index funds on autopilot, and a side hustle that quietly turned into a business.
Practical tip: Don’t chase a dollar amount; chase a system. Automate your investments, keep your overhead low, and treat your skills like a stock portfolio—always diversifying.
Mid-Life Peak: The 40s and 50s Powerhouse
Now, fast-forward to your mid-40s to mid-50s. Here, the top 1% jumps to a hefty $7.5 million to $10 million. This is the decade of compounded returns, where the market does its best magic trick—turning fifteen years of boring contributions into a genuinely impressive pile of cash.
This group is often full of senior executives, serial entrepreneurs, and doctors who actually practiced what they preached. They didn’t get here by timing the market; they got here by staying in the game, even through the 2008 crash and the pandemic yo-yo effect.
Culturally, this is the “Ferrari tax bracket,” but usually, they’re driving a ten-year-old Honda. It’s a classic paradox: wealth at this level often looks boring on the outside. The real luxury is freedom, not labels.
Quick fun fact: Studies show that most millionaires in this age group live in homes worth under $400,000. They upgrade their balance sheet, not their curb appeal.
The Retirement Ritz: 60+ and Beyond
By the time you hit your 60s, the top 1% net worth balloons to around $11 million to $20 million. This is where inheritance, decades of asset appreciation, and the beauty of zero new expenses come into play. Your mortgage is paid, your kids are (hopefully) launched, and your savings are a snowball rolling downhill.
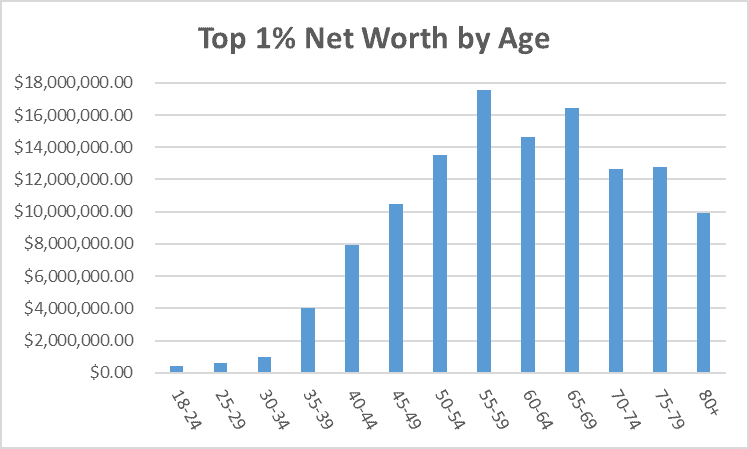 1% Net Worth By Age – Net Worth By Age – ULVV
But here’s the twist—this demographic isn’t just sitting on cash. They’re often big into philanthropy, art, or that niche hobby they never had time for. The net worth number is less about buying things and more about legacy building.
Fun fact: A lot of this wealth is tied up in business equity or real estate, not checking accounts. You could be a paper millionaire with almost no liquid cash, and that’s perfectly normal.
What the Numbers Don’t Tell You
Here’s the uncomfortable truth: these benchmarks are moving targets, and they’re heavily skewed by location and industry. A top 1% earner in San Francisco is living a very different life than one in Boise, Idaho, even if the decimal points look the same.
So, what’s the practical takeaway? Stop comparing your chapter one to someone else’s chapter twelve. The real metric of financial health isn’t beating the top 1%—it’s having a margin of error that lets you sleep well on a Tuesday night.
If you’re 35 with $50,000 saved, you’re not "behind" in any meaningful sense; you’re just early in a different curve. The secret sauce is consistency over intensity, and that’s available to everyone, not just the elite few.
The Reflection: Your Own Top 1%
At the end of the day, net worth is just a scoreboard. It doesn’t measure your health, your laugh, or the good you put into the world. The person with $20 million might still wake up with anxiety, while the barista who owns her co-op outright might feel like a queen.
So, maybe the goal isn’t to join the “top 1%” by age—it’s to build a life that feels rich by your own definition. Save fiercely, invest practically, but leave room for a spontaneous road trip or a silly, overpriced coffee.
Because true wealth, friend, is having the option to say no when something doesn’t serve you. And that, luckily, doesn’t require a seven-figure bank account—just a little planning and a lot of self-awareness. Now, go enjoy the ride; your future self is already rooting for you.