
Honestly, money goals feel like one of those things we just… avoid, right? We scroll past the flashy lifestyle posts and then quietly wonder, "Am I behind?" Well, grab your coffee, because we're going to break down the top net worth benchmarks by age — zero judgment, I promise.
These aren't set in stone, of course. They're more like helpful little signposts that say, "Hey, you're on track!" or "Okay, we might need a strategy tweak."
Under 25: The "I Just Started" Phase
At this age, most people are juggling student loans, first jobs, or maybe an internship that pays in experience… and instant ramen. A solid net worth here is usually anywhere from $0 to $5,000. That might sound underwhelming, but think about it — you're building habits, not empires yet.
Must Read
This is the perfect time to start an emergency fund, even if it's just $20 a paycheck. Seriously, do that now — future you will be absurdly grateful.
25–30: The "Am I Supposed to Be a Real Adult?" Phase
By your mid-to-late twenties, a healthy net worth target sits around $5,000 to $15,000. You've probably got a solo apartment, a questionable kitchen knife collection, and maybe your first real 401(k) contribution.
Debt — especially credit cards — is the biggest red flag here. Paying that down aggressively actually counts toward your net worth, so consider it a double win. Corny but true, right?
30–35: The "Things Should Be Clicking" Phase
By 30, benchmarks suggest you might aim for $50,000 to $100,000 in total net worth. Career momentum picks up, salaries improve, and you may even start thinking about homeownership. Keyword: thinking.
Investing early — even small amounts — makes a massive difference by this point. Compound interest is basically free money sleeping in your bank account waiting to wake up.
35–40: The "Competitive Comparison" Phase
Now we're talking $100,000 to $250,000. At this stage, retirement contributions should be consistent, and hopefully some of that money is invested rather than just sitting there looking pretty.
This is also when lifestyle creep starts sneaking up on people like a vending machine at midnight. More income ≠ you need a fancier car — do you really though?
40–45: The "Big Milestone" Years
A net worth of $400,000 to $600,000 puts you right in the comfort zone for your early forties. Equity from a home, retirement accounts, and decades of (hopefully consistent) saving are doing the heavy lifting. Not bad for someone who still debates whether cereal counts as dinner.
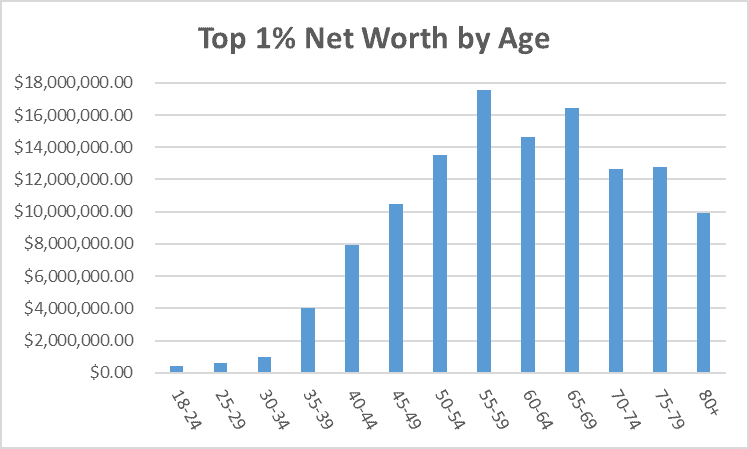 Median Net Worth _ Median: What It Is and How To Calculate It, With
At this point, you should have some diversification — stocks, bonds, retirement accounts, maybe a side income stream. If all your money lives in one place, that feels risky.
45–50: The "Peak Earning" Window
By your late forties, the benchmark climbs to $750,000 to $1 million. You're likely at the height of your career earning power, and the momentum from earlier investments really starts to show. This is where the math kind of sings.
I'd love to say everyone hits this comfortably, but honestly? It depends heavily on career, location, and whether you started early. Either way, staying consistent is everything.
50+: The "Retirement Radar" Phase
Once you cross 50, the typical top benchmark sits at $1 million to $2 million — and it should be growing fast. The goal here is shifting from pure accumulation to preservation and smart withdrawal planning. You don't want to run the marathon and trip on the finish line.
Accelerating retirement contributions at this stage is key. Catch-up provisions exist for a reason — use them shamelessly.
Wrapping It Up
Here's the real takeaway: these numbers are guidelines, not gospel. Everyone's path looks different — some start late, some take detours, some win the lottery (weird flex, but okay).
The best net worth move you can make right now? Start where you are. Stop comparing to someone else's highlight reel. Every dollar saved is a step forward, even if the step feels hilariously small at first.
So, refill that coffee. We're going to be fine.