Let’s be honest, most of us think the “Top 2 Percent” is a mythical creature, like a unicorn that drives a Tesla and complains about the lack of organic kale at the shareholders’ meeting. You picture them sipping overpriced coffee in a minimalist apartment, while you’re over here celebrating when your grocery bill comes in under $150. But the actual number to join this fancy club is probably way lower than you think, and that’s where the fun begins.
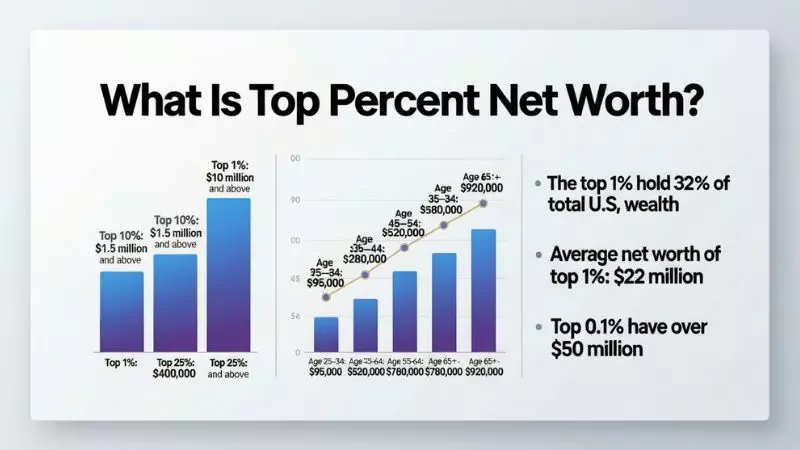
Depending on who’s counting, you need a net worth of around $2.4 million in the US to be in the top 2%. That’s not liquid millions in a checking account; it includes your home equity, your 401(k), your dusty coin collection, and that rusty bike you swear you’ll fix someday. So, basically, if you’re a couple in your late 50s who bought a house in the 90s and actually saved some cash, you might be accidentally elite.
The “Rich” Neighbor Who Eats Leftovers
The hilarious part is that this top 2% person isn’t sipping champagne on a yacht. They’re the neighbor who drives a 2012 Honda and brings Tupperware to the potluck, but their retirement account is a fortress. You might think they’re just frugal, but they’re actually playing a long game of financial chess while you’re playing checkers with a credit card.
Must Read
I remember meeting a guy at a BBQ who complained about the price of hot dog buns. We all rolled our eyes, thinking he was broke. Later, I found out his net worth was north of $3 million. He was in the top 2%, and he was mad that a four-pack of brioche buns cost seven bucks. It’s a real disconnect—they have the money, but they’ve tricked their brains into thinking a discount on paper towels is the ultimate thrill.
Why You’re Probably Closer Than You Think
If you’re in your 40s with a paid-off or half-paid house, a decent 401(k), and no crippling credit card debt, you’re probably swimming in the top 10% or 5% waters. The jump to 2% isn’t about winning the lottery; it’s about avoiding stupid taxes and letting your investments compound for a decade without touching them. It’s less about math and more about white-knuckling the urge to buy a boat every time you get a bonus.
The real kicker? The top 1% is where the big beasts live (think $10M+), and they don’t even know the top 2% exists. They’re too busy arguing about private jet fuel surcharges. But the 2% crowd is relatable—they still clip coupons, they still gasp at the price of a ribeye, and they definitely get excited when Costco has a sale on olive oil.
 What is the Average Net Worth by Age?
Anecdote Time: The “Almost” Rich
My buddy Mark is the perfect example. He’s a high school teacher with a side gig fixing appliances. His wife is a nurse. They don’t look rich—their couch has a permanent butt-shaped dent from 2007. But they bought a duplex in 1998, lived in one unit, rented the other, and stuffed money into index funds every single month. Last year, I did the math with him for fun, and he was shocked to discover he was in the top 2% for his age group. He laughed and said, “Great, now I can afford to replace the water heater with a tankless one.” That’s the spirit—the top 2% is just regular folks with an insane tolerance for delayed gratification.
So why does this matter for you? Because the dream isn’t about being a celebrity or a tech bro. It’s about hitting that quiet threshold where you can tell your boss to kick rocks and still pay your property taxes. It’s about that feeling of financial armor where a car breakdown is a minor annoyance, not a life crisis.
Next time you see a retiree in a faded flannel shirt arguing with a cashier over three cents, don’t pity them. That’s probably a top 2% net worth person making sure they stay in the club. They know that every penny they save today is another brick in their “I don’t have to deal with people” retirement wall.
And honestly, that’s the dream we can all nod to. It’s not about a flashy lifestyle; it’s about the peace of mind that comes from a spreadsheet that looks like it’s winning. While you’re out there checking your app for your paycheck, they’re checking their dividend calendar and smiling. The weirdest part? If you start saving aggressively today, you could be that weird old person in 30 years, hoarding your wealth while eating a sandwich from home. And trust me, that’s not a bad gig—it just comes with a side of judgement from your neighbors who think you’re broke. Let them talk.