
Last week, my buddy Mark—a perfectly normal, slightly balding accountant—told me he felt “behind.” He’d just read some report about the top 5 percent net worth by age, and now he was convinced his 401(k) was a cruel joke. I asked him what the magic number was for a 40-year-old, and he mumbled something about a million and a half while staring into his lukewarm coffee. I almost choked on my bagel, not because that’s a crazy number, but because Mark drives a 2012 Honda and I’ve seen his “fun budget” spreadsheet.
Here’s the thing: that “top 5 percent” club sounds like a secret society of hedge fund wizards, but the reality is way more mundane and, frankly, a little hilarious. It’s not about flashy cars or yachts; it’s about a boring, relentless grind of saving, investing, and avoiding stupid money mistakes. Let’s pull back the velvet rope and see who’s actually in this club, and why you’re probably closer than you think (or, at least, not as far behind as Mark feels).
The Holy Grail Numbers (And Why They Feel Random)
Okay, let’s rip the band-aid off. For a 30-year-old, being in the top 5 percent means a net worth of roughly $350,000 to $400,000. Yes, you read that right. A 30-year-old with a paid-off used Prius and a solid tech job could be there, which feels insane when your friends are brunching on avocado toast (no judgment, I love that toast). By 40, you’re looking at around $1.1 million to $1.5 million to crack that top 5 percent.
Must Read
But here’s the kicker—by 60, the bar jumps to a cool $2.5 million to $3 million. That’s the point where you realize that the “rich” person isn’t the one with the newest iPhone; it’s the one who didn’t buy a boat in their 40s. Honestly, these numbers are like a fever dream from the Federal Reserve, but they also reveal a dirty little secret: time in the market beats timing the market.
The irony? Most people in this bracket don’t feel rich. They see their house equity and their index funds, but they still clip coupons and freak out about a $400 car repair. That’s the disconnect—the top 5 percent is often just a bunch of anxious people who happen to have good savings habits.
Who’s Actually In This Club? (Spoiler: Not Who You Think)
You might picture a surgeon or a tech founder, but nope. The top 5 percent is disproportionately filled with dual-income households who are just… consistent. Think two teachers in their 50s who bought a house in 1998 and never moved. Or a mid-level manager at a utility company who maxed out their 401(k) for 30 years straight. It’s not sexy. It’s not exciting. It’s like watching grass grow, but the grass is made of compound interest.
And here’s a side comment for you: if you’re under 35, don’t panic if you’re at $5,000. The top 5 percent at 25 is mostly inherited wealth or people living in their parent’s basement while working at a bank. Seriously, one study showed that a huge chunk of young top-5-percenters got a down payment from mom and dad. So if you don’t have that, you’re playing on hard mode, and that’s okay.
What separates them from the rest of us? They don’t have a “lifestyle inflation” problem. When they get a raise, they don’t buy a luxury SUV; they bump up their automated transfer to Vanguard. It’s boring. It’s so, so boring. But boring money is good money, I promise.
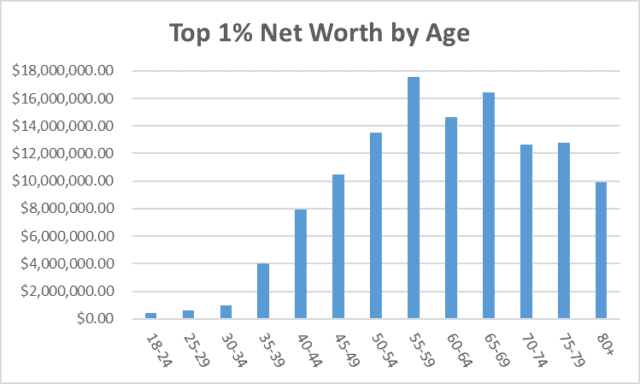 How Does Net Worth Actually Develop Over a Lifetime? - Wealthtender
The “Age” Trap (And Why You’re Not A Loser)
Here’s the part that makes me chuckle. Comparing your net worth to a random percentile by age is like comparing your height to a professional basketball player’s—it’s a rigged game. A 45-year-old in the top 5 percent might have $2 million, but they also might have a massive mortgage and two kids in college. Their liquid net worth could be $200,000. Meanwhile, a 45-year-old renter with $800,000 in cash and stocks might feel broke, but they’re actually much closer to financial freedom.
So, what’s the real takeaway? Stop using these numbers to beat yourself up. Use them as a rough compass, not a GPS. If you’re 35 and have $50,000, you’re not “behind”—you’re just not in the top 5 percent, and that’s fine. The goal isn’t to be in the top 5 percent; the goal is to be able to sleep at night when the market drops 20%.
Let’s be honest, most people reading this aren’t aiming for a yacht. You just want to retire without eating cat food. And guess what? You can build a perfectly good life on a net worth of $1 million at 65—that’s like the top 20 percent, and it’s plenty.
A Final Reality Check (From One Anxious Person To Another)
Remember Mark? I told him to stop reading those reports and instead calculate his savings rate. That’s the real metric of wealth. You can have a $200,000 net worth and save 30% of your income, and you’re wealthier than a guy with $2 million who spends $180,000 a year. Seriously, the second guy is one bad quarter away from a nervous breakdown.
So here’s my closing thought: the top 5 percent net worth by age is a fun party trick, a curiosity, a way to feel smug for five minutes. But it’s not a measure of your worth as a human, nor is it a reliable predictor of your happiness. Your real job is to save a little more than you spend, invest in low-cost index funds, and you know, touch some grass. Mark is still driving his Honda, but I caught him smiling at his brokerage statement yesterday. That, my friend, is the real top 1 percent.