Picture this: you’re at a backyard barbecue, flipping burgers, when someone casually mentions that “the top 5% of Americans are sitting pretty.” You nod along, but inside you’re thinking, “Am I in that club? Do I even want to be?” It feels like a secret society with a velvet rope, but the truth is more relatable—and a little more wonky—than you’d expect.
Let’s be honest: most of us aren’t counting yachts or private islands. We’re counting how many days until payday, or whether we can afford a new dishwasher without wincing. So when we hear “top 5% net worth,” our brains default to “that’s not me, and it never will be.” But here’s the kicker: that number isn’t as astronomically far away as you’d think. It’s less about Hollywood money and more about steady, boring habits that compound over time.
So, What’s the Magic Number?
Okay, let’s get the calculator out—but don’t panic. As of recent data, you need a net worth of roughly $1.3 million to $1.7 million to crack the top 5% in the US. That’s everything you own (house, investments, cash, that dusty coin collection) minus everything you owe (mortgage, student loans, credit cards).
Now, before you choke on your coffee, remember: net worth isn’t the same as income. You don’t need a seven-figure salary. Think of the couple who bought a modest home in 1998, paid it off slowly, and shoveled a little into their 401(k) every month. They might be worth more than a tech bro renting in San Francisco with a huge salary but zero savings. It’s the accumulation, not the flash, that gets you there.
Here’s a fun mental game: imagine your neighbor, Bob. Bob drives a 2013 Honda, grills his own chicken, and laughs at subscription services. Bob’s house is paid off, and he’s got a retirement account he’s never touched. Bob, my friend, is probably in that top 5%. Meanwhile, the guy with the leased BMW and a boat in the driveway might be swimming in debt. Wealth is quiet; it rarely posts on Instagram.
Why Should You Care? (Beyond Nosiness)
You might be thinking, “That’s great for Bob, but why does this matter for my Tuesday night laundry routine?” Fair point. Caring about the top 5% isn’t about envy—it’s about a mental shift. When you understand where the finish line is, you can aim for a smaller, more achievable version of it. You don’t need to hit $1.3 million tomorrow; you just need to know that it’s a marathon, not a sprint.
Also, it changes how you view money mistakes. That $5 latte habit? Not the villain. But the $30,000 car loan with 8% interest? That’s a net-worth slayer. Once you realize that net worth is a simple equation of assets minus liabilities, you start seeing every financial decision as a tiny push toward or away from that top 5% world. It’s like a video game where you get to control the stats.
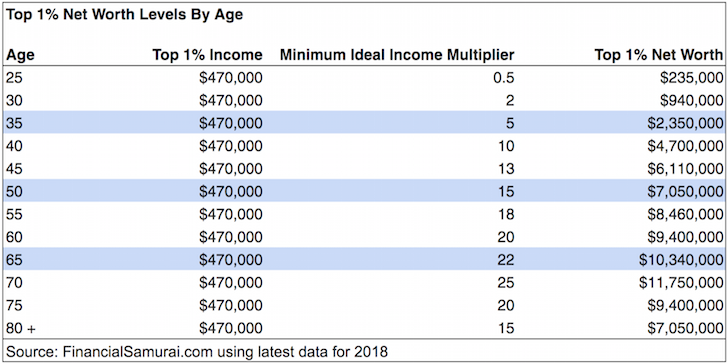 What Is The Top 5 Percent Income? – XOUM
The Little Stories That Make It Click
Meet Sarah. She’s a teacher, makes $62,000 a year. She’s not in the top 5%—not even close. But she buys a small duplex, lives in one unit, rents the other. Twenty years later, that property has doubled, and she’s got tenants paying her mortgage. Suddenly, her net worth includes a growing asset. She’s not a Wall Street wizard; she’s just stubborn and patient. That’s the secret sauce.
Or take Mike, who inherited $20,000 from his grandma. He could have blown it on a trip, but he put it into a boring index fund. He didn’t touch it for 25 years. With compounding, that $20,000 turned into over $100,000. Did he hit top 5%? No. But he built a bridge toward it. And that’s the real lesson: The top 5% isn’t a lottery ticket; it’s a collection of unglamorous choices.
What This Means for Your Sunday Afternoon
Here’s the practical takeaway: you don’t need to obsess over a threshold number. Instead, obsess over your personal “wealth ratio”—how much you own versus how much you owe. Take a hard look at your debts. A lower mortgage rate or a paid-off car is a bigger flex than a fancy watch. Every time you pay off a credit card, you’re stepping closer to that exclusive club, one boring, wonderful step at a time.
And please, don’t compare yourself to billionaires. That’s like comparing a goldfish to a great white shark—different species entirely. The top 5% is full of regular people with irregular habits: they save early, avoid lifestyle inflation, and don’t panic during market dips. They also tend to be relentlessly consistent.
So, why care? Because it’s a mirror. It shows you that wealth isn’t about being a genius or a celebrity. It’s about playing the long game with a little bit of discipline and a lot of patience. Next time you’re at a barbecue and someone brings up the top 5%, you can smile, take a bite of your burger, and think, “I’m not there yet, but I know the road map.” And honestly? That’s a pretty delicious place to be.