Let’s be honest—when you hear the words “net worth percentile,” your brain probably conjures up images of dusty spreadsheets and guys in suspenders muttering about dividends. But stick with me, because this isn’t about becoming a Wall Street wizard. It’s about figuring out where you fit in the great, messy, hilarious game of adulting—and feeling a whole lot better about your own scoreboard.
Your Neighbor, Your Bank Account, and You
Imagine you’re at a neighborhood barbecue. On your left is a chiropractor who just bought a boat. On your right is a schoolteacher who drives a 2012 Honda with a “Baby on Board” sticker that’s now peeling. If you peek into their savings accounts (which you absolutely shouldn’t, but let’s pretend), you’d see wildly different numbers. The net worth percentile by age is basically a map of where you land on that street—comparing your assets (what you own) minus debts (what you owe) against everyone else in your age bracket.
Why care? Because comparison is sneaky. It’s 2 a.m., you’re doom-scrolling, and you see a former classmate’s vacation photo in Santorini. You feel a pang of “am I falling behind?” The percentile data gives you a reality check—not to shame you, but to say, “Hey, you’re actually doing okay, Karen from accounting just has a rich husband.”
Must Read
The 20s: Ramen Noodles and Big Dreams
In your 20s, your net worth is usually negative. That’s not a typo. You’ve got student loans, a starter car loan, and a security deposit for an apartment that smells like the previous tenant’s curry. Your “assets” might be a laptop and a futon. The 25th percentile for a 25-year-old is often around zero or slightly negative—and that’s perfectly normal. You’re building a career, not a fortune.
I remember my own 25th birthday: I had $400 in savings and a broken air conditioner. My 50th percentile peers had maybe $15,000 saved. Fancy? No. But here’s the secret—your early 20s are for earning potential. That $30,000 you’re not saving now becomes a $90,000 salary later because you invested in skills. Don’t panic. Your future self is a marathon runner, not a sprinter.
The 30s and 40s: The Squeeze Years
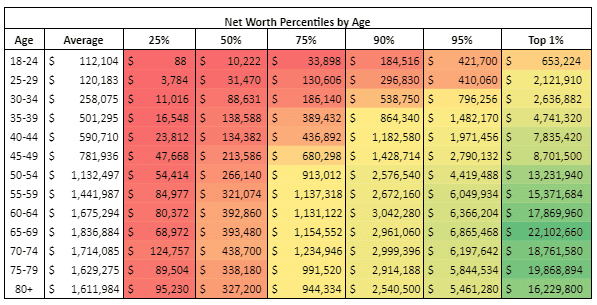
By your mid-30s, the percentile curve starts to look like a ski slope—one that’s going up, but with a few moguls. The median net worth for a 35-year-old hovers around $50,000. That’s not “rich,” but it’s real progress. You might own a home (or a down payment), have a 401(k) with an actual balance, and you’ve finally stopped paying for your parents’ Netflix.
Here’s the kicker: the 75th percentile at age 40 is around $400,000. Sounds huge, right? But that often includes home equity. Let me tell you about my friend Dave—at 42, he felt “poor” because his neighbor had a Tesla. Then Dave realized his neighbor was $80,000 in debt on that Tesla, while Dave’s paid-off Subaru and $150k in retirement savings made him technically richer. Debt is the great equalizer in reverse. Don’t chase cars. Chase compound interest.
The 50s and Beyond: The Finish Line (Sort Of)
In your 50s, the numbers get chunky. The median net worth jumps to around $200,000, but the 75th percentile soars past $800,000. That’s when you see the “double income, no kids” couples with lake houses, and the “raised three kids on one teacher’s salary” folks who are still renting. Both stories are valid. The percentile data isn’t a judgment—it’s a reflection of life’s choices.
 The Net Worth Of The Average American: Net Worth By Age - Crushing REI
What matters more than the number? Your runway. In your 50s, you’re not worried about impressing the neighbors. You’re worried about whether you can retire at 65 without eating cat food. A 2023 study showed that the top 10% of 65-year-olds have over $1.9 million. The bottom 25% have less than $10,000. That gap is scary, but it’s also a reminder: every single dollar you save now is a vote for your future comfort.
Why This Matters to Your Monday Morning
So why should you care about percentiles? Because they strip away the noise. When you’re 34 and your friend posts a photo of her new kitchen, you can whisper to yourself, “I’m in the 60th percentile for my age. I’m fine.” It’s not about being average—it’s about being aware. The percentile gives you a target without the smugness of a benchmark.
Here’s the warm, fuzzy truth: net worth is a snapshot, not a selfie. It changes daily. My neighbor’s house appreciated by $20k last year, but his roof cost $15k to fix. The stock market giveth, and the stock market taketh away. Your worth as a human isn’t tied to your checking account—but your freedom is. That’s the real reason to care.
Your Action Plan (Low Pressure, High Reward)
Stop comparing your behind-the-scenes to everyone else’s highlight reel. Instead, pull up a net worth calculator, type in your numbers, and see where you stand. If you’re below the 25th percentile, don’t spiral—start small. Automate $50 a month into a savings account. If you’re above the 75th, congratulations—now help a friend who isn’t.
The best part? This isn’t a contest. It’s a community potluck. Some bring the slow-cooked brisket (those with high savings), others bring the store-bought chips (the rest of us). But we all eat together. So check your percentile, laugh at the absurdity of it all, and then go enjoy that barbecue. Your net worth is just a number—your net happiness is the real metric.