
Let’s be honest for a second—when you hear “top 5 percent,” your brain probably flashes to private jets, Napa vineyard tours, and that one cousin who somehow bought a beach house before turning 30. But the reality is far more chill, and honestly, far more attainable than you’d think. In the U.S., cracking the top 5% of net worth doesn't mean you're rolling in diamonds; it means your household assets—home equity, investments, cash, and that dusty 401(k)—total roughly $2.5 million or more. That’s it. No yacht required.
Here’s the fun part: that number feels huge, but it’s often built on a foundation of boring, repeatable habits. Think of it like the financial version of a slow-cooked brisket—not flashy, but deeply satisfying. The real secret isn’t a Wall Street tip; it’s time, consistency, and a stubborn refusal to let lifestyle inflation eat your raise.
The Quiet Millionaire Next Door
You’ve probably walked past a top-5-percenter without a second glance. They’re the ones driving a 2018 Honda CR-V with a “Dog Mom” sticker, not a leased Porsche. The classic research from The Millionaire Next Door still holds: most high-net-worth folks are self-made, debt-averse, and painfully frugal in specific areas.
Must Read
They splurge on a great mattress and a sharp accountant, but they’ll still pack a sandwich for a flight. It’s not about deprivation; it’s about selective extravagance. They know that a $12 cocktail adds up to a $4,000 annual vacation—so they skip the cocktail and take the trip.
The Math Is Surprisingly Chill
Let’s break down the “how,” because it’s less about earning $500K a year and more about a steady, unglamorous climb. A 35-year-old with a solid tech salary, a spouse with a nursing degree, and a modest 3-bedroom house in Ohio can absolutely hit that mark by 55. The formula? Max out your 401(k) from day one, buy a house you can actually afford on one income, and let compound interest do the heavy lifting.
Fun fact: if you invest $1,000 a month at a 7% real return, you’ll hit $1.2 million in 30 years. Add in a paid-off home (worth $800K) and a business or side rental—boom, you’re in the club. It’s not sexy, but it works. The top 5% isn’t a lottery winner’s bracket; it’s a patience bracket.
The Cultural Myth of “Rich”
Pop culture loves a billionaire villain, but the top 5% is your friendly neighborhood dentist or the owner of the local HVAC company. They’re not hoarding gold in a vault—they’re just debt-light and asset-heavy. That’s the real distinction. A doctor earning $400K but owing $200K in student loans and $1.5M on a mortgage is technically “high-income,” but their net worth is often far lower than the teacher who paid off a modest home and invests aggressively.
This is where the Keeping Up with the Kardashians effect hurts us. We compare our bank statements to curated Instagram feeds, forgetting that half those “influencers” are renting everything. The top 5% usually flies under the radar because they have zero interest in proving anything to strangers.
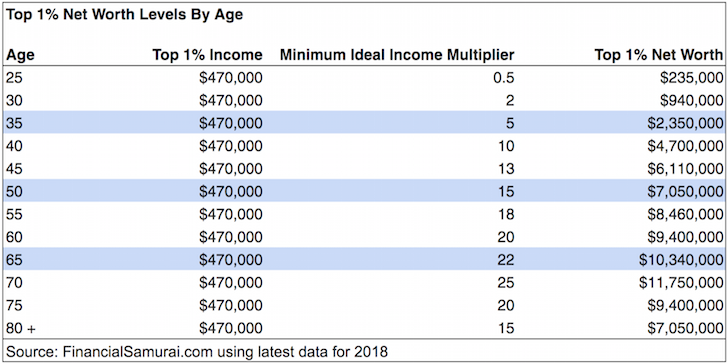 What Is The Top 5 Percent Income? – XOUM
Practical Steps to Join the Club (Without Joining a Cult)
First, automate your savings like it’s a utility bill. You don’t skip paying electricity, so don’t skip your investment contribution—make it automatic and boring. Second, tax efficiency is your new favorite hobby. A Roth IRA, a Health Savings Account (HSA), and a backdoor Roth aren’t just accountant jargon; they’re legal loopholes that save you six figures over a lifetime.
Third, don’t buy a new car. Seriously. A three-year-old used Lexus is the same car, at 60% of the price. The top 5% are masters of buying used luxury—that’s how they stay rich while earning a normal wage.
The Fun Fact You’ll Drop at Dinner
Did you know that the top 5% holds about 54% of all U.S. household net worth? That sounds scary until you realize the top 1% holds 32%—so the gap between the 99th percentile and the 95th percentile is massive. In other words, being in that bracket is more about solid middle-class-plus habits than being an oligarch. It’s the “rich” you can actually touch with a 20-year plan, not a lottery ticket.
Also, regional bias is real. You need $4.4 million in San Francisco to be top 5%, but only $1.9 million in Mississippi. So, if you’re flexible, a low-cost state is basically a cheat code. But hey, we get it—you love your avocado toast and coastal breeze. Just know the math is on your side if you ever get sick of traffic.
The Daily Life Connection
Here’s the takeaway that actually matters: your morning coffee habit isn’t ruining your net worth, but your attitude might be. Chasing “top 5%” as a magic number is a trap. Instead, focus on what that number represents: freedom, security, and the ability to say no to a bad job or a draining relationship.
Next time you’re scrolling through vacation pics of a friend who’s “killing it,” remember—their credit card might be crying. True wealth is quiet. It’s a paid-off mortgage, a funded emergency cushion, and the peace of knowing you could lose your job and still sleep like a baby. That’s the real luxury. And honestly, that’s worth more than a yacht ever could be—because you can’t take a boat to a good night’s sleep.