So, you’ve hit the big 4-0. Congratulations! You’re officially old enough to know better, but young enough to still pretend you don’t need reading glasses.
And now, the question that keeps you up at night (besides that second cup of coffee): What is a “good” net worth at 40? Let’s be real, you’re probably comparing yourself to that guy from college who invented a weird app, or your neighbor with the boat. Stop it. Right now.
The Big, Scary Number
Financial gurus love throwing around benchmarks. They’ll tell you that by 40, you should have about two to three times your annual salary saved up. That’s it? That feels… weirdly specific, right?
Must Read
If you make $100k a year, that means you need $300k in the bank. But wait—does that count your 401(k)? Your house equity? Your secret stash of vintage baseball cards? The rule is usually about investable assets, not your Beanie Baby collection.
Here’s the kicker: that number is a starting point, not a report card. It’s a loose guideline, like the “best by” date on a jar of pickles. You’re probably fine even if you’re a little late to the party.
The “It Depends” Trap (Because It Always Does)
Let’s get real for a second. A “good” net worth at 40 depends entirely on your life, not a fancy chart. Are you a single city dweller in a rental? Or are you a suburban parent with a mortgage and two kids who eat like locusts?
If you live in San Francisco, $500k feels like pocket change. In rural Ohio, that same amount makes you a mogul. Context is everything, people. It’s like asking “how long is a piece of string?”—except this string is made of dollar bills and anxiety.
Also, let’s talk about the elephant in the room: debt. If you have a $400k net worth but also carry $50k in credit card debt, your actual net worth is $350k. Math is rude like that. The goal isn’t just a number; it’s a clean number.
What’s Actually “On Track”?
Let’s break it down without the spreadsheet headache. A solid rule of thumb: by 40, you should have zero high-interest debt (looking at you, credit cards) and a growing retirement fund. That’s the non-negotiable baseline.
Then, you add up your cash, investments, and any property equity. Subtract what you owe on your mortgage, student loans, and that impulsive jet ski. The result? That’s your net worth. It’s not brain surgery, but it is a little terrifying.
 The Net Worth Of The Average American: Net Worth By Age - Crushing REI
So, is $250k good? Yes. Is $1 million better? Obviously. But here’s the secret: just having a positive number puts you ahead of roughly 30% of Americans. Pat yourself on the back. You’re not broke, and that’s a win.
The Real “Good” Net Worth
Here’s my hot take, served with a side of sass. A good net worth at 40 isn’t just about the digits in your brokerage account. It’s about peace of mind. Can you handle a $2,000 car repair without having a meltdown? That’s wealth, my friend.
It’s also about having a plan. If you’re 40 and you’re saving something—even $200 a month—you’re already winning. The people who fail are the ones who think “I’ll start at 50.” Newsflash: your future self is already rolling their eyes.
And please, for the love of all that is holy, don’t compare your chapter 20 to someone else’s chapter 40. That buddy with the boat? He probably has $14,000 in boat loan payments. You’re fine.
So, What’s The Magic Number?
Fine, you want a definitive answer? Here’s my professional, totally unscientific, coffee-fueled verdict. Aim for $300,000 to $500,000 in total net worth by 40. That includes your 401(k), home equity, and savings. Not there? Don’t panic.
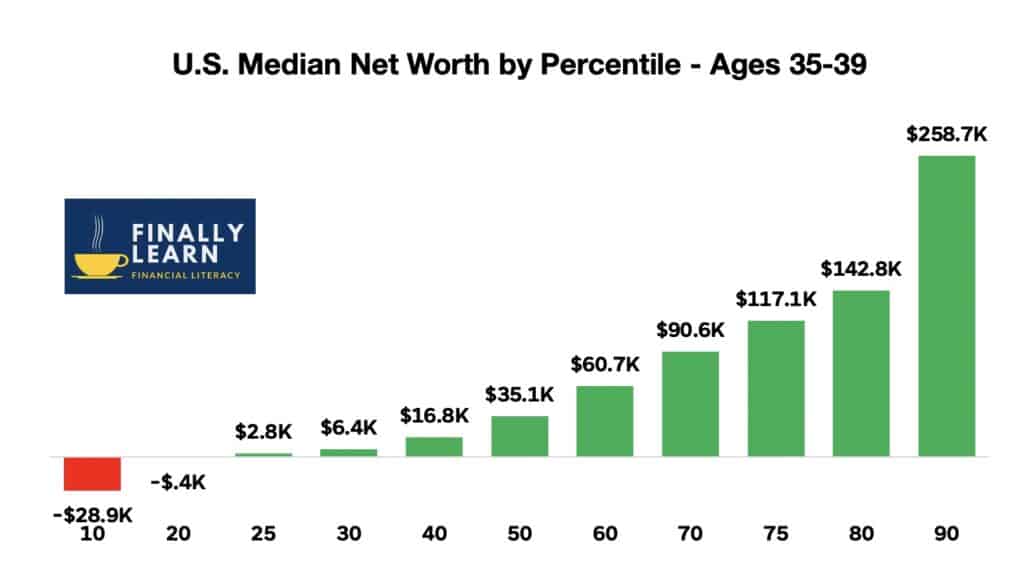
The average net worth for a 40-year-old in the US is around $135k, but the median is way lower—like $91k. That means half of all 40-year-olds have less than that. So if you’re at $200k, you’re not just okay; you’re the cool kid on the block.
Here’s my final thought: Your net worth is a tool, not a trophy. It’s there to buy you freedom, not to impress strangers at dinner parties. If you have enough to sleep soundly, chase a hobby, and maybe retire before you’re 70, you’re crushing it.
Now, go refill your coffee. And maybe check that 401(k) balance, just for fun. You’ve got this.