
Let’s be honest—when you hear the phrase “net worth,” your brain might immediately picture a billionaire in a glass tower, counting gold coins like Scrooge McDuck. But here’s the secret: net worth isn’t just for the rich and famous. It’s actually just a fancy way of saying “what you own minus what you owe.” Think of it as your financial report card, but without the pressure of getting an A+.
Imagine your life is a big, cozy backpack. On one side, you’ve got all the good stuff—your savings, your car (if it’s paid off), your retirement account, that vintage comic book collection. On the other side, you’ve got the heavy bricks—your credit card balance, your student loans, that lingering “buy now, pay later” app you swore you’d delete. Net worth is simply the weight of the backpack after you toss out the bricks.
Let’s Do the Math (Don’t Worry, It’s Easy)
Picture your friend Dave. Dave owns a used sedan worth $5,000, has $2,000 in the bank, and a $3,000 emergency stash under his mattress (kidding, but we love the enthusiasm). That’s $10,000 in assets. Now, Dave also has a credit card bill of $1,500 and a student loan of $4,000. That’s $5,500 in liabilities.
Must Read
So Dave’s net worth is $10,000 minus $5,500 equals $4,500. Not exactly yacht money, but hey—Dave is in the positive! And that’s a win. Meanwhile, your neighbor who leases a shiny BMW and pays for it with a maxed-out card? They might have a net worth of negative $20,000. Turns out the guy with the fancy car is actually walking around with a backpack full of rocks.
Why Should You Care? (Besides Bragging Rights)
You might be thinking, “Okay, cool, but I don’t plan on selling my soul to investment bankers, so why does this matter?” Great question. Net worth is like a health checkup for your money. You don’t go to the gym just to impress strangers—you go so you feel good and can climb stairs without huffing. Net worth does the same for your bank account.
It tells you if you’re moving forward or just spinning your wheels. For example, if you get a $2,000 tax refund and immediately spend it on a new TV, your net worth hasn’t budged. But if you put that $2,000 into a high-yield savings account, you just gave your net worth a little boost. It’s the difference between looking like you’re doing well and actually doing well.
The “Comparison Trap” (And How to Dodge It)
Here’s the fun part: net worth is deeply personal. Your friend posts a photo of their new kitchen renovation on Instagram, and suddenly you feel poor. But guess what? They might have financed that kitchen with a home equity loan, putting their net worth in the basement. Meanwhile, you’ve been quietly paying off your old car, and your net worth just ticked up by $200 this month. You’re winning the slow race, and that’s the race that counts.
Think of net worth like your own personal fitness tracker. You wouldn’t compare your step count to a marathon runner’s, right? Same deal here. A 25-year-old with $5,000 in net worth is doing fantastic. A 60-year-old with $5,000 might be in trouble. It’s all about your path, not the person next to you.
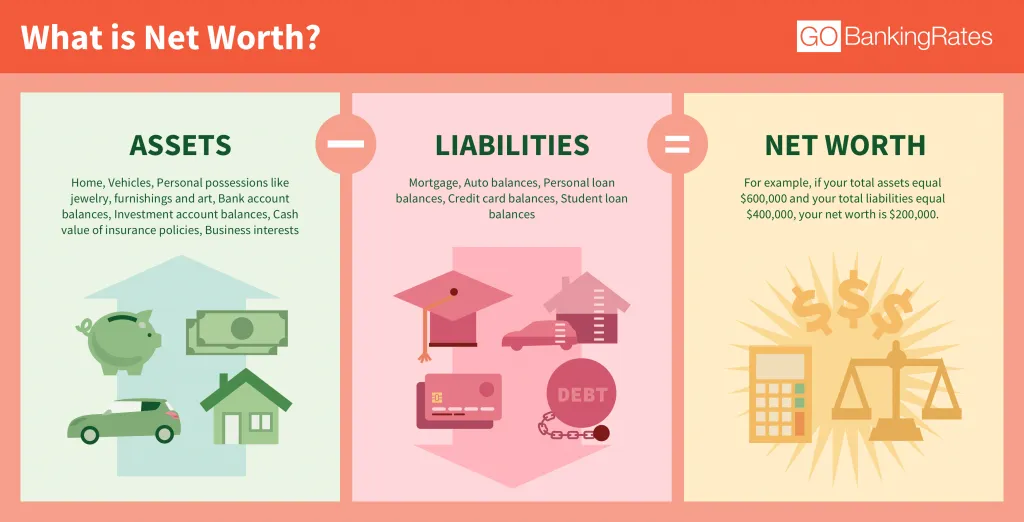 Net Worth: What It Is and How To Calculate It | GOBankingRates
How to Make Your Net Worth Go Up (Without Eating Only Ramen)
Here’s the good news: you don’t need a six-figure salary to grow your net worth. You just need to tip the scale. Pay off a $50 credit card charge? Boom—your net worth goes up. Use a coupon for 10% off your groceries and put the savings into a jar? Technically, that’s an asset. Ok, that might be overkill, but you get the vibe.
Start small. Track what you own and what you owe once a month—maybe on the first Sunday, while your coffee brews. You’ll notice that paying down a tiny debt feels like unlocking a level in a video game. Every dollar you keep out of debt is a dollar that makes your net worth smile. And before you know it, you’ll be checking your numbers more often than your social media feed—not because it’s addictive, but because it’s satisfying.
The Real Takeaway
Net worth isn’t about being a miser or counting every penny until you turn into a human calculator. It’s about freedom. The higher your net worth, the more choices you have—like quitting a job you hate, taking a sabbatical, or just sleeping better at night knowing you’re not upside down on your finances.
So go ahead, grab a napkin or the Notes app on your phone. Write down your assets (even that $50 gift card from your aunt) and your debts (yes, even that $20 you owe your buddy for pizza). Do the math. If the number is positive, do a little dance. If it’s negative, don’t panic—just smile and say, “Alright, game on.” Because the best part about net worth is that it changes every single day. And tomorrow, you can make it go up.
Remember: You’re not a number, but the number is a useful mirror. Look in it, laugh a little, and keep moving forward. Your future self—with their paid-off car and no credit card stress—will totally high-five you.