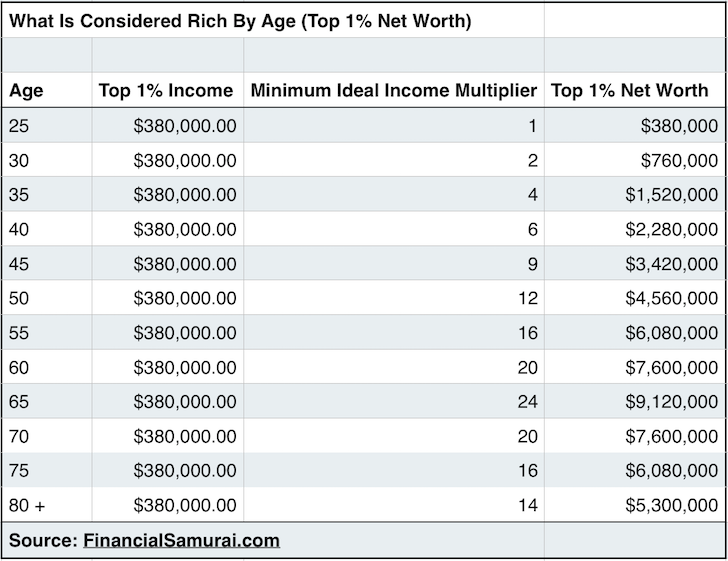
Picture this: you’re at a dinner party, and someone drops the phrase “the top 1%.” Instantly, mental images of private jets, champagne towers, and maybe a yacht named Serenity Now flood the room. But what does that club actually look like in cold, hard numbers? It’s not just about earning a fat paycheck—it’s about the net worth you’ve stacked up over a lifetime, and the gap is wilder than a plot twist on Succession.
The Magic Number That Opens the Door
To crack the top 1% in the U.S., you’re looking at a net worth of roughly $13.7 million as of recent data. That’s not your annual salary; that’s everything you own minus everything you owe—the house, the investments, the vintage guitar collection, and yes, that slightly regrettable timeshare. For context, the median American household sits at around $192,000, which means the 1% is holding about 70 times more wealth than the middle of the pack.
The real kicker? You don’t need to be a tech mogul or a Hollywood star to get there. A surprising slice of the 1% are boring—think dentists in Ohio, mid-sized manufacturing owners, and retired CFOs who quietly compounded their 401(k)s for four decades. It’s less about flashy income and more about accumulation, which is oddly comforting if you’re a spreadsheet nerd.
Must Read
Where Do You Actually Stand?
Let’s play a quick game of “financial horoscope.” If your net worth is around $1.1 million, you’re already in the top 10%—which sounds impressive until you realize the 1% is eleven million dollars ahead of you. The climb from the 90th percentile to the 99th is not a gentle slope; it’s a sheer cliff where every additional million requires a different strategy, like moving from a savings account to private equity.
Here’s a fun little reality check: the top 1% holds more than 30% of the nation’s wealth, while the bottom 50% fights over a measly 2.5%. That’s not a political rant—it’s just the math of the Monopoly board we’re all playing. But here’s the twist: your zip code and your parents’ tax bracket still do a lot of heavy lifting—over 60% of the 1% inherited a chunk of their pile, which feels less like “self-made” and more like “started on third base.”
Practical Tips to Edge Closer (Without Selling a Kidney)
You’re not going to wake up tomorrow with $13.7 million, but you can nudge your own numbers with a few under-the-radar moves. First, stop chasing hot stocks and start maxing out your tax-advantaged accounts—the wealthy treat compound interest like a religion, not a suggestion.
Second, own real assets that generate cash flow. Rental properties, a side business, or even royalty income from a niche podcast can push your net worth faster than a salary bump, because the rich don’t trade time for money—they trade money for money. And finally, live below your means, but not like a miser; the 1% typically saves 50% of their income, not because they’re cheap, but because they’ve learned that delayed gratification is the ultimate flex.
Consider this: if you invest $1,000 a month at a 7% return starting at age 30, you’ll hit around $2.5 million by 65. That won’t put you in the 1%, but it’s a solid ticket to the top 5%—and honestly, that’s where most of the fun happens anyway, with less paparazzi.
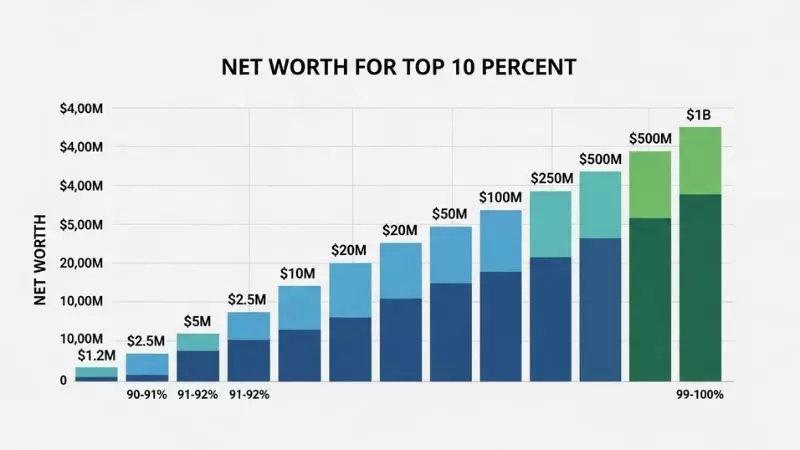 Net Worth for Top 10 Percent: Income, Assets & Wealth
Cultural Crossroads: What the 1% Buys With All That Cash
Pop culture loves to paint the ultra-rich as eccentric villains—think of the faux-mysterious buyers in The White Lotus or the ruthless venture capitalists in The Dropout. And sure, some of them do buy $200,000 watch collections and private islands with airstrips. But the smarter 1% spend on experiences and education: think art that appreciates, wine cellars that become investment portfolios, and tutors for their kids that cost more than your rent.
Fun fact: the most common asset among the top 1% isn’t a yacht—it’s a diversified stock portfolio, followed by their primary home and a small business they actually run. They’re not living like Gatsby; they’re living like a very disciplined accountant who happens to own a ski condo. That’s the secret sauce—the wealth comes from boring, repetitive behavior.
The Entertainment Side of the Wealth Gap
Let’s be real: there’s a guilty pleasure in scrolling through “luxury home tours” on Instagram, imagining yourself in a 12-bathroom mansion with a bowling alley. That’s the entertainment value of the 1%—it feeds our fantasies while conveniently ignoring the fact that most of them are working 60-hour weeks or sitting on decades of quiet anxiety about market dips. The truth is, net worth is a snapshot, not a self-help book; a market crash can shave off $3 million overnight, and then you’re just a regular billionaire with a headache.
For the rest of us, the gap can feel like a dystopian sci-fi novel, but it’s also a reminder that wealth is relative to your own goals. Want to retire early? That’s a $1.5 million goal. Want to leave something for your kids? $500k might do. The top 1% is a moving target, but your own finish line is the only one that actually matters.
A Short Reflection for Your Morning Coffee
Here’s the thing: chasing the 1% is like chasing a mirage in a desert—you’ll never feel full, only hotter and more thirsty. Most of us aren’t going to join that club, and that’s not a failure; it’s a storyline choice. The real wealth, the kind you feel in your bones, is the freedom to not panic when your car breaks down, the ability to take a Tuesday off, and the quiet security of knowing your savings can cover six months of rent.
So, check your net worth, smile at the number, and then go buy a good coffee or a used book. Because the top 1% might have the golden ticket, but you’ve got the keys to your own life, and that’s a portfolio no index fund can measure.