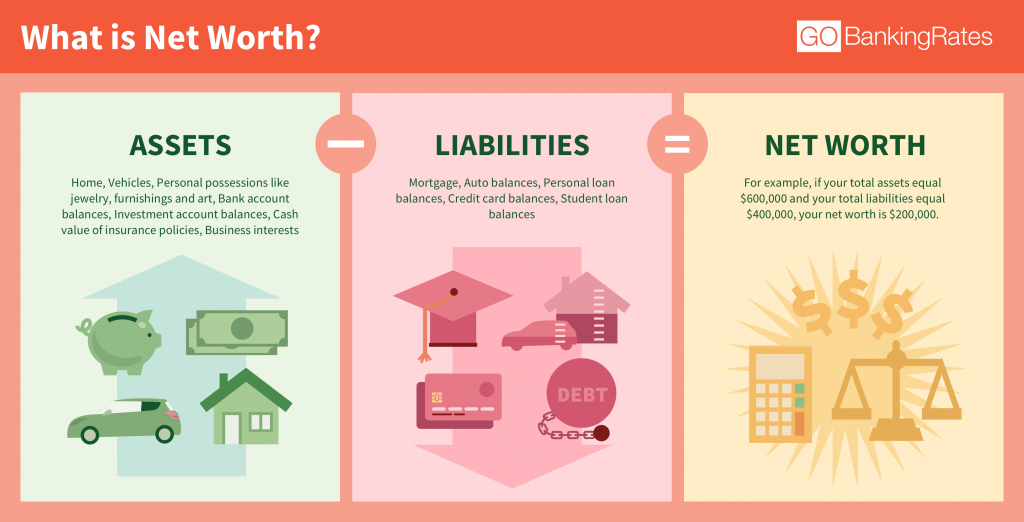
Let’s be honest: “net worth” sounds like something a stuffy billionaire whispers at a yacht party. But it’s actually just a fancy way of saying “what’s left if you sold all your stuff and paid off your debts.” Think of it as your financial report card, but with fewer gold stars and more spreadsheets.
It’s not about bragging. It’s a snapshot of your money life—a weird, brutally honest selfie. And once you get it, you’ll see it’s a total game-changer for how you make choices.
It’s Your Financial Compass (Not a Score)
Forget the “rich vs. poor” drama. Net worth is your personal GPS for the future. It shows you if you’re drifting toward trouble or cruising toward freedom.
Must Read
Imagine you make $10,000 a month but owe $50,000 on credit cards. You feel rich, right? Wrong. Your net worth might be negative, meaning you’re actually broke on paper. That painful math is exactly why you need it—it cuts through the illusion of a fat paycheck.
On the flip side, a retiree with a tiny income but a paid-off house and a nice 401(k) has a huge net worth. They might drive a rusty Honda, but they’re wealthier than the dude in the leased BMW. Fun, huh?
The “Emergency Exit” Metric
Life loves throwing curveballs—a lost job, a broken leg, or a surprise roof repair. Net worth tells you how long you can survive before things get scary. It’s your metaphorical airbag.
Here’s a fun rule: your net worth is basically your “F-U money” meter. If your assets minus debts gives you a solid cushion, you can quit a toxic job or take a risky leap. If it’s a big fat zero, you’re a passenger, not a driver.
That number isn’t just digits. It’s freedom in disguise. It’s the difference between “I have to” and “I choose to.”
Borrowing Power & The Bank’s Weird Love
Banks are shallow. They only care about your net worth because they want to know if you’ll repay their money. A high net worth means you get better interest rates, bigger loans, and fancier credit cards.
It’s not fair, but it’s true. Your net worth is like a bouncer at a club—if it’s high enough, you skip the line. If it’s low, you’re standing in the rain, showing valid ID and hoping for a pity nod.
Even your landlord might peek at it. No joke—some will ask for proof of assets before renting you a place. Your net worth literally unlocks doors (and apartments).
Tracking It Fixes Your Brain
Here’s the sneaky part: just thinking about net worth changes how you spend. You stop buying junk because you realize that $500 designer jacket is just a one-way ticket to “stuff you’ll sell for $20 on eBay.”
You start noticing assets vs. liabilities. A car? Liability—it loses value the second you drive it off the lot. A house? Maybe an asset, but only if you don’t have a huge mortgage on it. This is where nerdy people have actual fun.
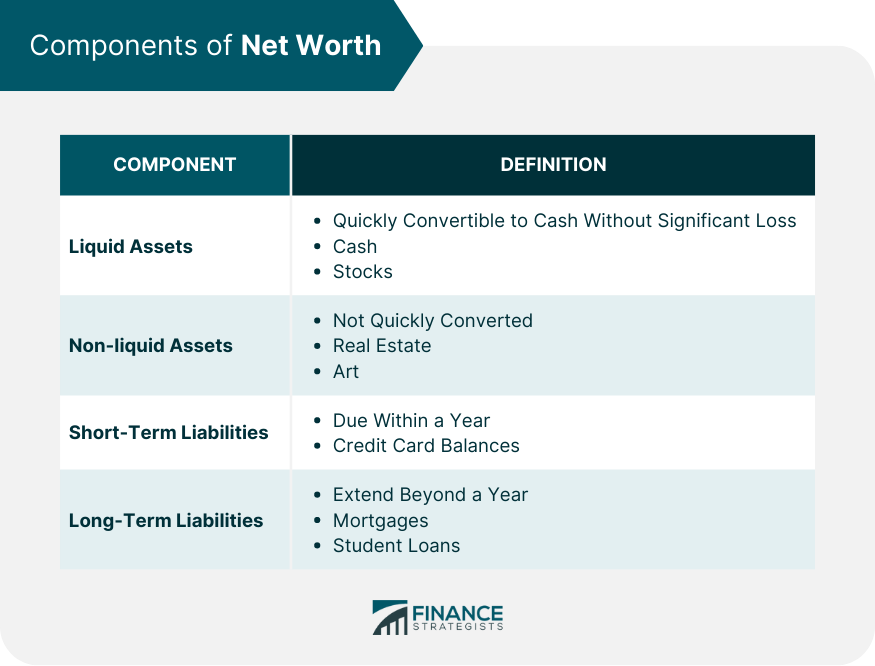 Net Worth | Definition, Components, Calculation, Significance
I once tracked my net worth monthly and got obsessed. It’s like a video game where you level up by paying off debt. The high score isn’t about being rich—it’s about slowly watching the red numbers turn black.
The Quirky, Awkward Truth
Nobody talks about this at parties, but your net worth includes your pension, your comic book collection, and that ugly painting from your grandma. Yes, it counts—if you can sell it. That’s why some folks have “negative net worth” for years. It’s normal.
Even celebrities mess this up. You know that rapper with diamond grills? His net worth might be lower than your mailman’s because of lawsuits and bad investments. Cash flow ain’t wealth. Net worth is.
And a hilarious fact: most millionaires have a net worth over $1M, but they often drive regular cars and clip coupons. Meanwhile, your neighbor who buys three ATVs might be drowning in debt. Never trust the surface.
It’s for “Boring” Life Goals Too
Net worth isn’t just for retirement or buying a yacht. It helps you decide if you can afford that master’s degree, a move to a new city, or a year off to write a novel. It’s your “what-if” calculator.
Want to start a business? Net worth shows how much cash you can burn before you start panicking. Want to retire at 50? You’ll need a specific number—usually 25 times your annual expenses, but that’s a nerd rabbit hole.
The point is: you can’t plan a fun future without a boring metric. It’s the unsung hero.
Don’t Let It Scare You
Here’s the best part—net worth is not your identity. If it’s low today, fine. You can change it. Every time you pay off a student loan or save $50, your number creeps up. It’s literally under your control.
So start calculating. Use an app, a spreadsheet, or a napkin. Add up your cash, investments, house value, and that old guitar. Subtract your debts. Boom—you have your number.
Then? Watch it move. It’s addictive, silly, and genuinely fun. You’ll never see money the same way again. Trust me—your future self will thank you.