Okay, let’s be real for a second. We’ve all wondered what it means to be really rich, not just “I can buy extra guac” rich, but “my money has its own zip code” rich. You hear about the "top 1%" all the time, like it’s some secret club with velvet ropes. But what does that actually mean for your bank account?
Well, the short answer is that the top 1% in the US isn’t about annual income, which is what most people guess. It’s about net worth – the total value of everything you own, minus everything you owe. That’s your house, your stocks, your retirement accounts, even that vintage comic book collection, all added up, with your credit card debt and mortgage taken out.
So, what’s the magic number to get your golden ticket? As of recent data, you’d need a net worth of roughly $13.7 million. Yeah, you read that right. Not one million, not five million, but a solid thirteen-point-seven million dollars. It’s the kind of number that makes you want to check under your couch cushions for loose change, right?
Must Read
Why It’s Not All About Your Paycheck
Here’s the fun twist: you might be pulling in a massive salary and still not crack the top 1%. Why? Because a huge income often comes with huge spending. Think about the doctor or the lawyer who drives a Tesla but has a massive mortgage and private school tuition. They earn a ton, but their net worth is locked up in liabilities.
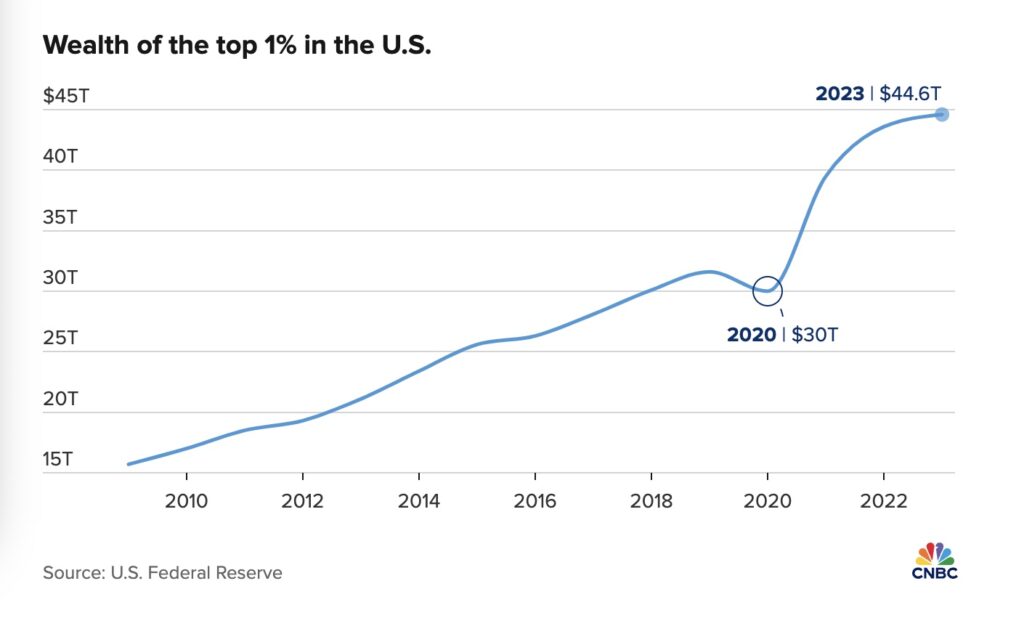
The real secret sauce for the top 1% is assets. They aren’t just trading hours for dollars; they’re letting their money do the heavy lifting. It’s about owning businesses, real estate, and stocks that grow over time, creating a snowball effect that’s hard to stop. It’s a completely different game of Monopoly.
And here’s the kicker: that number isn’t static. It keeps climbing! Ten years ago, the threshold was around $9 million. Now it’s $13.7 million. So, if you’re chasing this goal, you’re not just running a race; you’re running a race where the finish line keeps moving further away. Is it exhausting? Absolutely, but that’s what makes it fascinating.
Let’s Break It Down With Some Fun Math
Imagine you saved $100,000 every single year. That’s already a fantastic achievement, putting you ahead of most people. Now, keep that up for 137 years. That’s right, you’d need to start saving during the Civil War to hit the top 1% today. That really puts it into perspective, doesn’t it?
Or, think of it this way: with $13.7 million, you could buy around 274 brand new Toyota Corollas. Or, you could live in a city like Los Angeles and spend that on a moderately sized, non-mansion house by the beach. The difference between “rich” and “wealthy” is stark.
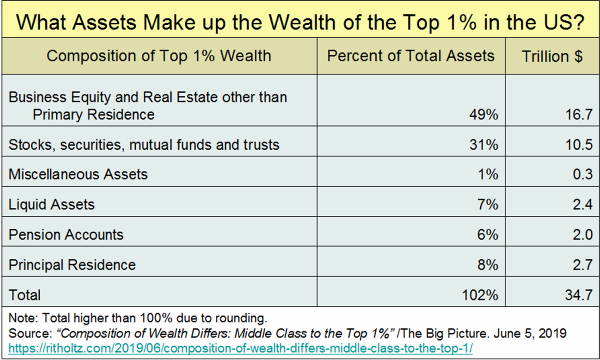 US Billionaires and the Top 1%: What is Their Total Net Worth and What
You could also generate roughly $500,000 a year in passive income just by sticking that money in a safe index fund. That’s a salary of half a million dollars, and you wouldn’t have to lift a finger. You could spend your days learning to surf, writing a novel, or just perfecting your sourdough bread recipe.
The Coolest Part? It’s (Mostly) About Behavior
Here’s the good news that keeps me up at night in a good way: the top 1% isn’t a secret society of geniuses. Sure, some inherited their wealth, but more than 70% of wealthy families are first-generation rich. That means they didn’t come from old money; they built it from scratch.
So, what’s the secret sauce? It’s boring, but it’s true: living below your means, investing early and often, and avoiding dumb debt. It’s less about hitting the jackpot with a crypto moon shot and more about patient, consistent habits. They didn’t get there by buying the newest phone every year or leasing a fancy car.
It’s a mindset shift. It’s asking, “How can I buy an asset that pays me?” instead of “What can I buy that will impress my neighbors?”. Once you see money as a tool for future freedom, rather than a toy for today, you’re already thinking like a 1%er, even if your bank account hasn’t caught up.
So, the next time you hear about the top 1%, you’ll have a clearer picture. It’s not about your six-figure salary; it’s about your balance sheet. And honestly? That’s a much cooler, more achievable goal to wrap your head around. It’s not about being born lucky; it’s about being intentional. Now, if you’ll excuse me, I need to go check my stock portfolio (and maybe buy some scratch-off tickets for fun).