
So, there I was, fresh out of college, ready to take on the world with my shiny new degree and a head full of dreams. I had this grand plan to invest every penny I had into some tech startup that was bound to be the next big thing. My dad, ever the wise one, looked at me like I was crazy and said, "Son, never put all your eggs in one basket." I rolled my eyes, but hey, he's my dad, he's supposed to say stuff like that, right?
Fast forward a few years, and I've learned a thing or two about money. One of the most important lessons? The importance of having a cash cushion. You know, that emergency fund that's just sitting there, ready to swoop in and save the day when your car breaks down or your roof starts leaking.
So, how much cash should you have, anyway?
That's the million-dollar question, isn't it? The answer, as with many things in life, is: it depends. On you, your lifestyle, your income, your debts, your risk tolerance. But let's talk about a general guideline that financial advisors often suggest: keeping 3-6 months' worth of living expenses in cash.
Must Read
But why so much?
Well, imagine this: you lose your job tomorrow. Or, heaven forbid, a global pandemic hits and you're stuck at home for months. Having that cash cushion can be the difference between panicking and scrambling, and taking a deep breath and making a plan.
Now, I'm not saying you should keep all your money in cash. That's like stuffing your mattress with $100 bills (not that I'd know anything about that). Inflation will eat away at your money, and you're missing out on potential growth from investments.
So, how much should be in cash, then?
Here's a general rule of thumb: keep 5-10% of your net worth in cash. This is a sweet spot that gives you peace of mind without sacrificing potential growth from investments. But remember, this is just a guideline. If you're a risk-averse person, or you're going through a phase of uncertainty (like, say, a global pandemic), you might want to lean towards the higher end of that range.
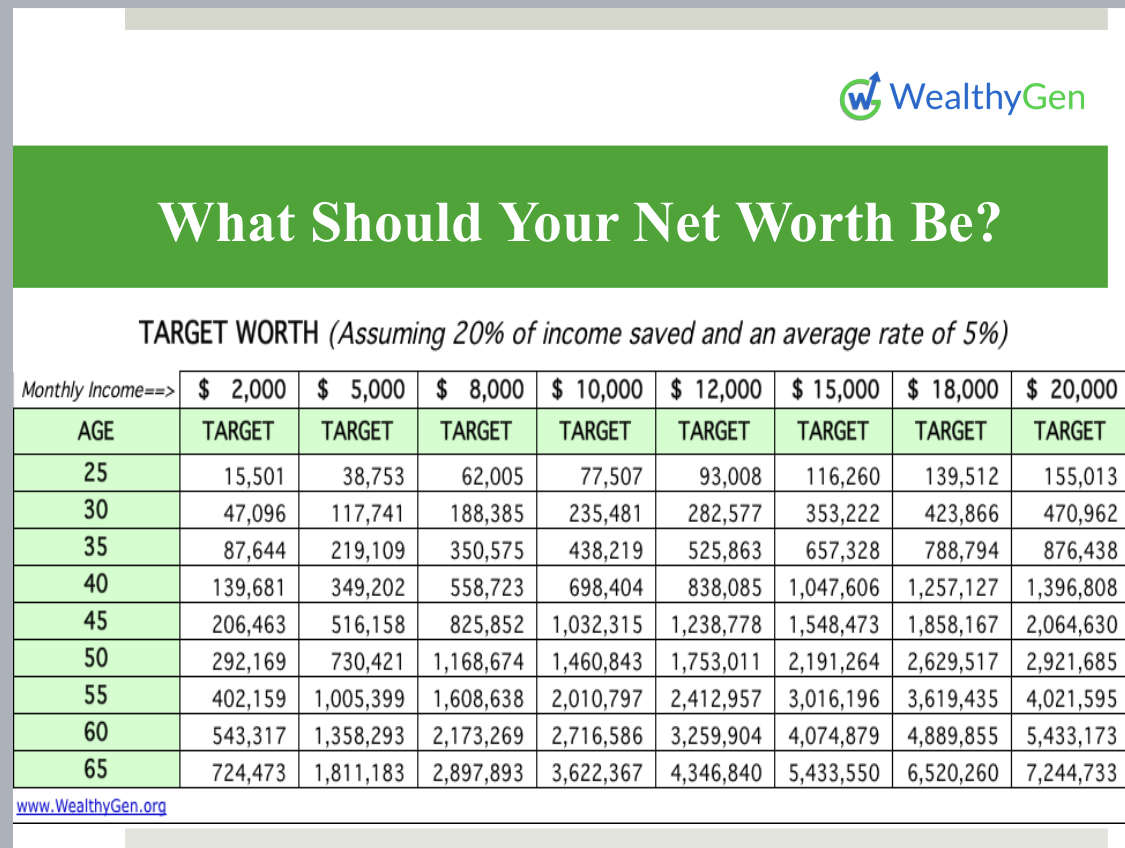 THIS IS WHAT YOUR NET WORTH SHOULD BE - WealthyGen Foundation
Now, you might be thinking, "That's all well and good, but what about my situation?" Well, that's where you need to do some soul-searching. Look at your income, your expenses, your debts, your investments. Ask yourself: how much can I afford to keep in cash without sacrificing my financial goals? How much would I need to weather a storm?
And what about you, dear reader?
Are you sitting on a pile of cash, or are you living on the edge, hoping your credit card will cover you in a pinch? It's time to take a hard look at your finances and ask yourself: am I comfortable with the amount of cash I have? Do I need to adjust my budget, my investments, my risk tolerance? Only you can answer that.
Remember, the goal here is balance. You want to be prepared for the unexpected, but you also want to grow your money. It's a delicate dance, but with a little planning and a lot of self-awareness, you can find that sweet spot.
And hey, if you're ever feeling unsure, you can always ask your dad. Or, you know, a financial advisor. They're usually a little less biased.