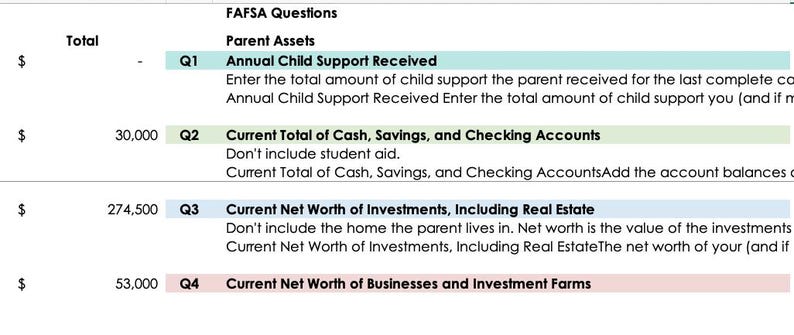
Hey there, let's grab a coffee and chat about something that's been on my mind lately - the current net worth of investments, or as the cool kids call it, the FAFSA (Free Application for Federal Student Aid). I mean, who doesn't love talking about money, right?
So, what's the deal with FAFSA?
FAFSA, my friend, is like the gatekeeper to the magical land of financial aid for college. It's where you spill the beans about your family's financial situation, and presto! You might qualify for grants, scholarships, or even loans with better terms. It's like a treasure hunt, but instead of a map, you've got a PDF form.
Let's talk numbers
Now, you might be wondering, "What's the current net worth of investments that FAFSA considers?" Well, grab your coffee, 'cause here we go. As of right now, for the 2021-2022 academic year, the expected family contribution (EFC) - that's the fancy term for how much you're expected to pay for college - is calculated based on a few things:
Must Read
- Your family's untaxed income, which includes things like wages, Social Security benefits, and unemployment compensation.
- Your family's taxed income, which is the amount of income that was actually taxed.
- Your family's net worth, which is the value of all the stuff your family owns (like a house, cars, or investments) minus any debts (like mortgages or car loans).
And here's where it gets interesting. For the 2021-2022 FAFSA, the protected asset allowance - that's the amount of assets that aren't counted towards your EFC - is $22,000 for dependent students and $65,000 for independent students. So, if your family's net worth is below that, you're in the clear! But if it's above, well, that's where things get a tad more complicated.
Investments, investments, investments
Now, let's talk about investments. FAFSA considers investments to be a part of your family's net worth. This includes things like stocks, bonds, mutual funds, and even retirement accounts (like 529 plans or IRAs). But here's the thing - not all investments are treated equally. For instance, cash (like money in a savings account) is assessed at a rate of 20%, while investments (like stocks and bonds) are assessed at a rate of 5.64%.
So, if you've got a chunk of change sitting in a savings account, FAFSA might expect you to use some of that to pay for college. But if that money's invested in the stock market, well, that's a different story. It's like FAFSA is giving you a little nudge to invest wisely - or at least, that's how I like to think about it.
 Do we really need to disclose true net worth ? : r/FAFSA
But wait, there's more!
Now, I know what you're thinking - "This is all well and good, but what if my family's financial situation changes? What if we have a sudden drop in income or a major expense?" Well, my friend, FAFSA has got you covered. You can appeal your EFC if you've got special circumstances that weren't reflected in your FAFSA application. This could be anything from a job loss to a medical expense to a natural disaster.
To appeal, you'll need to contact the financial aid office at the college you're planning to attend. They'll let you know what documents you need to provide to support your appeal. It's like having a safety net, just in case life throws you a curveball.
So, what's the takeaway?
Well, my coffee-chatting friend, the current net worth of investments that FAFSA considers is a moving target. It's all about your family's financial situation and how it's assessed by the FAFSA formula. But here's the thing - everyone's situation is unique. So, don't be discouraged if your family's net worth is high. There are still plenty of ways to make college affordable.
Remember, FAFSA is just one piece of the puzzle. There are also scholarships, grants, and loans to consider. And who knows? You might even find some hidden treasure in your family's financial history. So, keep your chin up, your eyes open, and your coffee hot. You've got this!